Multi-Goal SIP Planning: How to Manage Different Goals Simultaneously
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
Learn how to manage multiple SIPs for different goals, choose separate mutual funds, track investments, and decide whether to consolidate or separate SIPs.
Multi-Goal SIP Planning: How to Manage Different Goals Simultaneously
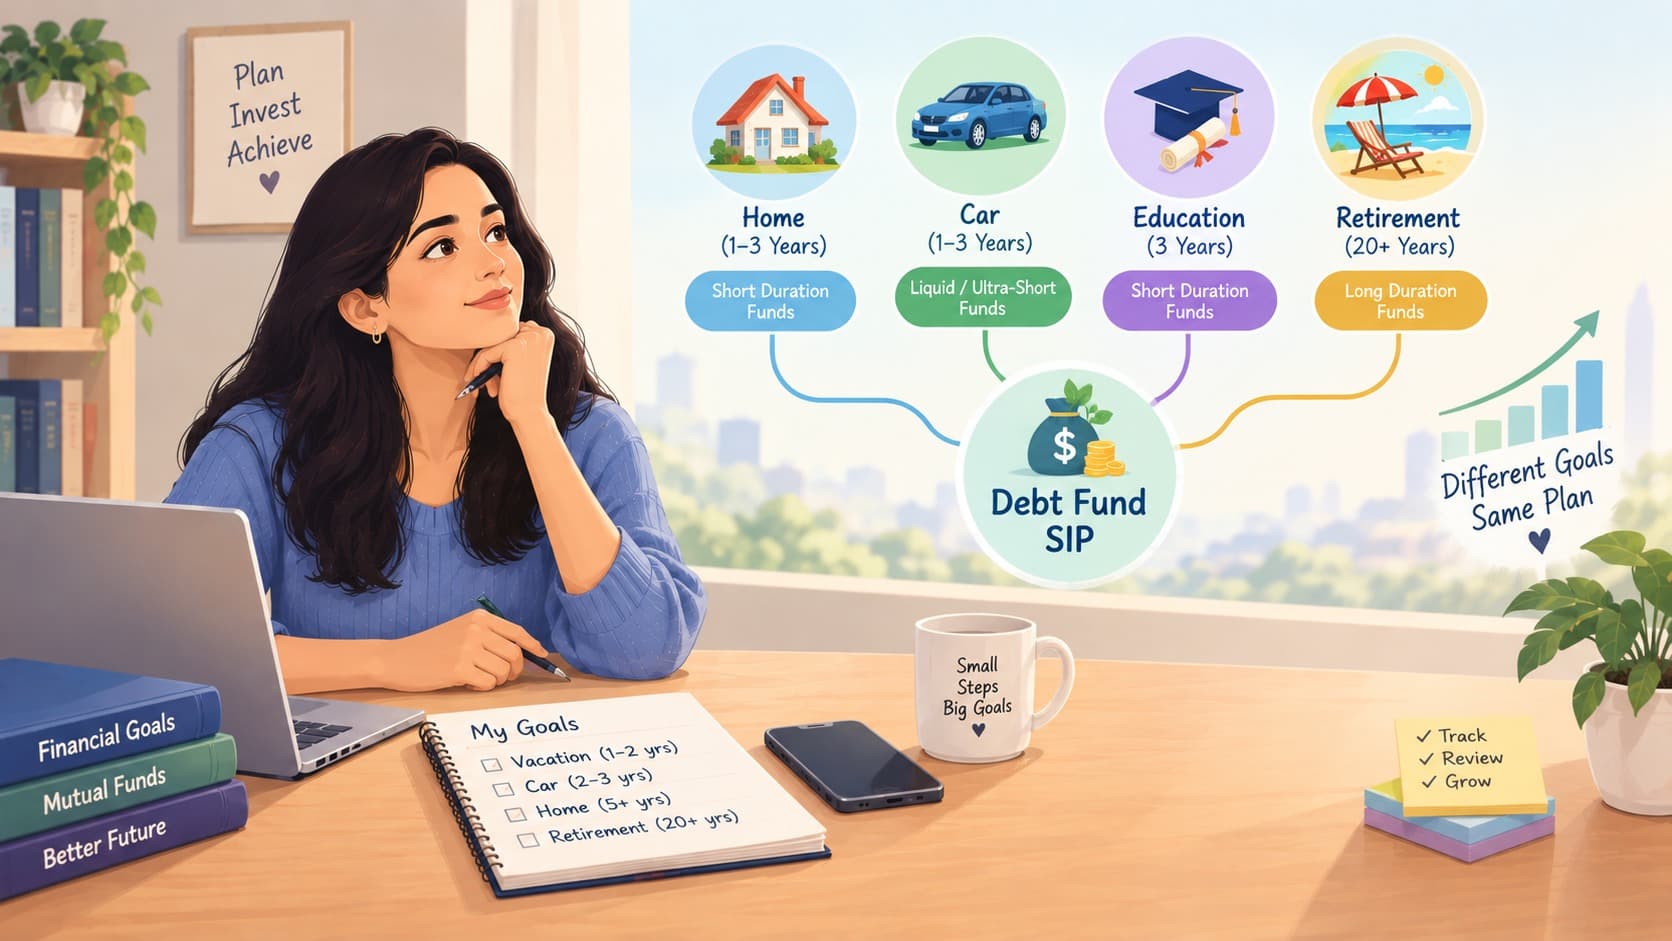
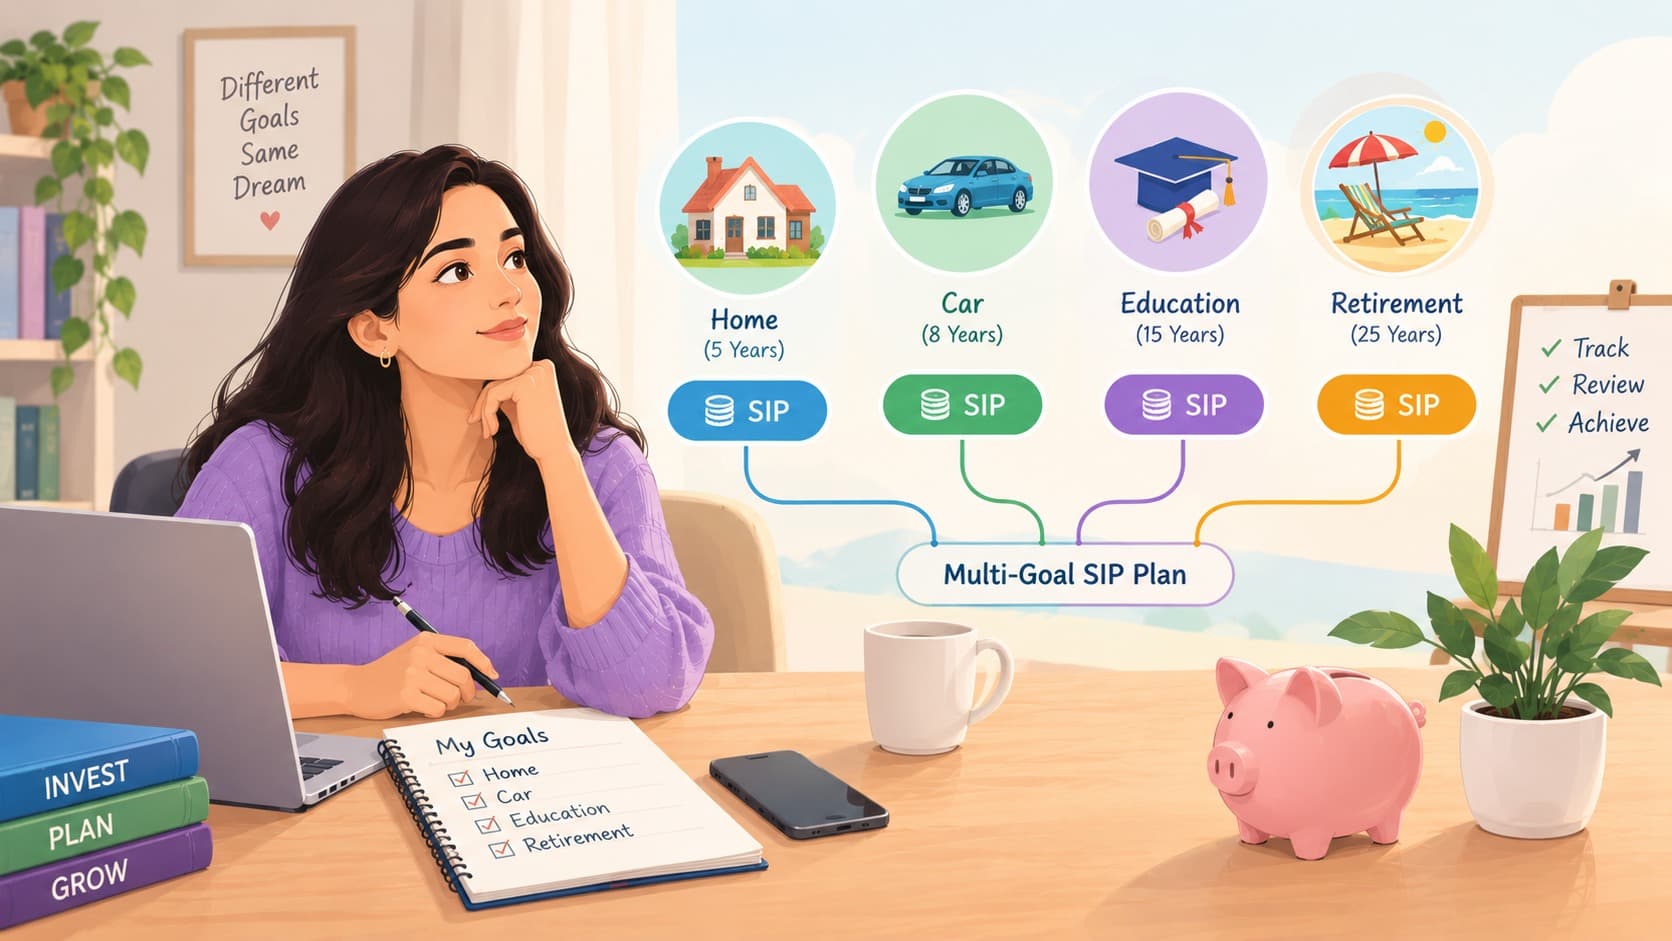
Most investors do not invest for just one financial goal. You might want to buy a car in three years, save for a home in seven years, fund your child's higher education in fifteen years, and build a retirement corpus over the next twenty-five years. Each goal has a different timeline, target amount, and level of flexibility.
This is where multi-goal financial planning becomes important. Instead of investing randomly and hoping your money will be sufficient when needed, you can assign a clear purpose to each investment and choose a suitable strategy.
However, managing multiple goals through systematic investment plans (SIPs) can become confusing. Should you start multiple SIPs or invest through a single SIP? Should every goal have a separate mutual fund? And how can you track progress without duplicating investments unnecessarily?
A structured approach to multiple SIPs for different goals can make investing easier to manage and help you stay focused on your financial priorities.
1. Start by Defining Your Financial Goals
Before choosing mutual funds or deciding how many SIPs to start, list your financial goals. For each goal, estimate the amount required, the time available, and how flexible the deadline is.
For example, consider these hypothetical goals:
Financial goal | Time horizon | Investment priority |
International vacation | 2 years | Capital stability |
Car purchase | 4 years | Controlled risk |
Child's higher education | 12 years | Long-term growth |
Retirement | 25 years | Long-term wealth creation |
These timelines are illustrative, not investment recommendations. The appropriate investment strategy also depends on your financial situation, risk tolerance, and the amount you have already saved.
Short-term goals generally leave less time to recover from market declines. Long-term goals may allow greater exposure to growth-oriented investments, depending on your risk capacity.
Once your goals are listed, estimate how much you need to invest monthly towards each one. This creates a practical starting point for managing multiple goals through SIPs.
2. One SIP vs Multiple SIPs: Which Is Better?
There is no universally correct answer to whether you should use one SIP or multiple SIPs. The right arrangement depends on how you want to organise and monitor your investments.
One SIP approach: Investing through one SIP may be simpler when you have a single goal, or when you deliberately use one investment as part of a broader portfolio. However, a single fund may not suit goals with very different timelines and risk requirements.
Multiple SIP approach: Multiple SIPs allow you to organise contributions around specific goals. For example, you could allocate ₹5,000 per month towards education and ₹8,000 towards retirement. Each contribution has a defined purpose, making progress easier to evaluate.
Remember that a SIP is simply a method of investing periodically. Starting more SIPs does not automatically improve diversification or returns.
The objective is to create an investment structure that matches your goals, not to increase the number of transactions.
3. Should You Choose Separate Mutual Funds for Separate Goals?
Using separate mutual funds for separate goals can improve clarity, but it is not compulsory to own a different fund for every goal.
Consider a portfolio with three goals:
Short-term goal: Money required within two years may be better suited to relatively stable, liquid options, depending on the investor's needs and risk tolerance.
Medium-term goal: A purchase planned in five years may require a cautious balance between growth potential and capital preservation.
Long-term goal: Retirement in twenty-five years may allow a greater allocation to equity, provided the investor can tolerate market fluctuations.
The examples illustrate the importance of matching investments to time horizons. Mutual funds, including debt and liquid funds, are not risk-free, and equity funds can experience significant losses.
You may use different funds for different goals, or use an existing fund for more than one goal if its investment strategy is appropriate for both. If you use one fund for several goals, maintain a clear record of how much of its value is assigned to each goal.
The key principle: Separate the tracking of your goals even when you do not separate every investment.
4. How to Avoid Overlap in Goal-Based SIPs
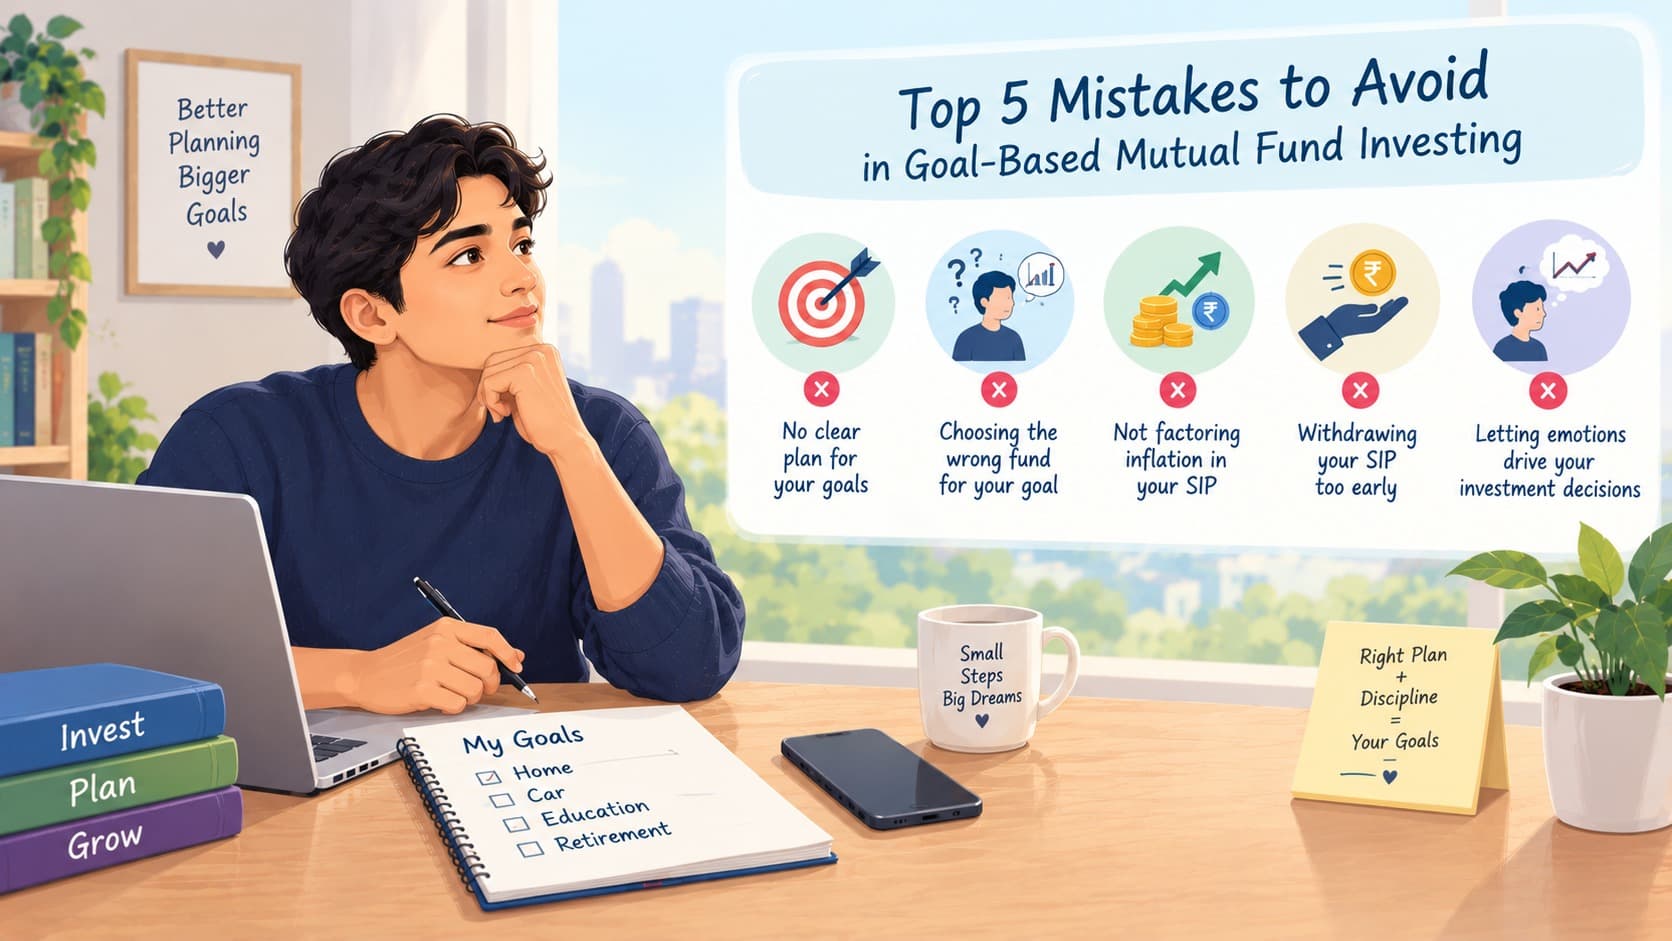
One common mistake in multi-goal planning is investing in several funds that hold similar securities or follow similar strategies. This can create the appearance of diversification without meaningfully spreading risk.
For example, holding three equity funds with substantial exposure to the same companies may not diversify your portfolio as much as expected.
To avoid overlap in goal-based SIPs:
Review each fund's investment objective and portfolio.
Identify whether two funds serve the same purpose.
Check your overall equity and debt allocation instead of reviewing each fund in isolation.
Avoid adding a new fund merely because it has performed well recently.
Review whether your portfolio still matches your goals and risk tolerance.
You should also avoid assigning the same money to multiple goals on paper. If ₹2 lakh is already earmarked for education, it cannot simultaneously be counted in full towards a car purchase and retirement.
Clear goal tagging prevents this kind of double-counting and gives you a more realistic picture of your financial position.
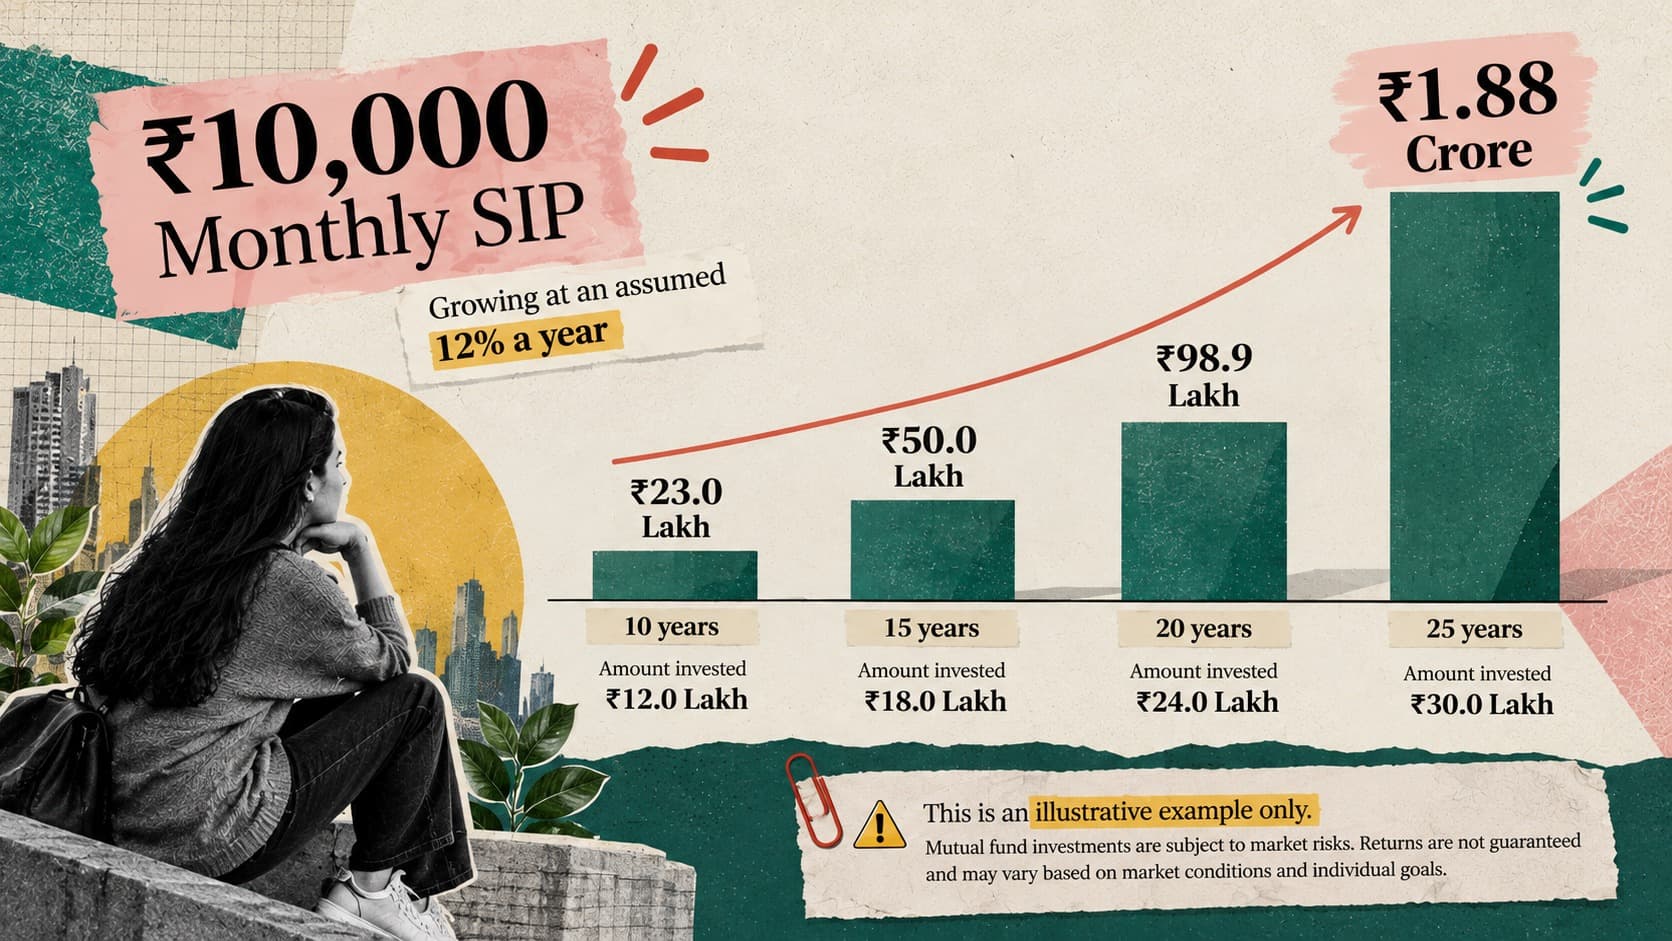
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
5. How to Track Multiple SIPs Without Confusion
Multi-goal SIP tracking does not need to be complicated. A spreadsheet or investment tracker can help you monitor contributions, portfolio values, deadlines, and remaining funding requirements.
Create a simple record containing:
Goal name and target amount
Target date
Amount already saved
Monthly SIP contribution
Mutual fund or investment assigned to the goal
Current portfolio value
Remaining amount required
Review the tracker periodically, such as every three or six months, and whenever your income or priorities change significantly.
Compare actual progress with your target, but do not expect investment returns to follow a fixed schedule. Market-linked investments fluctuate, so a projected corpus is an estimate rather than a guarantee.
As a goal approaches, reassess the portfolio's risk. You may need to gradually reduce exposure to volatile assets to protect money required soon. Any shift should account for taxes, exit loads, product conditions, and your personal circumstances.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
6. Consolidate vs Separate SIPs: Finding the Right Balance
Consolidation can reduce administrative effort, while separate SIPs can improve goal-level visibility. Neither approach is automatically superior.
Consolidating investments may be useful when several funds serve similar purposes, create unnecessary complexity, or make portfolio monitoring difficult. Before consolidating, check whether the investments are suitable for the goals they are meant to fund.
Keeping investments separate can be useful when goals have different timelines, risk requirements, or withdrawal dates. Separate arrangements may also make it easier to see whether you are on track for each goal.
A practical Kuberzo multi goal strategy is to organise investments around clearly defined financial objectives, review them together as one portfolio, and avoid unnecessary fund duplication.
You do not need dozens of mutual funds to manage multiple goals effectively. A manageable portfolio, clear allocations, and consistent tracking can be more useful than complexity.
Contact us for a more personalised guidance.
Conclusion
Managing multiple financial goals through SIPs becomes easier when every investment has a clear purpose. Start by defining your goals, estimating the monthly contributions required, matching investments to their timelines, and tracking progress consistently.
Whether you choose one SIP or multiple SIPs, focus on suitability, diversification, and transparency. Review your investments as your goals evolve, and avoid counting the same money towards different objectives.
A disciplined multi-goal plan helps you understand where you stand today and what adjustments may be needed to move towards your future financial priorities.
Frequently Asked Questions
Is it better to have multiple SIPs for different goals?
Multiple SIPs can make goal tracking easier, especially when your goals have different timelines. However, the number of SIPs should depend on your investment strategy and administrative preferences, not on the assumption that more SIPs automatically produce better returns.
Can I use one mutual fund for multiple financial goals?
Yes, if the fund's investment strategy and risk level are appropriate for those goals. Maintain separate records of the amount allocated to each goal and avoid counting the same investment value twice.
How many SIPs should I have?
There is no fixed ideal number. Start with the goals you need to fund and select suitable investments. Keep your portfolio manageable and avoid adding funds without a clear reason.
How often should I review my multi-goal SIP portfolio?
A review every three to six months can help you monitor progress. Also review your plan when your income, goals, target dates, or financial responsibilities change significantly.
Should I consolidate my mutual funds?
Consider consolidation when funds overlap or your portfolio has become unnecessarily complicated. Before making changes, evaluate investment suitability, diversification, tax implications, and exit loads.