Avoiding the Top 5 Mistakes in Goal-Based Mutual Fund Investing
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
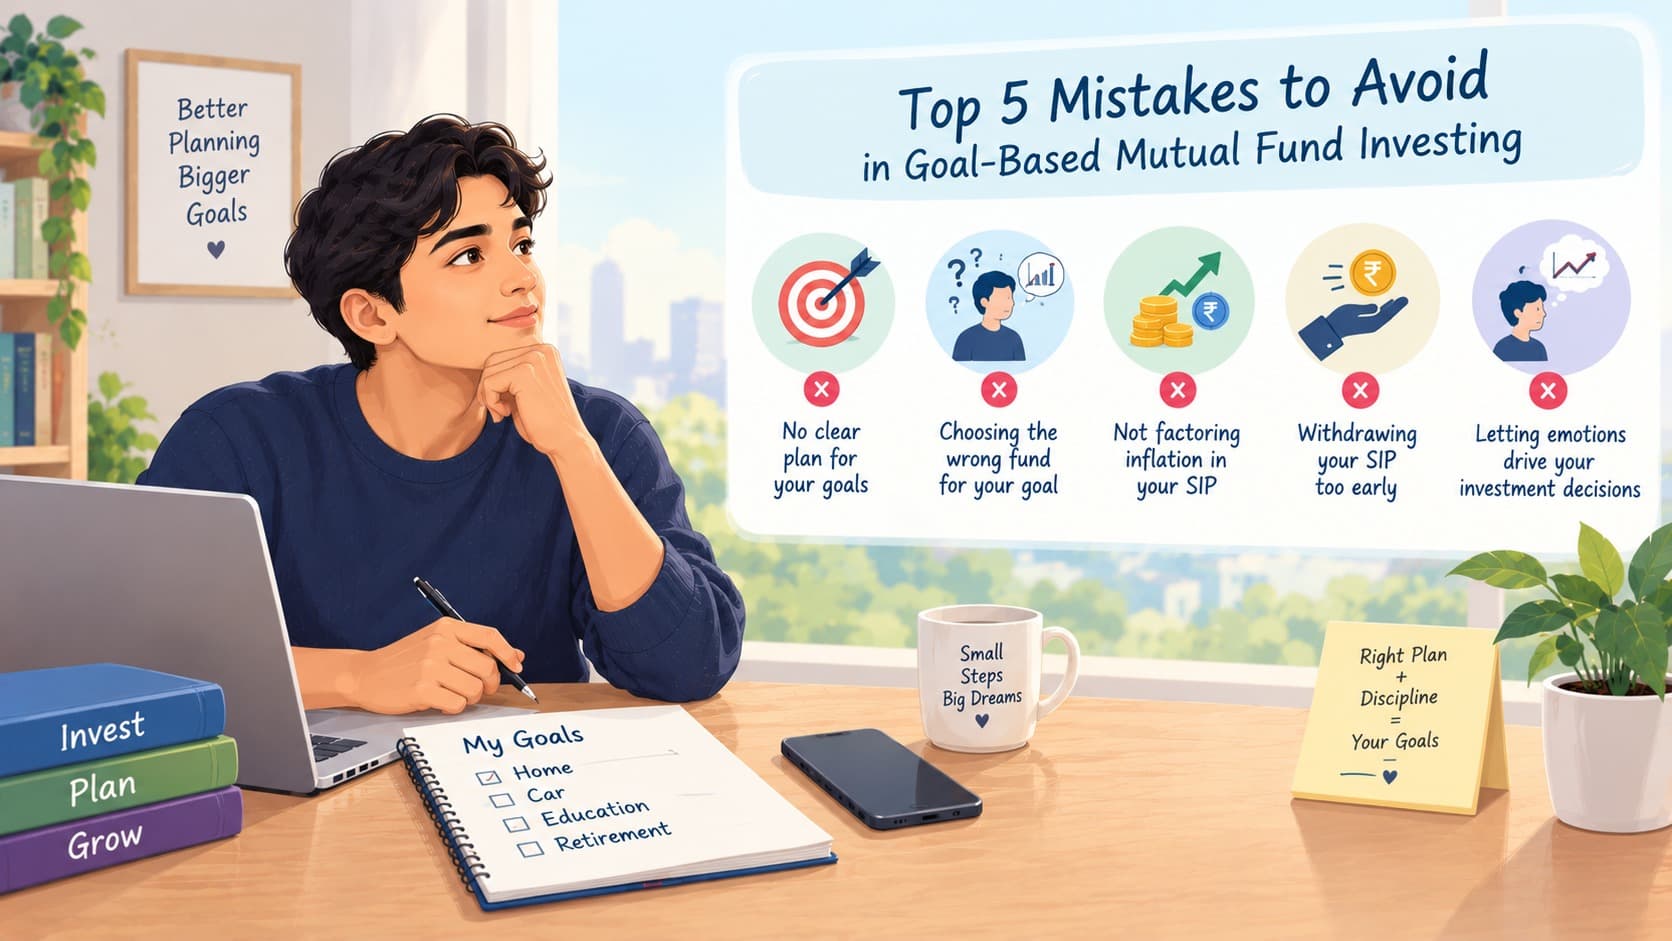
Avoid common mutual fund mistakes, from choosing the wrong fund to withdrawing SIPs early. Learn how to plan goals and invest with greater discipline.
Avoiding the Top 5 Mistakes in Goal-Based Mutual Fund Investing
Investing in mutual funds through systematic investment plans (SIPs) can help you work towards financial goals such as buying a home, funding your child's education, or building a retirement corpus. However, investing regularly alone does not guarantee that you will reach these goals.
Your results also depend on how well you plan, select investments, manage risk, and respond to market fluctuations. Small mistakes made early can create significant challenges when a financial deadline approaches.
Understanding common mutual fund errors can help you build a more disciplined investment strategy. Here are five important mistakes to avoid when investing for specific financial goals.
1. Setting Goals Without a Clear Plan
One of the most common mutual fund mistakes is investing without defining what the money is meant to achieve.
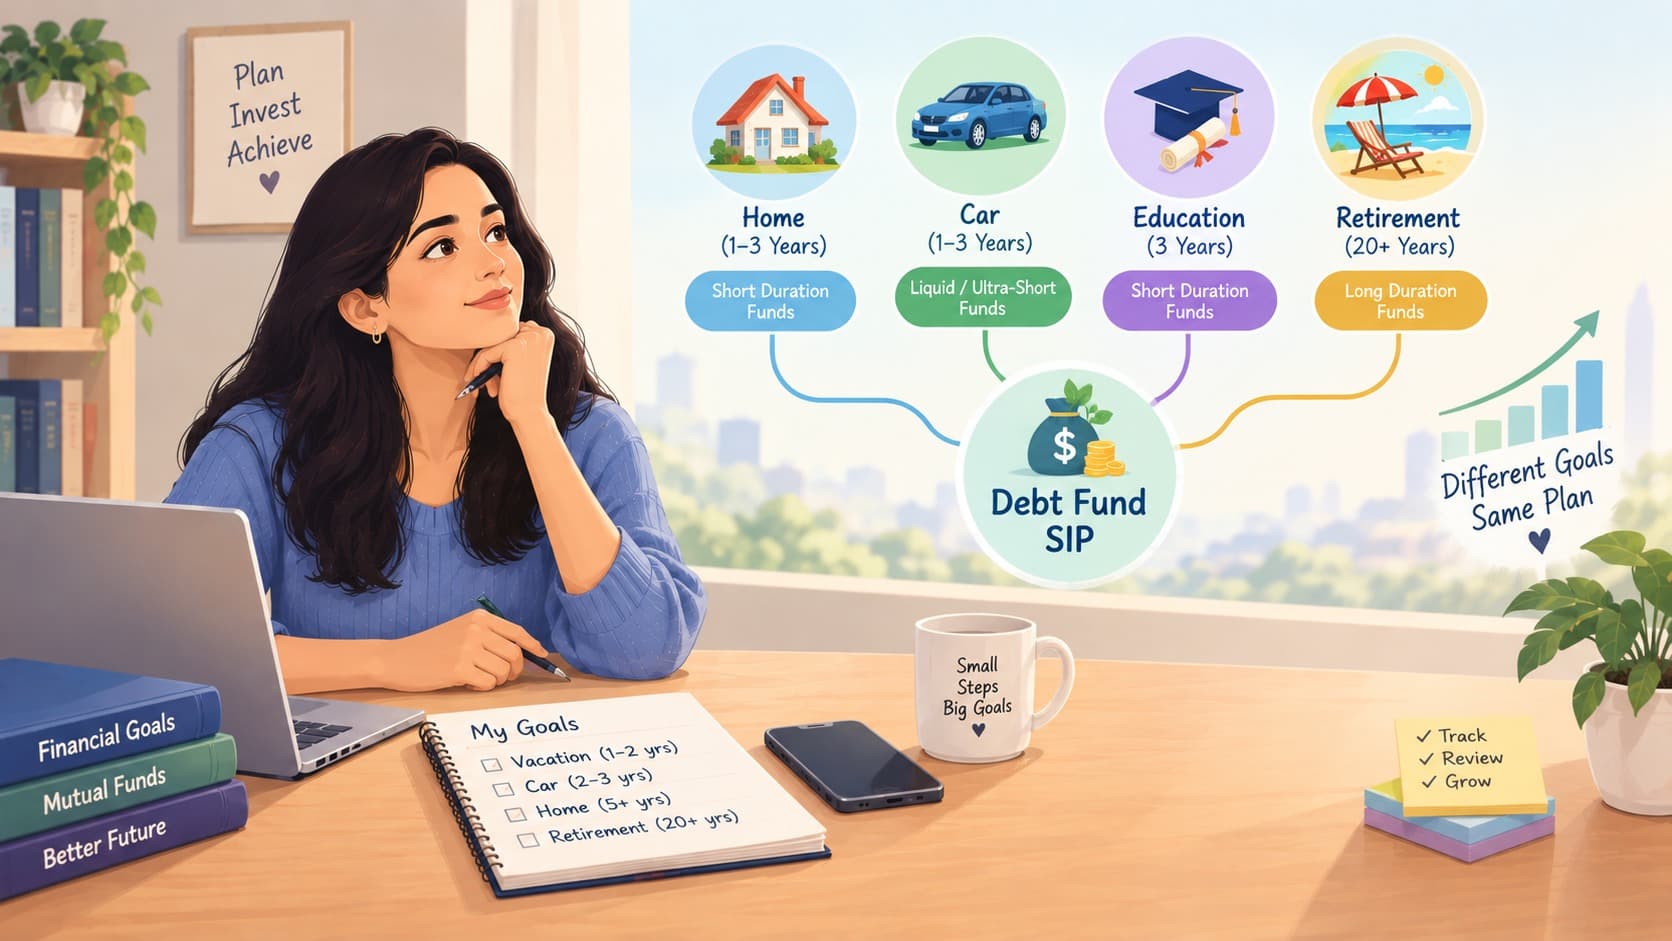
For example, investing ₹5,000 every month without a target amount or deadline makes it difficult to determine whether your contributions are sufficient. A retirement goal twenty years away requires a different approach from a car purchase planned in three years.
How to avoid it:
Identify each financial goal and its deadline.
Estimate the amount required, accounting for potential inflation.
Calculate a realistic monthly investment contribution.
Review your progress as your income and priorities change.
For instance, if you expect to need ₹10 lakh for a goal in five years, estimate the future cost rather than assuming today's price will remain unchanged.
A clear target makes it easier to choose suitable investments and measure progress. It also helps prevent wrong goal planning, where contributions are too small or the investment strategy does not match the deadline.
2. Picking the Wrong Mutual Fund for Your Goal
Not every mutual fund is suitable for every financial objective. Choosing a fund based only on recent returns, popularity, or recommendations can expose you to risks that do not match your needs.
Equity funds can experience substantial short-term declines, making them potentially unsuitable for money you must use very soon. Debt funds may have lower volatility than equity funds, but they can still carry credit, interest rate, and liquidity risks.
How to avoid it:
Match the investment's risk profile to your goal's time horizon.
Review the fund's investment objective, portfolio, expenses, and Riskometer.
Consider your ability to tolerate losses, not just your willingness to take risks.
Avoid selecting funds solely because they recently outperformed their peers.
For long-term goals, growth-oriented investments may be appropriate depending on your circumstances. For short-term goals, capital stability and access to money may deserve greater priority.
The objective is not to find the fund with the highest recent return. It is to select investments that fit the financial goal.
3. Not Factoring Inflation into Your SIP
Inflation reduces the purchasing power of money over time. A goal that appears affordable today may cost considerably more when you are ready to pay for it.
Suppose higher education costs ₹10 lakh today. If education expenses rise by an illustrative 6% annually, the cost could reach approximately ₹17.9 lakh in ten years.
This example is an illustration, not a prediction of future inflation. Actual costs may rise faster or slower.
How to avoid it:
Estimate the future cost of each major goal.
Use a reasonable inflation assumption based on the expense involved.
Recalculate your required monthly SIP periodically.
Increase contributions when your income allows and your plan requires it.
Education, healthcare, housing, and lifestyle expenses can experience different rates of inflation. Using one assumption for every goal may not accurately reflect your future needs.
Ignoring inflation can leave you with a sizeable corpus that still falls short of the amount required.
4. Withdrawing Your SIP Investments Too Early
Withdrawing SIP investments before reaching the intended goal can disrupt your financial plan. Investors sometimes redeem units during market declines because they fear further losses, while others use goal-based savings for unplanned purchases.
Early withdrawals can reduce the amount available for the original goal and leave less capital invested for potential future growth.
However, staying invested at all costs is not always the right decision. Genuine emergencies or changing financial circumstances may require you to access your savings.
How to avoid it:
Maintain an emergency fund separate from long-term goal investments.
Avoid reacting impulsively to short-term market movements.
Review your financial priorities before redeeming investments.
Check exit loads, taxes, and other redemption conditions.
If your goal is approaching, gradually reassess the risk in your portfolio rather than waiting until the last moment. Protecting money needed soon may be more important than seeking additional returns.
The key is to distinguish between an essential withdrawal and an avoidable one.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
5. Letting Emotions Drive Investment Decisions
Behavioural biases in SIP investing can affect even experienced investors. Fear may cause someone to stop investing during a market correction, while greed may encourage them to chase funds that have recently performed exceptionally well.
Another common mistake is checking returns too frequently and treating every decline as a sign that the investment strategy has failed.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
How to avoid it:
Set a review schedule instead of reacting to every market movement.
Evaluate performance against your goals and the fund's stated strategy.
Avoid switching funds solely because another scheme has recently delivered higher returns.
Review your asset allocation when your financial situation or goal timeline changes.
SIP investing encourages regular contributions, but discipline does not mean ignoring every warning sign. Review genuine changes in a fund's risk profile, investment strategy, or suitability.
A written investment plan can help you make decisions based on your goals rather than temporary emotions.
Contact us for a more personalised guidance.
Conclusion
Avoiding common mutual fund errors starts with clear financial goals, suitable fund selection, realistic inflation estimates, disciplined withdrawals, and thoughtful decision-making.
A successful goal-based SIP strategy is not about chasing the highest returns or investing in the largest number of funds. It is about matching your investments to your needs and reviewing them as circumstances change.
Use this Kuberzo mutual fund guide as a starting point to assess your current approach. With realistic targets and consistent reviews, you can identify gaps early and make more informed decisions towards your financial goals.
Frequently Asked Questions
What are the most common mutual fund mistakes?
Common mistakes include investing without clear goals, choosing unsuitable funds, ignoring inflation, withdrawing investments prematurely, and making emotional decisions during market fluctuations.
Can I lose money by investing through SIPs?
Yes. An SIP is a method of investing, not a guarantee against losses. The value of mutual fund investments can rise or fall depending on market conditions and the underlying assets.
Should I stop my SIP when the market falls?
Not automatically. Review your goals, time horizon, and ability to tolerate risk before making a decision. If your circumstances or investment's suitability have changed, reassess your plan rather than reacting purely out of fear.
Why should inflation be considered when planning SIPs?
Inflation increases the future cost of goods and services. If you plan using today's prices alone, your eventual investment corpus may not be sufficient to meet the goal.
How often should I review my goal-based SIP portfolio?
A review every three to six months can be a useful starting point. Also review your plan when your income, financial goals, risk tolerance, or investment timeline changes significantly.