Debt Mutual Fund SIPs: The Best Way to Save for 1-to-3 Year Goals
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
Discover how debt mutual fund SIPs can support 1-to-3 year goals, compare debt funds with FDs, and understand risks before investing.
Debt Mutual Fund SIPs: The Best Way to Save for 1-to-3 Year Goals
Saving for a goal that is only one to three years away requires a different approach from investing for retirement. You might be planning a family holiday, saving for a vehicle, preparing for a house deposit, or building funds for an upcoming expense. In each case, protecting the money you have accumulated is often more important than chasing high returns.
A debt fund SIP can help you invest regularly towards these goals. Debt mutual funds invest primarily in instruments such as government securities, corporate bonds, treasury bills, and money market instruments. Their risk and return potential depend on the securities held in the portfolio.
However, debt funds are not guaranteed-return products. For short-term goals, the right choice depends on your deadline, need for predictable returns, tolerance for fluctuations, and willingness to accept investment risk.
1. What Is a Debt Fund SIP?
A systematic investment plan (SIP) allows you to invest a fixed amount at regular intervals in a mutual fund. A debt fund SIP applies this method to a debt mutual fund.
For example, if you want to save ₹1.2 lakh over two years, you could plan monthly contributions towards that target. Your eventual balance will depend on your contributions, expenses, and investment performance.
Debt funds may be worth considering for conservative goal-based investing because they generally have lower volatility than equity funds, although the level of risk varies by scheme.
Their main risks include:
Interest rate risk: Bond prices can fall when market interest rates rise.
Credit risk: An issuer may delay or fail to repay its debt.
Liquidity risk: Some securities may be difficult to sell quickly at a fair price.
A low-risk SIP is therefore not the same as a risk-free investment.
2. Which Debt Funds Suit 1-to-3 Year Goals?
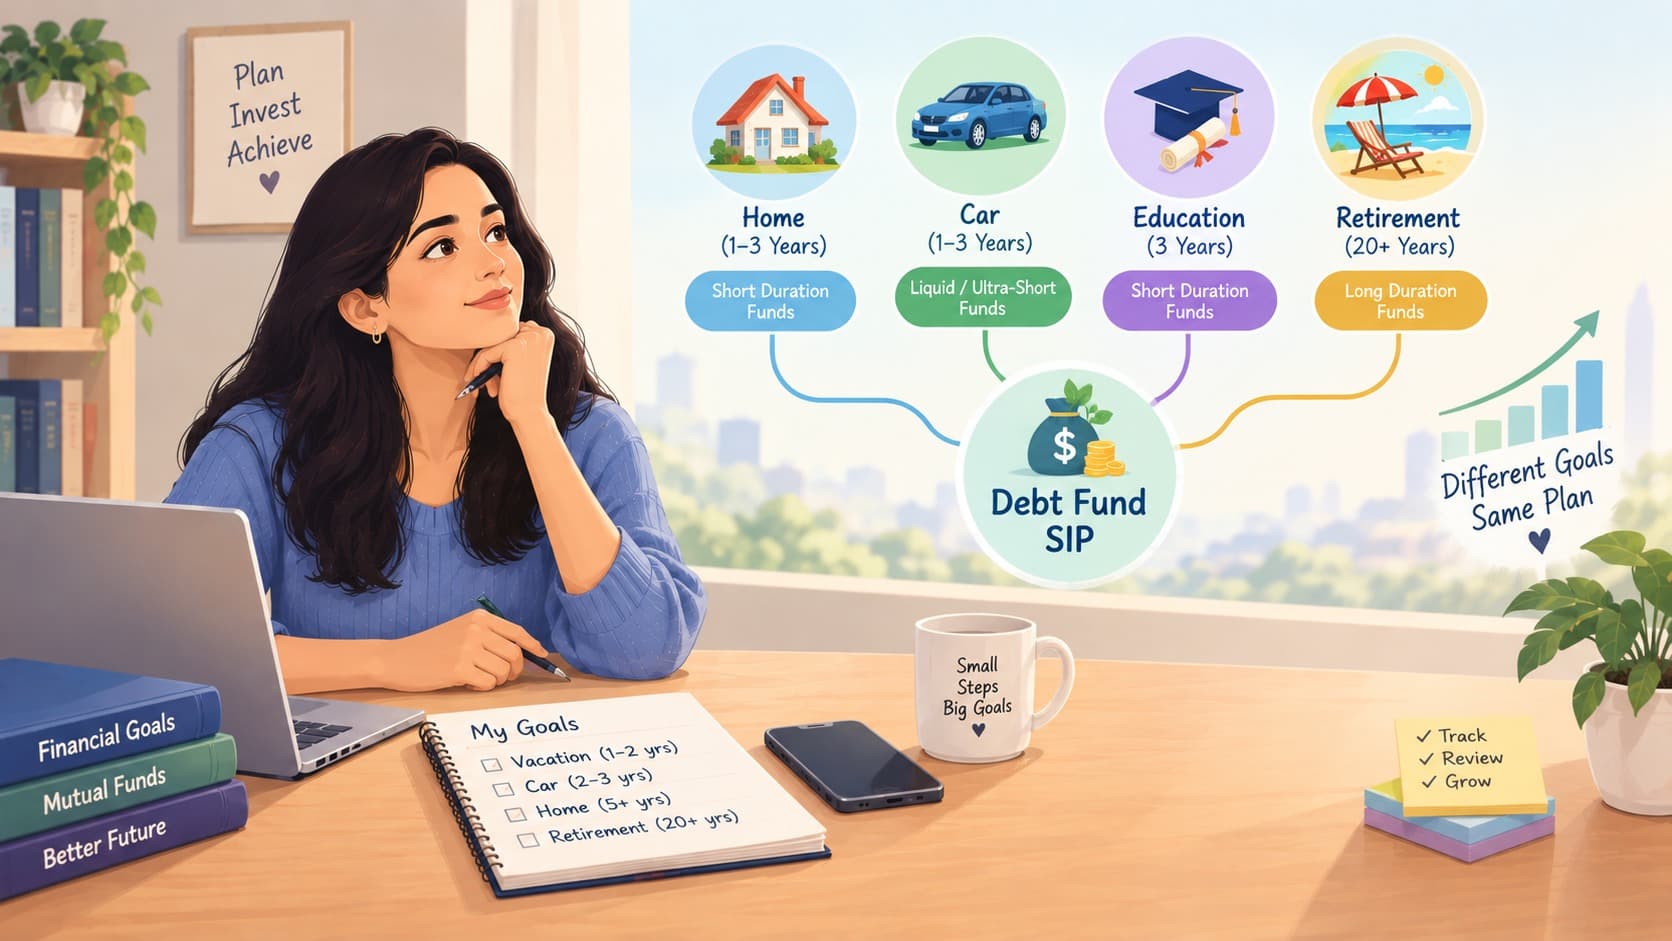
Choosing a suitable category means matching the fund's portfolio and risks to the time remaining before you need the money. There is no single category that is best for every short-term goal.
Fund category | Potential use | What to consider |
Overnight funds | Very short holding periods | Returns can vary with short-term interest rates |
Liquid funds | Parking money for short periods | Credit quality, liquidity and expenses |
Ultra-short-duration funds | Short-term savings plans | Portfolio duration and credit exposure |
Short-duration funds | Some goals with a horizon of around 1–3 years | Interest rate sensitivity and credit quality |
These are general examples, not guaranteed matches for particular goals. A short-duration fund can fluctuate in value, and its portfolio may not mature exactly when you need your money.
When evaluating the best debt funds for a three-year goal, examine the scheme's portfolio, expense ratio, Riskometer, credit quality, and interest rate sensitivity. Do not select a fund solely because it recently delivered higher returns.
3. Debt Mutual Fund vs FD for Short-Term Goals
Fixed deposits (FDs) and debt mutual funds can serve different purposes. The better choice depends on whether you prioritise predictable maturity proceeds, flexibility, or market-linked returns.
Fixed deposits: An FD generally offers a stated interest rate for a specified tenure, subject to its terms and the institution's ability to meet its obligations. It may suit investors who want more predictable proceeds at a known date. Premature withdrawal rules and penalties should be checked.
Debt mutual funds: These provide access to a professionally managed portfolio of debt securities. They can offer flexibility, but their returns are not fixed and the value of your investment may fall. Redemption proceeds depend on the fund's net asset value and applicable scheme terms.
Tax treatment also matters. Tax rules for debt mutual funds differ from those for bank deposits and can depend on the investment date and applicable law. Review the current rules before deciding.
For a goal with a non-negotiable deadline, compare the certainty of an FD's maturity value with the potential fluctuations of a debt fund. You do not need to choose debt funds simply because you are investing through an SIP.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
4. How to Plan a SIP for a Short-Term Goal
A practical goal-based debt investing process starts with the amount you need and the date you need it.
Step 1: Set a target. Estimate the expense and include a buffer for rising costs.
Step 2: Calculate your monthly contribution. Divide the amount still required by the number of months remaining. Treat any expected investment return as uncertain rather than guaranteed.
Step 3: Match the investment to the deadline. Prioritise liquidity and capital stability when the goal is close. Avoid taking more risk to compensate for starting late.
Step 4: Check the fund's risk profile. Read the scheme information document, portfolio disclosures, expenses, and Riskometer.
Step 5: Review progress regularly. Check whether your contributions remain sufficient and whether the portfolio still fits your goal.
Step 6: Reduce uncertainty as the deadline approaches. Consider moving money needed soon into an appropriate, lower-volatility option. Account for redemption timelines, taxes, and exit loads before making changes.
This process helps make a debt fund SIP part of a plan rather than a standalone product choice.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
5. Common Mistakes to Avoid
Investors sometimes assume that all debt funds are equally safe or that a short holding period eliminates market risk. Neither assumption is correct.
Avoid choosing funds only on recent performance, ignoring credit quality, or investing in a longer-duration strategy without understanding interest rate risk. Also, do not put emergency money or funds needed immediately into an investment without checking how quickly and reliably you can access them.
A Kuberzo debt SIP strategy should begin with the goal's timeline and risk requirements, not with a promise of higher returns. For low-volatility SIPs for short goals, compare suitable debt funds with FDs and other savings options before investing.
Contact us for a more personalised guidance.
Conclusion
Debt mutual fund SIPs can help investors build savings gradually for certain one-to-three-year goals. Their suitability depends on the fund's portfolio, credit quality, interest rate sensitivity, and the investor's need for certainty.
Compare debt mutual funds with FDs, review the risks, and match the investment to the date the money is required. If a shortfall would disrupt an essential goal, prioritise predictability and capital stability over chasing additional returns.
Frequently Asked Questions
Are debt mutual fund SIPs safe for short-term goals?
Debt funds can have lower volatility than equity funds, but they are not risk-free. Interest rate movements, credit events, and liquidity conditions can affect their value.
Which debt fund is best for a three-year goal?
There is no universally best fund. Compare short-duration and other suitable debt fund categories based on portfolio quality, duration, expenses, risk level, and your ability to tolerate fluctuations.
Is a debt mutual fund better than an FD?
Not always. FDs may offer more predictable maturity proceeds, while debt funds provide market-linked returns and different liquidity features. Compare risk, tenure, taxation, and withdrawal conditions.
Can I use an SIP for a one-year goal?
Yes, an SIP can help you contribute regularly, but the investment itself must suit your short deadline. Consider whether a suitable FD or other lower-risk savings option offers the certainty you need.
Do debt mutual funds guarantee returns?
No. Debt mutual fund returns are not guaranteed, and the value of your investment can decline. Read the scheme documents and assess the risks before investing.