What Is AUM in Mutual Funds? Meaning & Does Fund Size Affect Returns
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
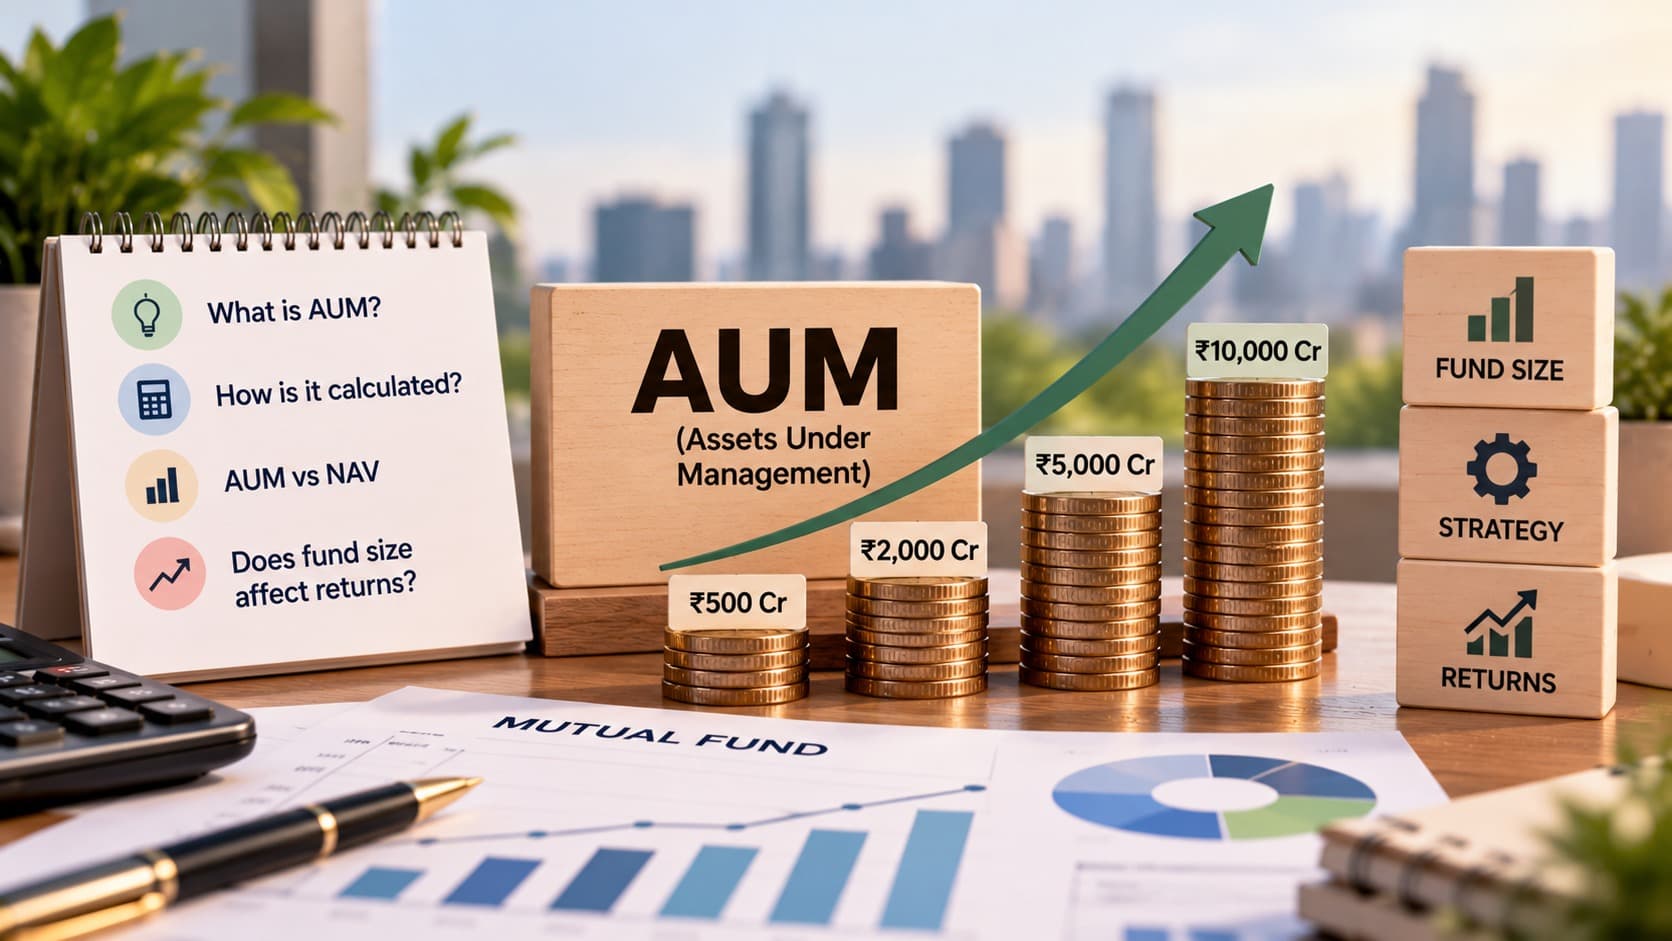
Understand AUM in mutual funds, how fund size affects returns, AUM vs NAV, and what investors should check before choosing a fund.
Introduction
When comparing mutual funds, investors often look at past returns, expense ratios, ratings and fund managers. However, there is another metric worth understanding: Assets Under Management (AUM).
You may have noticed that some mutual funds manage thousands of crores, while others have a much smaller portfolio. Does a larger fund automatically perform better? Can a smaller fund generate higher returns? And should you consider fund size before investing?
Understanding what AUM in mutual funds is can help you answer these questions and evaluate a scheme more effectively.
AUM indicates the total value of assets a mutual fund scheme manages on behalf of its investors. It gives you an idea of the fund's size, but it does not tell you everything about its performance, risk or suitability.
In this guide, we explain the assets under management meaning, the difference between AUM and NAV, how fund size can affect performance, and what investors should consider before choosing a mutual fund.
What Is AUM in Mutual Funds?
AUM stands for Assets Under Management. It represents the total market value of the investments and other assets managed by a mutual fund scheme on behalf of its investors, as reported under the applicable valuation and reporting rules.
In simple terms, AUM tells you how much money a fund manages.
For example, suppose a mutual fund scheme has an AUM of ₹5,000 crore. This means the scheme manages assets worth approximately ₹5,000 crore. The money may be invested in shares, bonds, government securities or other instruments, depending on the scheme's investment objective.
AUM can change over time due to several factors:
New investments: Investors put additional money into the scheme through lump-sum investments or SIPs.
Redemptions: Investors withdraw money from the scheme.
Market movements: The value of the securities held by the fund rises or falls.
Income and distributions: Interest, dividends and other portfolio-related cash flows can affect the fund's assets.
Therefore, an increase in AUM does not necessarily mean that the fund has delivered strong returns. The increase could be due to fresh investments, favourable market movements or a combination of factors.
Assets Under Management Meaning in Finance
The AUM meaning in finance extends beyond mutual funds. It is used to describe the value of assets managed by financial institutions, investment managers and other financial service providers on behalf of clients.
For mutual fund investors, AUM is primarily a measure of the size of a scheme. It can help you understand how much capital the fund manager oversees and whether the fund has grown over time.
However, AUM should not be treated as a direct measure of investment quality. A fund with a large AUM may have a strong track record, but it may also underperform its benchmark. Similarly, a smaller fund can perform well if its investment strategy, portfolio and execution are effective.
Think of AUM as a measure of scale, not a guarantee of success.
How Is AUM Calculated?
The reported AUM of a mutual fund scheme generally reflects the market value of its assets at a particular point in time, calculated according to applicable valuation and reporting conventions.
A simplified illustration is:
AUM = Total Value of Managed Assets
Suppose a mutual fund scheme holds:
Equity shares worth ₹600 crore
Bonds worth ₹250 crore
Cash and other assets worth ₹50 crore
The total value of these assets is ₹900 crore. If the scheme also has liabilities of ₹10 crore and the reporting measure is net assets, its net assets would be ₹890 crore.
The precise AUM figure may depend on the reporting convention being used. When comparing figures, make sure you are looking at the same type of measure and reporting date.
AUM is not fixed. If the market value of the portfolio changes or investors add or withdraw money, the reported figure can change accordingly.
AUM vs NAV Difference: What Should Investors Know?
AUM and Net Asset Value (NAV) are related, but they measure different things. Understanding the AUM vs NAV difference helps you avoid a common mistake when comparing mutual funds.
Feature | AUM | NAV |
Meaning | Total value of assets managed by a scheme | Net asset value per unit |
What it indicates | The size of the fund | The value of one unit |
What affects it | Investments, redemptions and market movements | Portfolio values, liabilities and units outstanding |
How investors use it | To understand fund size and scale | To determine the per-unit value for transactions |
Does a higher figure mean better returns? | No | No |
For example, Fund A may have an AUM of ₹10,000 crore and an NAV of ₹50, while Fund B may have an AUM of ₹2,000 crore and an NAV of ₹100.
Fund B is not automatically more expensive, and Fund A is not automatically a better investment. The NAV mainly indicates the value per unit, while AUM indicates the scale of the scheme.
When comparing funds, focus on performance over appropriate periods, risk, costs, portfolio quality and suitability rather than simply choosing the fund with the highest AUM or lowest NAV.
Does High AUM Affect Returns?
The answer to whether high AUM affect returns is: it can influence how a fund is managed, but it does not directly determine the returns investors earn.
A large AUM can provide certain advantages. It may allow a fund to spread operating costs across a larger asset base and provide access to a wider range of investments, subject to the scheme's mandate.
However, a very large fund may also face practical challenges, particularly when investing in less liquid securities. The impact depends on the fund category, investment strategy and the markets in which it operates.
Here are the main factors to understand.
1. Liquidity and Trading Flexibility
A large fund may need to buy or sell substantial quantities of securities to invest incoming money or meet redemptions.
In highly liquid large-cap stocks, this may be relatively manageable. In smaller companies with limited trading volumes, placing large orders can become more difficult. The fund may need more time to build or exit a position, and large trades can affect the prices at which transactions take place.
This is one reason fund size can matter more in small-cap funds than in some large-cap strategies.
2. Investment Opportunities
A smaller fund may sometimes have greater flexibility to invest in less widely traded securities or take positions in companies where the amount that can be invested is limited.
As a fund grows, the same investment opportunities may become too small to make a meaningful difference to the overall portfolio.
However, a smaller AUM is not automatically an advantage. Smaller funds may also face challenges such as limited operating scale, shorter track records or a less established investment process.
3. Expense Ratio and Operating Costs
AUM can influence the economics of running a mutual fund. Some operating expenses can be spread across a larger asset base, although the actual expense ratio depends on the applicable regulatory framework, scheme structure and expenses.
A lower expense ratio can benefit investors over time, all else being equal. However, a fund's AUM alone does not tell you what its expense ratio will be.
4. Portfolio Management
Managing a large pool of money requires disciplined execution, risk management and portfolio construction.
A skilled fund manager may handle a large scheme effectively if the investment universe is sufficiently liquid and the strategy can accommodate the fund's size. In other cases, growth in AUM may make it harder to implement the original investment strategy without affecting trading costs or portfolio flexibility.
This means the impact of large AUM on fund performance depends on how well the fund's investment process adapts as the scheme grows. A regular mutual fund portfolio review can help you evaluate portfolio quality, risk exposure and whether your investments remain aligned with your goals.
Ideal AUM for Small Cap Funds: Does Size Matter More?
There is no universally accepted ideal AUM for small-cap funds. A suitable size depends on the investment strategy, the liquidity of the stocks held, the fund manager's approach and the scheme's ability to deploy capital effectively.
Small-cap stocks often have lower trading volumes than large-cap stocks. When a fund manages a large amount of money, building or selling positions in these companies may become more challenging.
For example, a fund managing ₹500 crore and a fund managing ₹10,000 crore may both want to invest in a small company. The larger fund may need to purchase a much greater number of shares to establish a position that has a meaningful impact on its portfolio. That can make execution more difficult if trading volumes are limited.
However, this does not mean that investors should always prefer small-cap funds with lower AUM. A smaller fund can still take excessive risks or underperform, while a larger fund may have strong research capabilities and a well-managed portfolio.
Instead of setting an arbitrary AUM threshold, investors should assess:
Portfolio concentration and diversification
Liquidity of the underlying stocks
Investment strategy and consistency
Performance across different market conditions
Expense ratio and risk measures
Fund manager experience and investment process
Fund size should be one part of your evaluation, not the deciding factor.
AUM Growth in Indian Mutual Funds: What Does It Tell Us?
The AUM growth in Indian mutual funds reflects changes in investor participation, market valuations, investment flows and the overall expansion of the mutual fund industry.
When more investors invest through SIPs or lump sums, scheme assets may grow. Rising stock and bond prices can also increase AUM even when investors do not add new money.
Similarly, AUM can decline when markets fall or investors redeem their units.
This distinction matters because fund growth and investment performance are not the same thing. A scheme can attract significant new investments without outperforming its benchmark. Another scheme may deliver strong returns but experience slower AUM growth because it attracts fewer new investors.
When evaluating a fund's AUM trend, consider the following:
Growth over time: Has the scheme's size increased steadily or changed sharply?
Source of growth: Is the increase driven by fresh inflows, market performance or both?
Category context: Is the scheme's size appropriate for its investment universe?
Investment execution: Has the fund maintained its strategy as its assets have grown?
Use AUM trends as context, not as a standalone signal to buy or sell.
How to Use AUM When Choosing a Mutual Fund
AUM is most useful when combined with other measures of fund quality. Before selecting a scheme, assess your investment risk profile to understand whether its potential risks align with your comfort level. Before investing, consider these steps:
1. Compare funds within the same category. AUM is more meaningful when you compare similar schemes with similar investment mandates.
2. Review long-term performance. Check returns over multiple periods and compare them with an appropriate benchmark. Past performance does not guarantee future results.
3. Understand the portfolio. Look at the securities held, sector exposure, diversification and liquidity.
4. Check costs and risks. Review the expense ratio, volatility and other relevant risk measures.
5. Evaluate consistency and management. Consider whether the investment process is clear and whether the fund has managed different market conditions effectively.
This approach helps you assess fund size without giving it more importance than it deserves.
Conclusion
AUM is an important metric in mutual fund investing because it shows the scale of a scheme's managed assets. However, a larger AUM does not automatically mean better returns, stronger management or lower risk.
Fund size can influence liquidity, trading flexibility, operating costs and portfolio construction. These factors may be particularly relevant for small-cap funds, where the availability and trading volume of securities can limit how much capital a fund can deploy efficiently.
For investors, the best approach is to consider AUM alongside performance, risk, expense ratio, portfolio quality and investment objectives. Use fund size as one part of your decision-making process rather than treating it as a shortcut to identifying the best mutual fund.
Ultimately, a suitable fund aligns with your financial goals, investment horizon and risk tolerance, regardless of whether its AUM is large or small. Using a goal-based financial planner can help you connect your investment choices with your time horizon and long-term financial objectives.
Frequently Asked Questions
What is AUM in mutual funds?
AUM stands for Assets Under Management. It represents the value of assets a mutual fund scheme manages on behalf of investors, according to the applicable reporting measure.
Does high AUM affect returns?
High AUM can affect liquidity, trading flexibility and portfolio management, particularly in less liquid markets. However, it does not automatically lead to higher or lower returns.
What is the difference between AUM and NAV?
AUM indicates the total size of a scheme's managed assets, while NAV represents the net asset value per unit. Neither a higher AUM nor a lower NAV automatically makes a fund a better investment.
What is the ideal AUM for small-cap funds?
There is no single ideal AUM for small-cap funds. Investors should consider the liquidity of the underlying stocks, the fund's strategy, portfolio construction, performance and risk management.
Should I choose a mutual fund with higher AUM?
Not based on AUM alone. Compare the fund's performance, risk, expense ratio, portfolio quality, investment process and suitability for your financial goals before making a decision.