Expense Ratio in Mutual Funds: What Is TER & Direct vs Regular Charges
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
Understand expense ratio in mutual funds, what TER means, Direct vs Regular charges, SEBI limits and how fund expenses affect long-term returns.
When comparing mutual funds, investors often focus on historical returns, ratings and portfolio performance. However, there is another factor that can affect how much money they accumulate over time: the expense ratio.
The expense ratio in mutual funds represents the recurring expenses charged by a mutual fund scheme for managing and operating the fund. Even though investors generally do not pay this amount separately, these expenses affect the scheme's Net Asset Value (NAV) and, consequently, its returns.
This becomes particularly important when comparing Direct and Regular Plans of the same mutual fund. Both plans invest in the same portfolio, but their expense ratios differ because of distribution-related costs.
Understanding what Total Expense Ratio (TER) is, how it works and how to compare fund charges can help investors make more informed investment decisions.
What Is Total Expense Ratio (TER) in Mutual Funds?
The Total Expense Ratio (TER) is the annual percentage of a mutual fund scheme's assets used to cover eligible recurring expenses associated with managing and operating the scheme.
These expenses may include:
Investment management and advisory fees
Administrative and operating expenses
Registrar and transfer agent fees
Custodial and audit expenses
Marketing and distribution-related expenses, where applicable
Other permitted scheme expenses
The TER is expressed as a percentage of a scheme's assets. For example, if a mutual fund has an expense ratio of 1%, the annualised expense rate is equivalent to approximately ₹1,000 per ₹1 lakh invested, assuming the investment value remains constant throughout the year.
In practice, the actual amount varies because the expense ratio is applied to the scheme's assets over time, and the investment value changes.
The important point is that investors generally do not receive a separate bill for TER. The expenses are accounted for within the scheme, and the daily NAV is disclosed after deducting applicable expenses.
How Does Expense Ratio Affect Mutual Fund Returns?
Understanding how expense ratio affects mutual fund returns is important because even a small difference in annual costs can influence long-term investment outcomes.
Consider an illustrative example.
Suppose two otherwise comparable investment options each have ₹1 lakh invested and generate a hypothetical gross annual return of 10% before expenses.
Particulars | Fund A | Fund B |
Initial Investment | ₹1,00,000 | ₹1,00,000 |
Gross Annual Return | 10% | 10% |
Illustrative annual expense ratio | 0.50% | 1.00% |
Approximate return after expenses | 9.50% | 9.00% |
This is a simplified illustration. Actual returns depend on daily expenses, investment performance and other factors.
If the difference in net returns persists over many years, the effect can compound because the money retained after expenses also participates in future investment growth.
However, a lower expense ratio does not automatically make a fund better. A fund with higher expenses may still be suitable if its strategy, risk profile and overall performance justify consideration. Investors should compare costs alongside other relevant factors.
Direct vs Regular Expense Ratio: What Is the Difference?
The direct vs regular expense ratio comparison is one of the most important considerations when selecting a mutual fund plan.
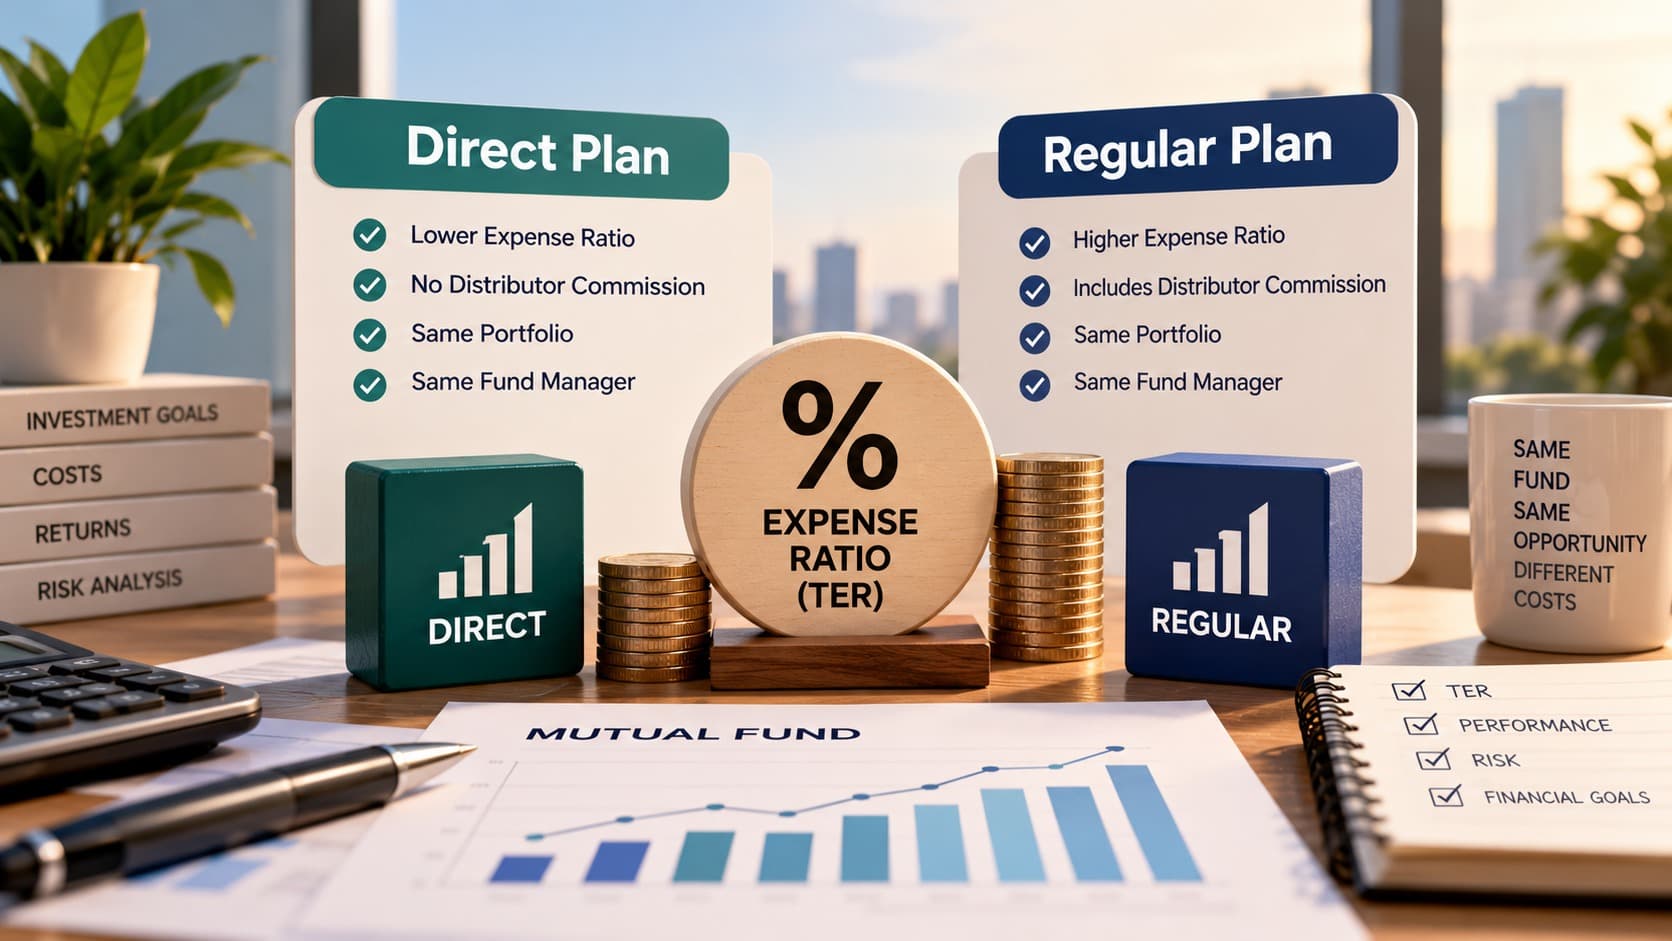
Direct and Regular Plans belong to the same mutual fund scheme. They have the same investment portfolio and fund manager, but their expense ratios and NAVs differ.
A Direct Plan is purchased directly from the asset management company without routing the investment through a distributor. A Regular Plan involves a distributor or intermediary, whose distribution commission is included in the applicable scheme expenses.
Feature | Direct Plan | Regular Plan |
Investment Route | Directly through the AMC or eligible platform | Through a mutual fund distributor |
Expense Ratio | Generally lower | Generally higher |
Distributor Commission | Not charged under the Direct Plan | May be included in scheme expenses |
Portfolio | Same scheme portfolio | Same scheme portfolio |
Fund Manager | Same | Same |
NAV | Separate NAV | Separate NAV |
Investor Support | Investor handles selection and monitoring or uses separate advice | Distributor may assist with fund selection and servicing |
AMFI confirms that Direct and Regular Plans have the same portfolio but different expense ratios, with Direct Plans generally having lower expenses because distribution costs are not included.
Which Plan Should You Choose?
A Direct Plan may suit investors who are comfortable researching funds, selecting investments and monitoring their portfolios independently.
A Regular Plan may suit investors who value distributor support and understand the cost of that service.
The choice should not depend on expense ratio alone. Investors should also consider whether they need help with investment selection, asset allocation, risk assessment and ongoing financial planning.
SEBI Expense Ratio Limits: What Should Investors Know?
The SEBI expense ratio limits define the expenses that mutual fund schemes may charge under the applicable regulatory framework.
The permissible expense limit depends on factors such as the scheme's structure, assets under management and applicable expense categories. Regulatory provisions also specify how certain expenses may be charged.
SEBI requires mutual fund schemes to disclose their expense ratios, allowing investors to compare costs before investing. AMFI also provides information on TER and scheme expense disclosures.
Investors should not rely on a single percentage as a universal expense limit for every mutual fund. Different scheme categories and structures can have different applicable limits, and regulations may change.
Before investing, check the latest TER disclosed by the asset management company or AMFI, along with the applicable scheme documents.
What Are the Hidden Charges in Mutual Funds?
The phrase hidden charges in mutual funds can be misleading because permitted scheme expenses are disclosed through the applicable regulatory and reporting framework. However, investors may overlook certain costs when evaluating an investment.
Here are some charges and costs worth checking:
1. Expense ratio: The recurring cost of operating and managing the scheme.
2. Exit load: A charge that may apply when units are redeemed within a specified period, depending on the scheme's terms.
3. Transaction-related costs: Certain permitted transaction costs can affect scheme expenses or returns, depending on the applicable rules and disclosures.
4. Taxes: Tax may apply to capital gains or other distributions depending on the investment and applicable tax provisions.
5. Distributor-related costs: Distribution commissions can form part of the expenses associated with a Regular Plan.
These costs do not all operate in the same way. For example, TER is accounted for within the scheme's NAV, while an exit load may apply to a particular redemption.
Investors should review the scheme information document, key information memorandum and current expense disclosures to understand the costs relevant to their investment.
How to Compare Low Expense Ratio Mutual Funds
Searching for low expense ratio mutual funds can be a useful starting point, but cost should not be the only selection criterion.
Before choosing a fund, consider the following factors:
Investment objective: Does the fund's objective align with your financial goals?
Fund category: Compare expense ratios among funds with similar investment strategies.
Risk and portfolio: Understand the underlying securities, diversification and potential volatility. Evaluating your investment risk profile can help you assess whether the fund's risk level is appropriate for your investment horizon and financial circumstances.
Performance: Evaluate returns over suitable periods against an appropriate benchmark.
Consistency: Examine whether the fund has followed its stated investment strategy.
Plan type: Compare the Direct and Regular expense ratios for the same scheme.
Other costs: Check exit loads, transaction-related costs and applicable taxes.
A mutual fund portfolio review can help you assess your existing holdings, diversification and the costs associated with your investments.
For passive index funds, expense ratio is especially relevant because the funds generally aim to track an index rather than outperform it through active stock selection. Even then, investors should also consider tracking difference, liquidity and other scheme characteristics.
For actively managed funds, expenses should be evaluated alongside the investment process, risk and performance. A low-cost fund is not necessarily the most suitable choice for every investor.
How to Check a Mutual Fund's Expense Ratio
You can generally find a scheme's expense ratio through the following sources:
AMC website: Check the scheme's latest TER disclosure and factsheet.
AMFI website: Review the published expense ratio information for mutual fund schemes.
Scheme documents: Read the scheme information document and key information memorandum.
Fund comparison platforms: Compare expense ratios for the relevant Direct and Regular Plans, ensuring the information is current.
When comparing two schemes, make sure you are checking the same plan type and a comparable investment category. A Direct Plan should not be compared with a Regular Plan without accounting for the difference in distribution costs.
Investors can also compare the impact of different expense assumptions on their long-term investment projections. Any calculator-based estimate should be treated as illustrative rather than a promise of future returns.
Conclusion
The expense ratio in mutual funds is an important factor because it represents the recurring cost of managing and operating a scheme. These expenses are accounted for within the fund and affect its NAV and returns over time.
The Direct vs Regular comparison highlights why plan selection matters. Direct Plans generally have lower expense ratios because distributor commissions are not charged under those plans, while Regular Plans may provide distributor assistance at an additional cost.
However, choosing a mutual fund should involve more than finding the lowest TER. Investors should assess the fund's objective, portfolio, risk, performance, costs and suitability for their financial goals.
A sensible approach is to understand what you are paying for, compare similar schemes and choose a plan that fits your investment knowledge and support requirements.
Expense ratios should also be considered alongside your long-term financial goals, investment horizon and need for professional support.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial or investment advice. Mutual fund investments are subject to market risks, and returns are not guaranteed. Expense ratios, regulatory limits and tax rules may change. Investors should check the latest scheme disclosures and applicable regulations before investing.
Frequently Asked Questions
What is the expense ratio in mutual funds?
The expense ratio is the annualised percentage of a mutual fund scheme's assets used to cover eligible recurring management and operating expenses. The scheme's NAV accounts for it.
What is the difference between TER and expense ratio?
TER stands for Total Expense Ratio. The terms TER and expense ratio are commonly used to refer to the recurring expenses charged to a mutual fund scheme as a percentage of its assets.
Why is the expense ratio lower in Direct Plans?
Direct Plans do not include distributor commissions, so their expense ratios are generally lower than those of Regular Plans. Both plans have the same scheme portfolio and fund manager.
Do low expense ratio mutual funds always perform better?
No. Lower costs can benefit returns, all else being equal, but performance also depends on the investment strategy, portfolio, market conditions and risk. A low expense ratio alone does not establish that a fund is suitable.