Alpha and Beta in Mutual Funds: Meaning, Ratio and How to Check Them
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
Understand alpha and beta in mutual funds, their formulas, how to interpret negative alpha, and how to evaluate fund performance and risk.
When comparing mutual funds, investors often look at returns to identify which scheme has performed better. However, returns alone do not tell the complete story. A fund may deliver strong returns because the overall market performed well, while another may generate better returns relative to its benchmark.
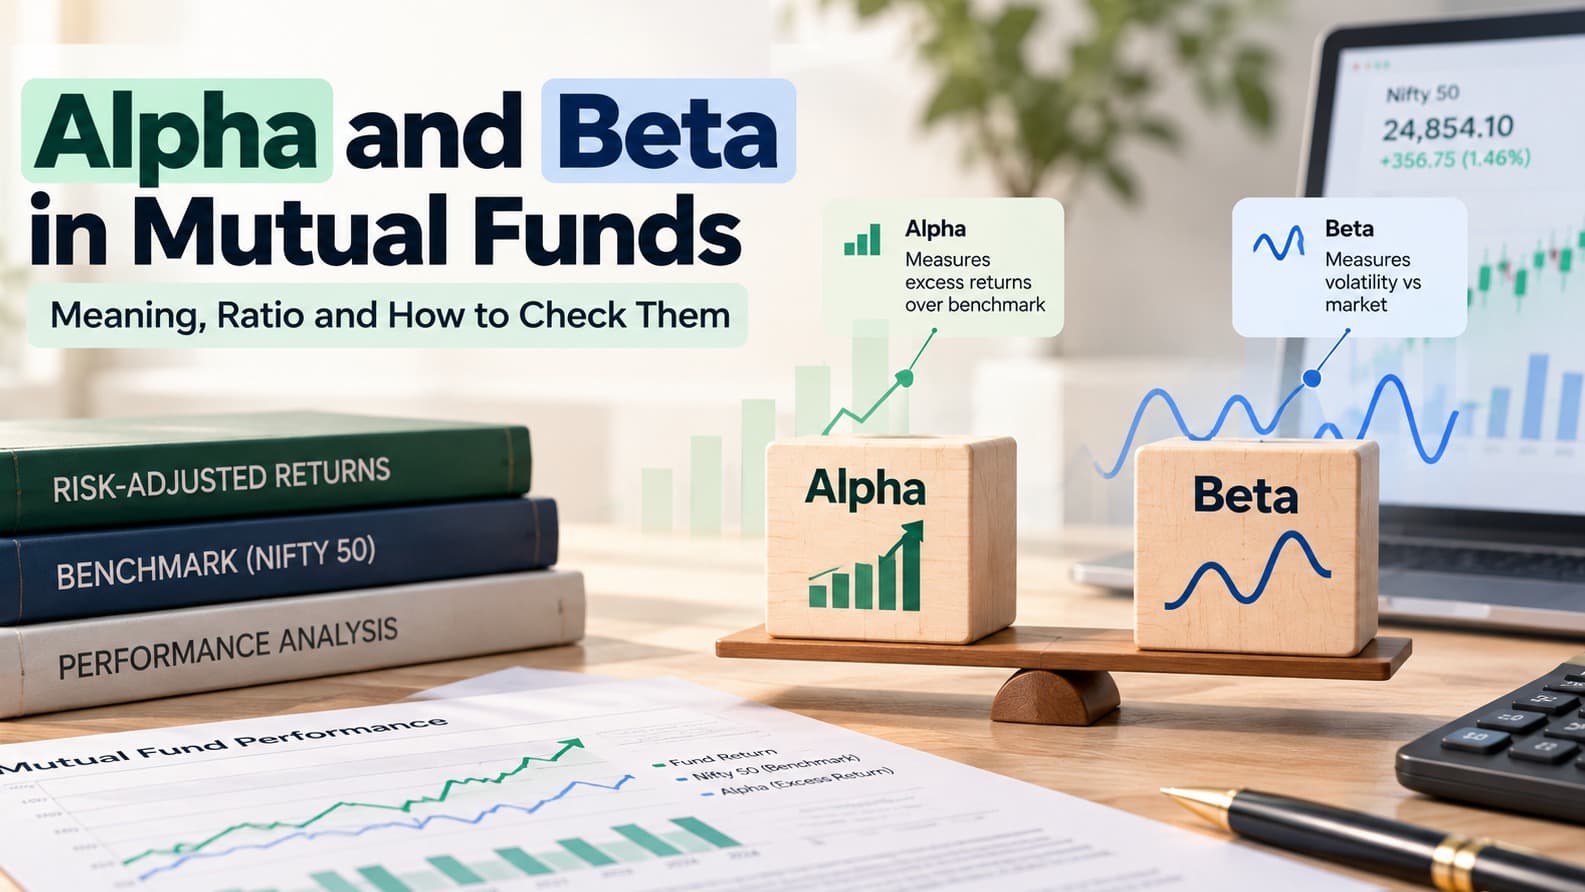
This is where alpha and beta in mutual funds become useful. Alpha helps investors understand a fund's performance relative to its expected or benchmark-adjusted return, while beta indicates how sensitive the fund is to movements in the broader market.
Together, these measures can provide useful insights into a fund's performance and market risk. However, neither metric should be used in isolation when selecting investments.
Understanding what alpha in mutual fund analysis is, how the beta ratio works and how to interpret both measures can help investors make more informed comparisons.
What Is Alpha in Mutual Funds?
Alpha measures a mutual fund's excess return relative to a benchmark or its expected return under a specified model, after accounting for the relevant risk assumptions.
In simple terms, alpha helps answer this question: Did the fund generate more or less return than expected relative to its benchmark or risk exposure?
For example, suppose an equity mutual fund delivers a return of 14% over a year, while its benchmark delivers 11% over the same period.
The fund has outperformed the benchmark by 3 percentage points. This is its simple return difference, although it is not necessarily the fund's formally calculated alpha.
Formal alpha calculations may adjust for market exposure and other model assumptions.
A positive alpha generally indicates that the fund has outperformed its benchmark or expected return under the calculation method used. A negative alpha indicates underperformance relative to that reference.
Alpha can help investors evaluate active fund management, but it does not guarantee that the fund will continue to outperform.
How Is Alpha Calculated?
The basic benchmark-relative return difference can be expressed as:
Simple excess return = Fund Return − Benchmark Return
For example:
Particulars | Annual Returns |
Mutual Fund | 14% |
Benchmark | 11% |
Excess Return | +3% points |
This is a straightforward comparison, not a risk-adjusted alpha calculation.
A commonly used risk-adjusted measure is Jensen's alpha, which estimates the return generated by a fund above the return expected under the Capital Asset Pricing Model (CAPM).
Its formula is:
Jensen's Alpha = Fund Return − [Risk-Free Rate + Beta × (Market Return − Risk-Free Rate)]
Here:
Fund return: The return earned by the mutual fund.
Risk-free rate: The assumed return on a relatively low-risk reference investment.
Beta: The fund's sensitivity to market movements.
Market return: The return generated by the relevant market benchmark.
Example of Jensen's Alpha
Suppose a mutual fund delivers a return of 15%, the risk-free rate is 6%, the market return is 12%, and the fund's beta is 1.1.
Expected return under CAPM:
6% + 1.1 × (12% − 6%) = 12.6%
Jensen's alpha:
15% − 12.6% = +2.4 percentage points
Under these assumptions, the fund has generated a positive Jensen's alpha of 2.4 percentage points.
This illustrates Jensen's alpha meaning: the fund's return exceeded the return predicted by the model for its market exposure.
The result depends on the selected benchmark, period, risk-free rate and calculation methodology. Alpha values calculated using different methods may not be directly comparable.
What Is Beta in Mutual Funds?
Beta measures how sensitive a mutual fund's returns are to movements in its benchmark or market index.
The beta ratio mutual fund investors see is commonly interpreted as follows:
Beta Value | General Interpretation |
Beta = 1 | Historically moved broadly in line with the benchmark |
Beta greater than 1 | Historically more sensitive to benchmark movements |
Beta between 0 and 1 | Historically less sensitive to benchmark movements |
Beta below 0 | Historically moved in the opposite direction on average |
For example, a fund with a beta of 1.2 may be expected to move approximately 12% when its benchmark moves 10%, under a simplified linear interpretation and assuming the historical relationship holds.
This is only an illustration. Beta does not predict the exact return of a fund, and actual results can differ substantially.
A beta of 0.7 suggests lower sensitivity to benchmark movements than a beta of 1, but it does not mean the fund has 30% less total risk. Beta measures market-related sensitivity, not every source of investment risk.
Difference Between Alpha and Beta
The difference between alpha and beta lies in what each metric measures.
Factor | Alpha | Beta |
Primary purpose | Measures relative or risk-adjusted performance | Measures sensitivity to benchmark movements |
Main question | Did the fund outperform its expected return? | How strongly does the fund respond to market movements? |
Interpretation | Positive or negative, depending on the method | Higher, lower or negative relative sensitivity |
Main use | Evaluating performance | Understanding market-related risk |
Limitation | Depends on benchmark and calculation method | Does not capture all investment risks |
Consider two hypothetical funds. Fund A has positive alpha and a beta of 1.2, while Fund B has zero alpha and a beta of 0.8.
Fund A has outperformed its model-based expected return but has greater sensitivity to market movements. Fund B has lower market sensitivity, but its alpha indicates no excess return under the selected model.
Neither is automatically the better investment. The choice depends on the investor's objectives, risk tolerance, investment horizon and the fund's overall characteristics.
High Alpha Low Beta Mutual Funds: Are They Better?
Investors often search for high alpha low beta mutual funds because the combination may appear attractive: stronger relative performance with lower sensitivity to market movements.
A fund with positive alpha and relatively low beta may have delivered better-than-expected performance without moving as strongly as its benchmark. However, this combination should not be treated as proof of superior investment quality.
Several factors matter:
The period over which alpha and beta were calculated.
Whether the selected benchmark suits the fund's investment strategy.
The fund's volatility and downside performance.
The consistency of performance across different market conditions.
The expense ratio and other investment costs.
The fund's portfolio composition and concentration.
Understanding your investment risk profile can help you decide whether a fund's market sensitivity and potential downside align with your risk tolerance.
A fund can also show attractive historical alpha because of a favourable market environment that may not continue. Similarly, a low-beta fund may still face credit risk, liquidity risk, sector concentration or losses during a market downturn.
Investors should evaluate alpha and beta alongside other risk ratios in mutual funds, such as standard deviation, Sharpe ratio and downside-risk measures, where relevant.
How to Check Alpha and Beta of a Mutual Fund
If you want to understand how to check alpha and beta of mutual fund schemes, follow these steps.
1. Visit a reliable fund information source. Check the fund house's factsheet or a reputable mutual fund research platform that publishes these metrics.
2. Identify the benchmark. Ensure the fund is being compared with an appropriate index for its investment category.
3. Check the measurement period. Alpha and beta can vary depending on whether they are calculated over one year, three years or another period.
4. Understand the methodology. Confirm whether alpha is a simple excess return or a risk-adjusted measure such as Jensen's alpha. Check how beta is calculated and which benchmark is used.
5. Compare similar funds. Metrics are more useful when comparing schemes with similar objectives and investment strategies.
6. Review other risk measures. Look at volatility, downside performance, portfolio concentration, expenses and consistency.
A mutual fund portfolio review can help you assess fund overlap, diversification and the overall risk exposure of your existing investments. For a more complete evaluation, Kuberzo mutual fund risk analysis should go beyond a single ratio. Investors need to understand how a fund's performance, risk exposure and investment strategy fit their financial goals.
Interpreting Negative Alpha in Funds
Interpreting negative alpha in funds requires context rather than an immediate decision to sell.
Negative alpha generally indicates that a fund has underperformed its benchmark or model-based expected return over the measurement period.
For example, if a fund's calculated alpha is −2%, it may have underperformed its relevant reference by two percentage points under the method used.
However, one negative reading does not automatically mean the fund is unsuitable. It could reflect a short-term market phase, a strategy temporarily falling out of favour or investment decisions that did not work as expected.
Investors should check whether the underperformance persists across longer periods, whether the benchmark is appropriate, and whether the fund's investment strategy and risk characteristics have changed.
If negative alpha persists over several relevant periods, it may be worth examining the fund more closely. However, the decision should also account for portfolio objectives, costs, consistency and the reasons behind the underperformance.
Conclusion
Alpha and beta provide two different but complementary perspectives on mutual fund performance.
Alpha helps investors assess whether a fund has outperformed its benchmark or model-based expected return, while beta indicates how sensitive the fund has historically been to market movements.
Positive alpha does not guarantee future outperformance, and low beta does not eliminate investment risk. Both measures depend on the benchmark, period and calculation methodology. These metrics should also be considered in the context of your long-term financial goals and the investment horizon available to achieve them.
For a meaningful comparison, investors should evaluate alpha and beta alongside other risk ratios, portfolio characteristics, costs and investment objectives. The aim is not simply to find the fund with the highest alpha or lowest beta, but to understand whether its performance and risk profile suit the investor's needs.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial or investment advice. Mutual fund investments are subject to market risks, and returns are not guaranteed. Investors should read scheme-related documents carefully and consider their financial goals and risk tolerance before investing.
Frequently Asked Questions
What is a good alpha for a mutual fund?
A positive alpha generally indicates outperformance relative to the chosen benchmark or expected return model. However, what counts as meaningful depends on the calculation method, benchmark, measurement period and risk taken.
What is a good beta ratio in a mutual fund?
There is no universally ideal beta. A beta below 1 indicates lower sensitivity to benchmark movements, while a beta above 1 indicates higher sensitivity. The appropriate level depends on the fund's objective and the investor's risk tolerance.
Can a mutual fund have positive alpha and low beta?
Yes. A fund can deliver positive risk-adjusted performance while showing relatively low sensitivity to its benchmark. Investors should verify the calculation period and examine other risk measures before concluding.
Does negative alpha mean I should sell my mutual fund?
Not necessarily. Review the duration and extent of underperformance, the benchmark, the fund's strategy, costs and portfolio suitability before making a decision. A single negative reading is not sufficient on its own.
Where can I check alpha and beta for mutual funds?
You can check fund factsheets and reputable mutual fund research platforms. Confirm the benchmark, measurement period and calculation methodology before comparing figures across schemes.