Tax-Saving Mutual Funds for Senior Citizens: Guide & Top Picks
By Aviral Singh
About the Author
Aviral Singh is an MBA student at IIM Guwahati and a CSIR NET (JRF) qualifier with an M.Sc. from Hansraj College. A former Physics Wallah educator, he creates content on campus life and writes on finance, investments, businesses and education.
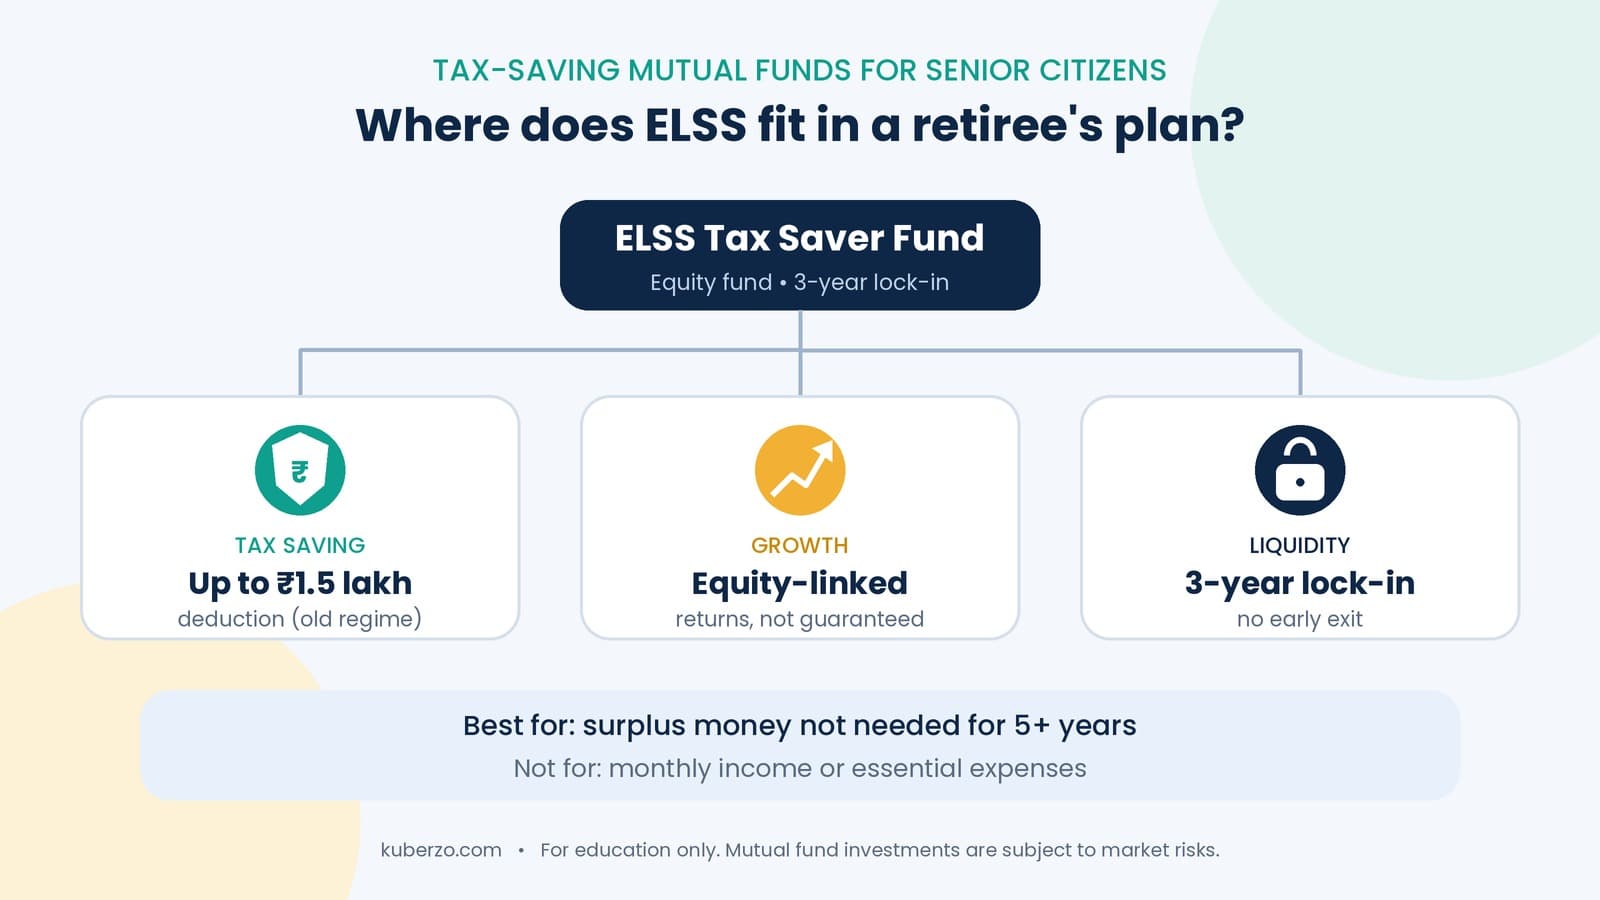
Tax-saving mutual funds (ELSS) for senior citizens: how the deduction works, who should avoid them, and a shortlist of popular ELSS funds including Canara Robeco ELSS Tax Saver.
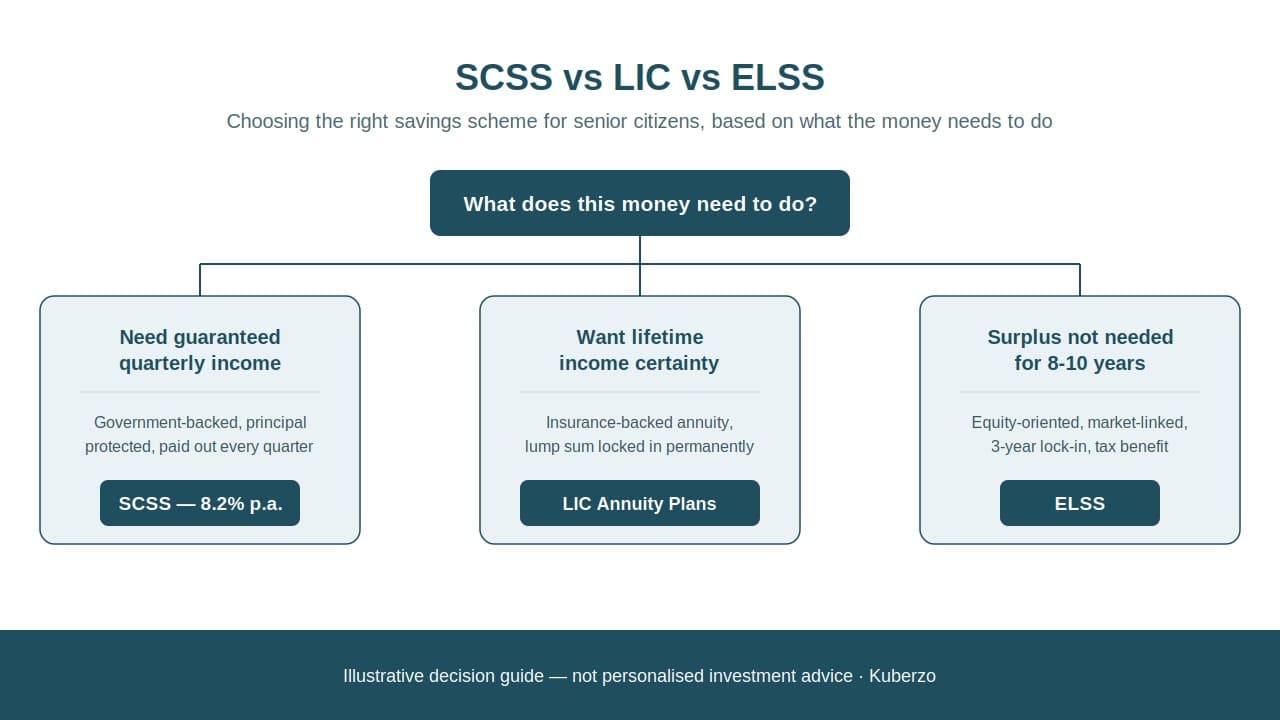
The direct answer: for senior citizens, tax-saving mutual funds (ELSS) are a growth tool, not an income tool. They can cut your taxable income by up to ₹1.5 lakh a year under the old tax regime. But they carry market risk and a 3-year lock-in, so they suit only surplus money you won't need soon.
What are tax-saving mutual funds?
Tax-saving mutual funds, also called ELSS (Equity Linked Savings Schemes), are equity funds that invest at least 80% in equities. Each investment is locked in for 3 years, the shortest lock-in among major tax-saving options. The amount you invest qualifies for a deduction of up to ₹1.5 lakh a year, but only if you file under the old tax regime.
One update to note: under the Income-tax Act, 2025, Section 80C has been renumbered as Section 123 from FY 2026–27. The ₹1.5 lakh limit and ELSS eligibility continue.
How does ELSS tax saving work for seniors?
At investment: the amount invested (up to ₹1.5 lakh, combined with your other 80C/Section 123 investments) is deducted from taxable income. This applies only under the old regime.
At redemption: gains are taxed as long-term capital gains. Gains above ₹1.25 lakh in a financial year are taxed at 12.5%.
Lock-in: every lump sum or SIP instalment is locked for 3 years from its own date. You cannot redeem early.
If you've chosen the new tax regime, ELSS gives no deduction. It then works like any other equity fund, with a lock-in attached.
Tax-saving funds vs other tax-saving options for seniors: the basic comparison
Factor | ELSS | SCSS | 5-Year Tax-Saver FD |
|---|---|---|---|
Nature | Equity mutual fund | Govt-backed savings scheme | Bank deposit |
Returns | Market-linked, not guaranteed | Fixed, set at account opening | Fixed, set at deposit |
Lock-in | 3 years | 5 years (extendable by 3) | 5 years |
Deduction | Up to ₹1.5 lakh (old regime) | Up to ₹1.5 lakh (old regime) | Up to ₹1.5 lakh (old regime) |
Tax on returns | LTCG above ₹1.25 lakh at 12.5% | Interest fully taxable | Interest fully taxable |
Best for | Long-term growth | Regular income with safety | Safe, fixed returns |
This table is a starting point for comparison, not a personalised recommendation.
Are tax-saving mutual funds suitable for senior citizens?
Only for a portion of the corpus. ELSS funds carry a "Very High" risk rating, and their value can fall for long stretches. A senior who relies on this money for medical bills or monthly expenses should not put it here. A surplus not needed for 5–8 years, such as a legacy or a grandchild's education fund, is a more reasonable fit.
If you're deciding between safety and growth for the rest of your corpus, Kuberzo's Fixed Deposit vs Mutual Fund guide" is a useful companion read.
Top tax-saving mutual funds: popular ELSS funds to research
Rankings change with every NAV update, and different websites show different return figures. So this is an illustrative shortlist of widely followed ELSS funds, not a ranked recommendation. Check the latest factsheet before you decide.
# | Fund | Why it's on the watch list |
|---|---|---|
1 | Canara Robeco ELSS Tax Saver Fund | Long-running fund, roughly ₹8,700 crore AUM, large-cap-leaning style |
2 | SBI ELSS Tax Saver Fund | One of the largest in the category by AUM |
3 | HDFC ELSS Tax Saver Fund | Large AUM, widely held by investors |
4 | DSP ELSS Tax Saver Fund | Consistent presence in category rankings |
5 | Motilal Oswal ELSS Tax Saver Fund | Higher-conviction, concentrated style |
6 | Nippon India ELSS Tax Saver Fund | Large, established fund house |
7 | HSBC ELSS Tax Saver Fund | Frequently included in category comparisons |
8 | Bank of India ELSS Tax Saver Fund | Often cited for long-term returns |
9 | Quant ELSS Tax Saver Fund | Aggressive, high-churn style |
10 | Axis ELSS Tax Saver Fund | Large and widely held ELSS option |
Mentioned for education only. This is not a buy recommendation.
What is the Canara Robeco ELSS Tax Saver Fund?
Canara Robeco ELSS Tax Saver Fund (formerly Canara Robeco Equity Tax Saver) is one of the long-running funds in the category. It has historically leaned toward large caps. Large-cap tilt can mean somewhat smoother performance than small-cap-heavy ELSS funds, but it does not remove market risk. Its returns trail some peers over recent periods, so compare it on 5-year and 10-year numbers and on expense ratio (Direct vs Regular), not on a single year.
To understand how the equity portion is split across market caps, read Kuberzo's Large Cap vs Mid Cap vs Small Cap guide
How should a senior citizen choose an ELSS fund?
Check the equity style. Large-cap-leaning funds are generally less volatile than mid/small-cap-heavy ones.
Look at 5- and 10-year returns, not 1-year. One strong year says little.
Compare expense ratios. Direct plans cost less than Regular plans.
Check the fund house and fund manager track record.
SIP or lump sum in ELSS?
An ELSS SIP spreads your buying across months, which reduces the risk of investing everything at a market peak. But each instalment has its own 3-year lock-in, so the last instalments are locked for longer. If you're unsure which approach fits, Kuberzo's SIP vs Lump Sum guide walks through the trade-offs.
A practical way to use ELSS
Example 1: Surplus beyond the income plan
A retiree whose monthly needs are covered by pension, SCSS and an annuity has ₹2 lakh of surplus. Putting part of it in ELSS may make sense, since it won't be needed for years.
Example 2: Still earning, still in the old regime
A 62-year-old with consulting income who files under the old regime and hasn't used the full ₹1.5 lakh limit can use ELSS to fill the gap and cut taxable income.
Example 3: Health and income needs first
A retiree with unpredictable medical costs should prioritise health cover and liquid or fixed-income options. ELSS is a poor fit for money that may be needed in an emergency. Kuberzo's Goal Based Planner can help you size each bucket.
Common mistakes seniors make with tax-saving funds
Mistake 1: Investing in ELSS while filing under the new tax regime. You lose the deduction but keep the lock-in.
Mistake 2: Treating ELSS as a safe fixed-income product. It is an equity fund and can fall in value.
Mistake 3: Choosing a fund on last year's returns alone. Check 5- and 10-year performance, cost and style.
Mistake 4: Locking up money needed for medical or living expenses. There is no early exit for 3 years.
Mistake 5: Counting ELSS against the ₹1.5 lakh limit separately. The limit is combined across all eligible investments, including SCSS, PPF, NPS (own contribution) and tax-saver FDs.
So, which should a senior citizen choose?
There's no single winner. SCSS and fixed deposits suit guaranteed, low-risk needs. ELSS suits only the part of your money that can stay invested for 5+ years and handle market swings. Many retirees do best with a small ELSS allocation alongside safer instruments, rather than as the main holding.
Financial disclaimer
This article is for general education and does not constitute personal investment or tax advice. ELSS returns are market-linked and not guaranteed. Fund names are mentioned for illustration and are not recommendations. Tax rules, including section numbering and regime-wise benefits, can change and vary by individual circumstances. Mutual fund investments are subject to market risks; read all scheme-related documents carefully. Consult a qualified financial or tax professional before investing.
Frequently Asked Questions
Which are the best tax saving mutual funds for senior citizens?
There is no single best fund. Popular ELSS options include Canara Robeco, SBI, HDFC, DSP and Motilal Oswal ELSS Tax Saver funds. The right choice depends on your risk comfort, horizon and costs.
Is ELSS safe for senior citizens?
Not in the way SCSS or an FD is. ELSS is an equity fund with market risk and no guaranteed returns, so it suits only surplus money.
What is the lock-in period of ELSS?
3 years from the date of each investment. Each SIP instalment has its own lock-in.
How much tax can I save with ELSS?
You can claim a deduction on up to ₹1.5 lakh a year under the old tax regime, combined with other eligible investments. The tax actually saved depends on your slab.
Do I get ELSS tax benefits under the new tax regime?
No. The deduction applies only under the old regime.