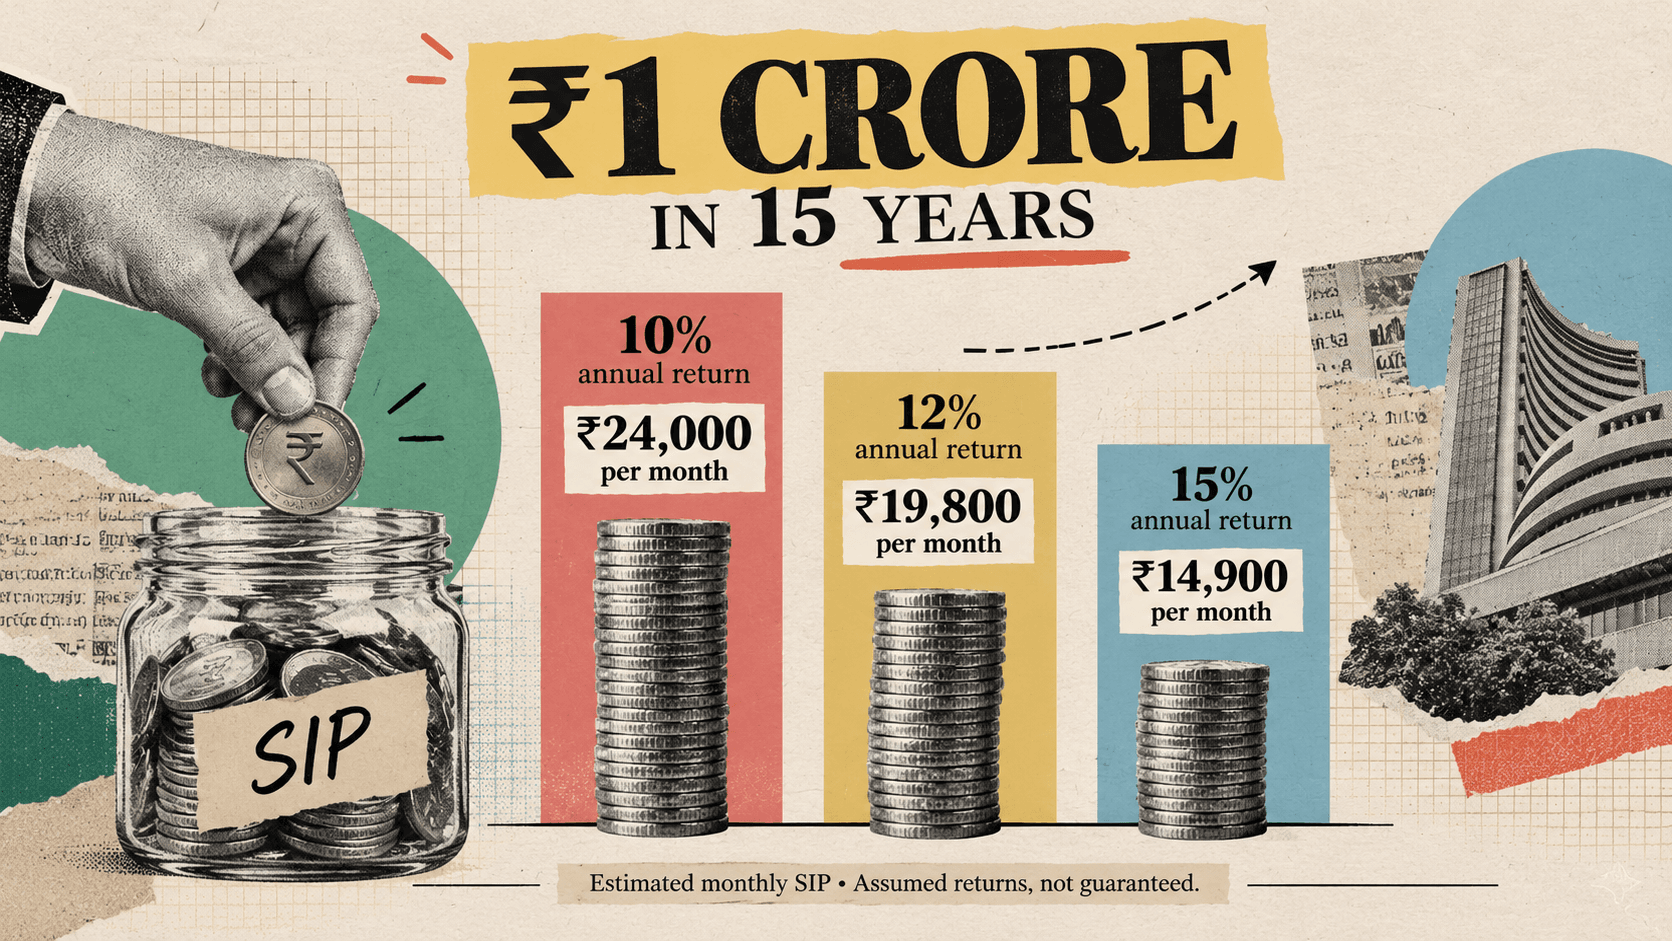
SIP for Women: Taking Charge of Your Financial Independence
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
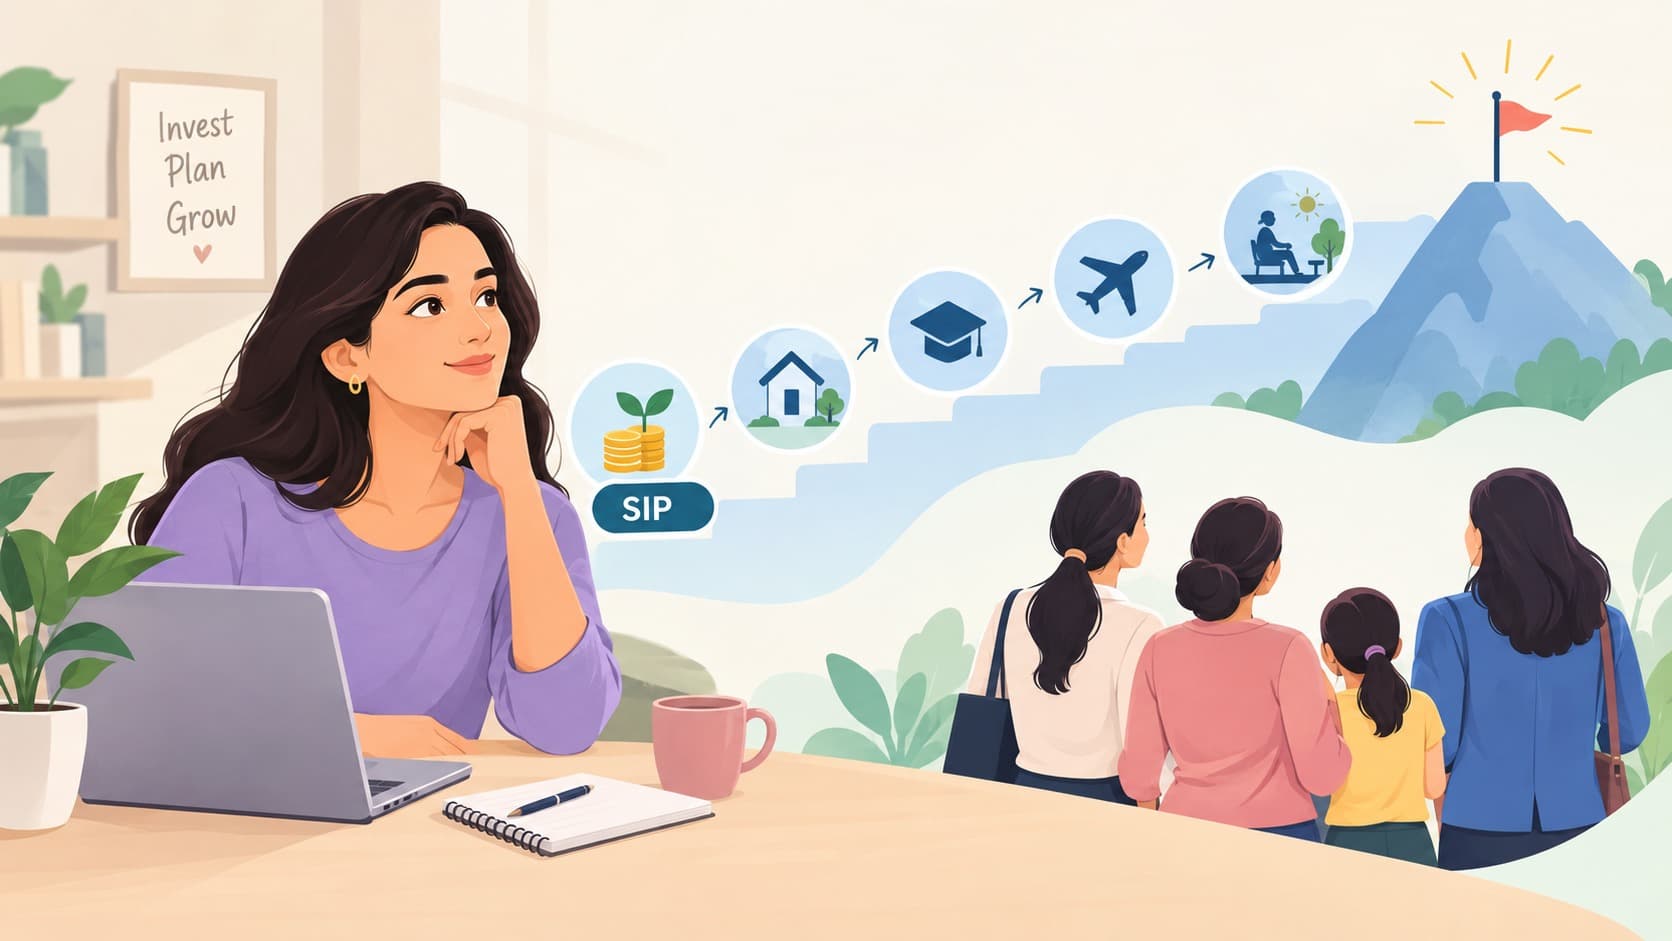
Explore how SIPs can help women build financial independence, plan life goals, and develop disciplined savings habits, whether working or managing a household.
SIP for Women: Taking Charge of Your Financial Independence
Financial independence is not just about earning a salary. It is about having control over your money, making informed financial decisions, and building resources for your future. Whether you are a working professional, a homemaker, a single mother, or someone returning to work after a career break, planning your finances can help you move towards greater financial security.
A Systematic Investment Plan (SIP) offers one way to invest regularly in mutual funds. By investing an affordable amount at regular intervals, women can work towards personal goals without needing a large initial investment. However, choosing the right investment requires understanding your goals, time horizon, and tolerance for risk.
Why Is Financial Planning Important for Women?
Women may experience different financial circumstances throughout their lives, including career breaks, caregiving responsibilities, changing household incomes, or longer periods of retirement. Having investments and savings in their own name can provide greater financial flexibility.
Financial planning for women starts with understanding income, expenses, savings, insurance, and future commitments. It also means having access to information about household finances, loans, investments, and important financial documents.
You do not need a high income to begin planning. Even a modest, consistent saving habit can help establish financial discipline. The amount should be affordable and should not come at the cost of essential expenses or emergency savings.
How Can an SIP Support Financial Independence?
An SIP allows you to invest a fixed amount in a mutual fund at regular intervals, commonly monthly. Instead of waiting until you have accumulated a large sum, you can begin with an amount that fits your budget.
SIPs can help women build a structured approach to investing through three key benefits:
Regular investing: A fixed schedule encourages consistency instead of relying on occasional surplus money.
Long-term wealth creation potential: Equity mutual funds may offer growth potential over long periods, although returns are market-linked and not guaranteed.
Goal-based planning: Separate investments can be planned around goals such as education, retirement, starting a business, or building personal savings.
Remember that an SIP is a method of investing, not a guarantee of profit. The risk depends on the mutual fund scheme selected.
SIP for Housewives: Starting Without a Salary
Homemakers contribute significantly to household finances through budgeting, managing expenses, and coordinating family needs. However, they may have limited personal income or direct access to investments.
A SIP for housewives can begin with money allocated from household savings, personal income, rental income, or another legitimate source, depending on the individual's circumstances. The first step is to agree on a sustainable amount and maintain clear records of investments and ownership.
For example, a homemaker who can set aside ₹1,000 each month could explore suitable mutual fund options after establishing an emergency reserve. The goal should be to develop a manageable habit rather than chase high returns.
It is also important to understand whose name the investment is held in, who controls the account, and the applicable tax treatment. Financial independence involves both building assets and understanding how to access and manage them.
Goal-Based SIP for Women: Invest With a Purpose
A goal-based SIP connects each investment to a specific financial objective. This makes it easier to decide how much to invest, which type of fund to consider, and when the money will be needed.
Common goals include:
Emergency savings: Build accessible reserves for unexpected expenses before taking significant investment risks.
Education or skill development: Set aside money for courses, certifications, or further education.
Starting a business: Plan for future equipment, working capital, or initial operating expenses.
Retirement: Build long-term resources that may supplement other retirement income.
Personal goals: Save towards travel, a home, or other meaningful milestones.
The investment horizon matters. Equity mutual funds may be appropriate for some long-term goals, depending on risk tolerance. For money needed soon, lower-volatility options may be more suitable, although they also carry risks. Review your investments as the goal approaches.
Best Savings for Working Women: What Should You Prioritise?
Before selecting mutual funds, create a financial foundation. A practical order of priorities is:
1. Track your money. Understand your monthly income, essential expenses, debts, and available surplus.
2. Build an emergency fund. Keep money accessible for unexpected expenses. The required amount depends on your household responsibilities, income stability, and existing support.
3. Review insurance needs. Health insurance and, where appropriate, life insurance can help protect against financial shocks.
4. Start investing according to your goals. Choose between suitable savings products and mutual fund categories based on the time horizon and risk involved.
5. Review regularly. Increase contributions when your income grows, if your budget allows, and reassess your plan after major life changes.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
SIP Strategy for Single Mothers
For single mothers, financial planning may involve balancing childcare costs, household expenses, education, and retirement with a single primary income. Flexibility is therefore essential.
Begin by identifying non-negotiable expenses and establishing emergency savings. Avoid committing so much to SIPs that you may need to redeem investments during a financial emergency.
Consider separating your child's education goal from your own retirement goal. These objectives may have different timelines and risk requirements. Review nominee details and keep important financial records organised so that your family can navigate unexpected situations more easily.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
Common Mistakes to Avoid
Women beginning their investment journey should watch out for several common mistakes:
Investing in a fund only because someone recommended it.
Assuming mutual funds or SIPs guarantee returns.
Ignoring emergency savings while investing for long-term goals.
Choosing investments without understanding their risks, fees, or withdrawal conditions.
Depending entirely on another person to manage financial decisions without understanding the investments.
A mutual fund investment guide for women should encourage informed choices rather than promise quick wealth. Learn the basics, compare suitable options, and seek qualified financial advice when necessary.
Contact us for a more personalised guidance.
Key Takeaway
Financial independence begins with awareness, control, and consistent decisions. An SIP can be a useful tool for women who want to invest towards long-term goals, but it should form part of a broader financial plan that includes emergency savings, appropriate insurance, and manageable expenses.
The Kuberzo women investment plan approach should centre on individual circumstances rather than a one-size-fits-all investment amount. Start with a clear goal, invest only what you can afford, understand the risks, and review your progress regularly.
The objective is not simply to invest more. It is to build financial confidence and greater control over your future.
Frequently Asked Questions
Is an SIP suitable for women who do not earn a salary?
It can be, if there is a legitimate, sustainable source of money to invest and the household's essential needs are covered.
How much should a woman invest in an SIP each month?
There is no universal amount. Start with an affordable contribution based on your income, expenses, emergency savings, and financial goals.
Are SIP returns guaranteed?
No. SIPs in mutual funds are subject to market risks, and returns depend on the underlying scheme.
Which mutual fund is best for women's financial independence?
There is no single best fund for everyone. The choice depends on the investment horizon, risk tolerance, goal, and overall financial situation.
Can single mothers use SIPs to plan for their children's education?
Yes. They can consider goal-based investing, while keeping emergency savings and their own retirement needs in view.