Robo-Advisory vs Human Wealth Advisor: Which Management Model Fits Your Net Worth?
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
Compare robo-advisors vs human wealth advisors on fees, personalisation, portfolio management and suitability to choose the right approach for your wealth.
Introduction
Managing money today involves more than choosing investments. Investors also need to plan financial goals, manage risk, review portfolios and make decisions during market fluctuations. This raises an important question: should you rely on technology or work with a human wealth advisor?
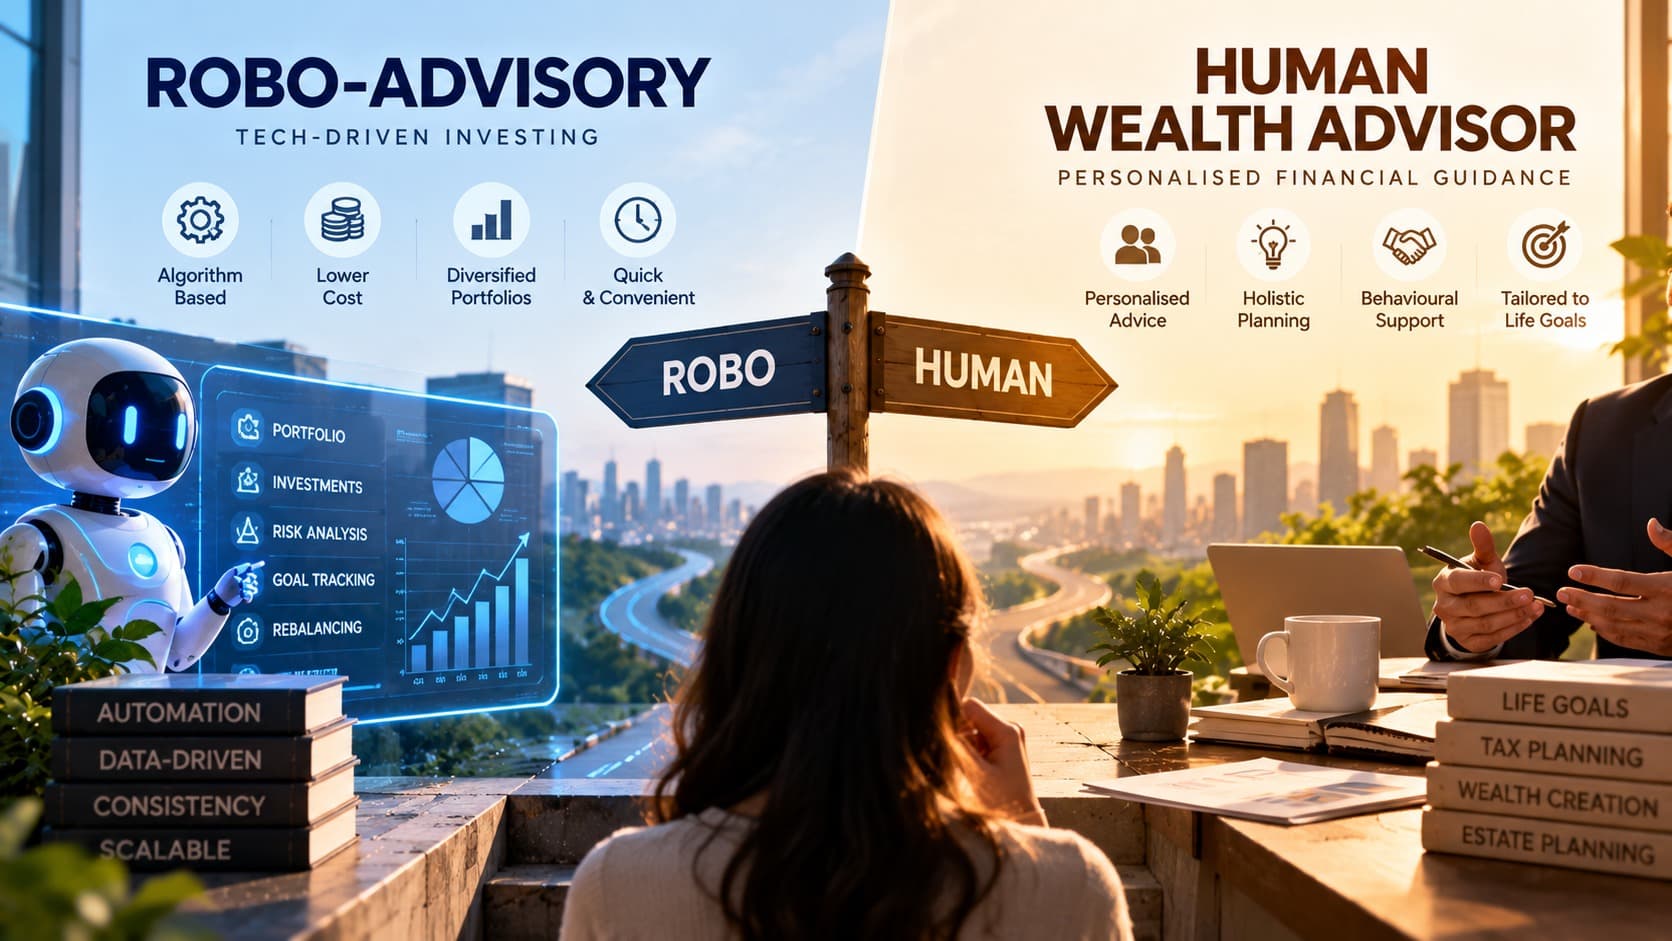
The comparison of robo-advisor vs human advisor comes down to how you prefer to manage your money. Robo-advisors use algorithms to automate investment processes, while human advisors offer personalised guidance based on an investor’s broader financial circumstances.
Neither model is automatically better for everyone. Your income, investable assets, financial responsibilities, investment knowledge and need for professional guidance all influence the right choice.
What Is Robo-Advisory?
Robo-advisory is a technology-driven investment service that uses algorithms and investor information to recommend or manage an investment portfolio. Investors typically provide details about their financial goals, investment horizon and risk tolerance through an online questionnaire.
Based on these inputs, a robo-advisor investment platform may suggest an asset allocation, recommend suitable investment products and monitor the portfolio. Depending on the service, it may also automate portfolio rebalancing.
An automated investment advisor can make investing more accessible to people who prefer a digital experience and do not require extensive personal interaction.
However, the service offered by each platform can differ. Some provide investment recommendations, while others offer portfolio execution and ongoing management. Investors should understand exactly what a platform provides before signing up.
What Does a Human Wealth Advisor Do?
A human wealth advisor provides investment guidance through discussions about an investor’s financial situation, goals and responsibilities.
Unlike a purely automated service, a human advisor can consider factors beyond the investment portfolio, such as insurance needs, retirement planning, tax considerations, property purchases and financial responsibilities towards dependants.
The comparison of a human financial advisor vs a robo advisor is particularly relevant when financial decisions become more interconnected. For example, someone planning retirement while supporting dependants may need to balance several goals, cash-flow requirements and investment risks.
A human advisor can also help investors understand market volatility and avoid making impulsive decisions. The quality of advice, however, depends on the advisor’s expertise, service model, fees and the investor-advisor relationship.
Robo-Advisor vs Financial Advisor: Key Differences
The following comparison highlights the main differences between the two models.
Feature | Robo-Advisor | Human Wealth Advisor |
|---|---|---|
Management style | Algorithm-driven | Personalised, relationship-driven |
Cost | Often lower, depending on the service | Varies by advisor and service |
Accessibility | Usually digital and convenient | Depends on availability and meeting format |
Personalisation | Based on inputs and platform rules | Can consider broader financial circumstances |
Portfolio monitoring | May be automated | May involve manual or technology-supported reviews |
Emotional support | Limited or automated | Direct human guidance |
Financial planning | Depends on platform features | May include broader financial planning |
Best suited for | Investors with straightforward needs | Investors seeking more personalised guidance |
The distinction is not absolute. Some human advisors use advanced portfolio software, while some digital platforms provide access to human support.
Robo-Advisory vs Wealth Management: What Does Your Net Worth Have to Do With It?
When evaluating robo-advisory vs wealth management, net worth can be a useful starting point, but it should not be the only deciding factor.
An investor with a modest portfolio, regular income and straightforward goals may find a digital investment service sufficient. A lower-cost structure can be useful when the investor needs basic portfolio allocation and monitoring rather than extensive financial planning.
As wealth grows, financial decisions may become more complex. An investor might have multiple investments, property, business income, retirement requirements, tax considerations and estate-planning needs. A human wealth advisor may be better placed to coordinate these different areas, depending on their expertise and the scope of their service.
However, a large portfolio does not automatically require a human advisor, just as a smaller portfolio does not automatically rule one out. The right model depends on the complexity of your finances and the level of guidance you need.
Robo-Advisory Fees vs Financial Advisor: Which Costs Less?
Cost is an important factor in the robo-advisory fees vs financial advisor comparison.
Robo-advisory services often use technology to automate parts of the investment process, which may allow them to offer lower fees. However, charges vary by provider, investment product and service level. Investors should check for platform fees, advisory charges and underlying fund expenses.
Human advisors may charge a fixed fee, a percentage of assets under advice or management, or another disclosed fee structure, depending on their business model and applicable regulations. Additional services may also affect the overall cost.
When comparing wealth management advisor fees, look beyond the headline amount. Consider what you receive in return, including portfolio reviews, financial planning, tax coordination and ongoing support.
A lower fee is useful only when the service meets your needs. Equally, a higher fee does not automatically mean better advice.
Portfolio Rebalancing Advisor vs Algorithm: How Are Investments Managed?
Portfolio rebalancing helps bring an investment portfolio back towards its intended asset allocation when market movements cause it to drift.
In the portfolio rebalancing advisor vs algorithm comparison, an algorithm can monitor allocations and trigger rebalancing according to predefined rules. This can reduce manual effort and help maintain consistency.
A human advisor can also review portfolio allocations but may consider additional circumstances before recommending changes. For example, a planned house purchase, a change in income or a shorter investment horizon could affect how much risk an investor should take.
Neither approach removes market risk. Investors should understand the rebalancing method, potential transaction costs, tax implications and conditions under which changes are made.
Is Hybrid Wealth Management Advisory a Better Middle Ground?
Hybrid wealth management advisory combines digital investment tools with access to human guidance. This approach can offer automated portfolio monitoring and reporting alongside professional support for more complex decisions.
For example, an investor might use technology for routine portfolio tracking but consult an advisor when planning retirement, reviewing asset allocation or reassessing financial goals after a major life change.
A hybrid model can be useful for investors who value convenience but do not want to make every financial decision independently. Before choosing one, check whether human advice is included in the fee, when consultations are available and whether the advisor provides comprehensive financial planning or only investment-related support.
How Should You Choose the Right Model?
Before choosing between an automated service and a human advisor, consider these questions:
Are your financial needs straightforward? A digital service may be sufficient for basic investment management.
How comfortable are you with investing? If you need explanations and ongoing guidance, human support may be valuable.
How complex are your finances? Multiple financial goals, business interests or retirement requirements may call for broader planning.
What services are included? Compare portfolio management, reviews, rebalancing and financial planning.
What is the total cost? Review all advisory fees and investment-related expenses.
How much personal interaction do you need? Consider whether you prefer self-service tools, direct advice or a combination.
Ultimately, the right choice should fit your financial circumstances, not just your current portfolio value.
Conclusion
The robo advisor vs financial advisor decision is about choosing the right level of technology, personalisation and support for your financial needs.
Robo-advisory can offer convenience, systematic portfolio management and potentially lower costs for investors with straightforward requirements. A human wealth advisor may provide more personalised guidance when financial decisions involve several goals, responsibilities and changing circumstances.
For investors who want both, a hybrid model may offer a practical middle ground.
Rather than choosing solely based on net worth, evaluate the complexity of your finances, the services you need, the total cost and your comfort with managing investments. The most suitable management model is one that supports your financial goals and helps you make informed, consistent decisions over time.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial or investment advice. Investment products carry risks, and returns are not guaranteed. Review the terms, services, fees and regulatory status of any advisory provider before making a decision.
Frequently Asked Questions
Is a robo-advisor better than a human financial advisor?
Neither is universally better. Robo-advisors may suit investors who prefer automated, lower-cost investment management, while human advisors may be useful when financial needs are more complex or personalised guidance is important.
Are robo-advisors cheaper than wealth advisors?
Robo-advisors often have lower fees, but costs vary by provider and service. Compare platform charges, advisory fees and underlying investment expenses before deciding.
Can a robo-advisor manage a large investment portfolio?
It may be able to, depending on the platform’s investment limits, available services and features. A large portfolio with complex financial needs may also benefit from human advice.