Corporate Fixed Deposits vs Bank Fixed Deposits: Evaluating Higher Yields vs Credit Risk
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
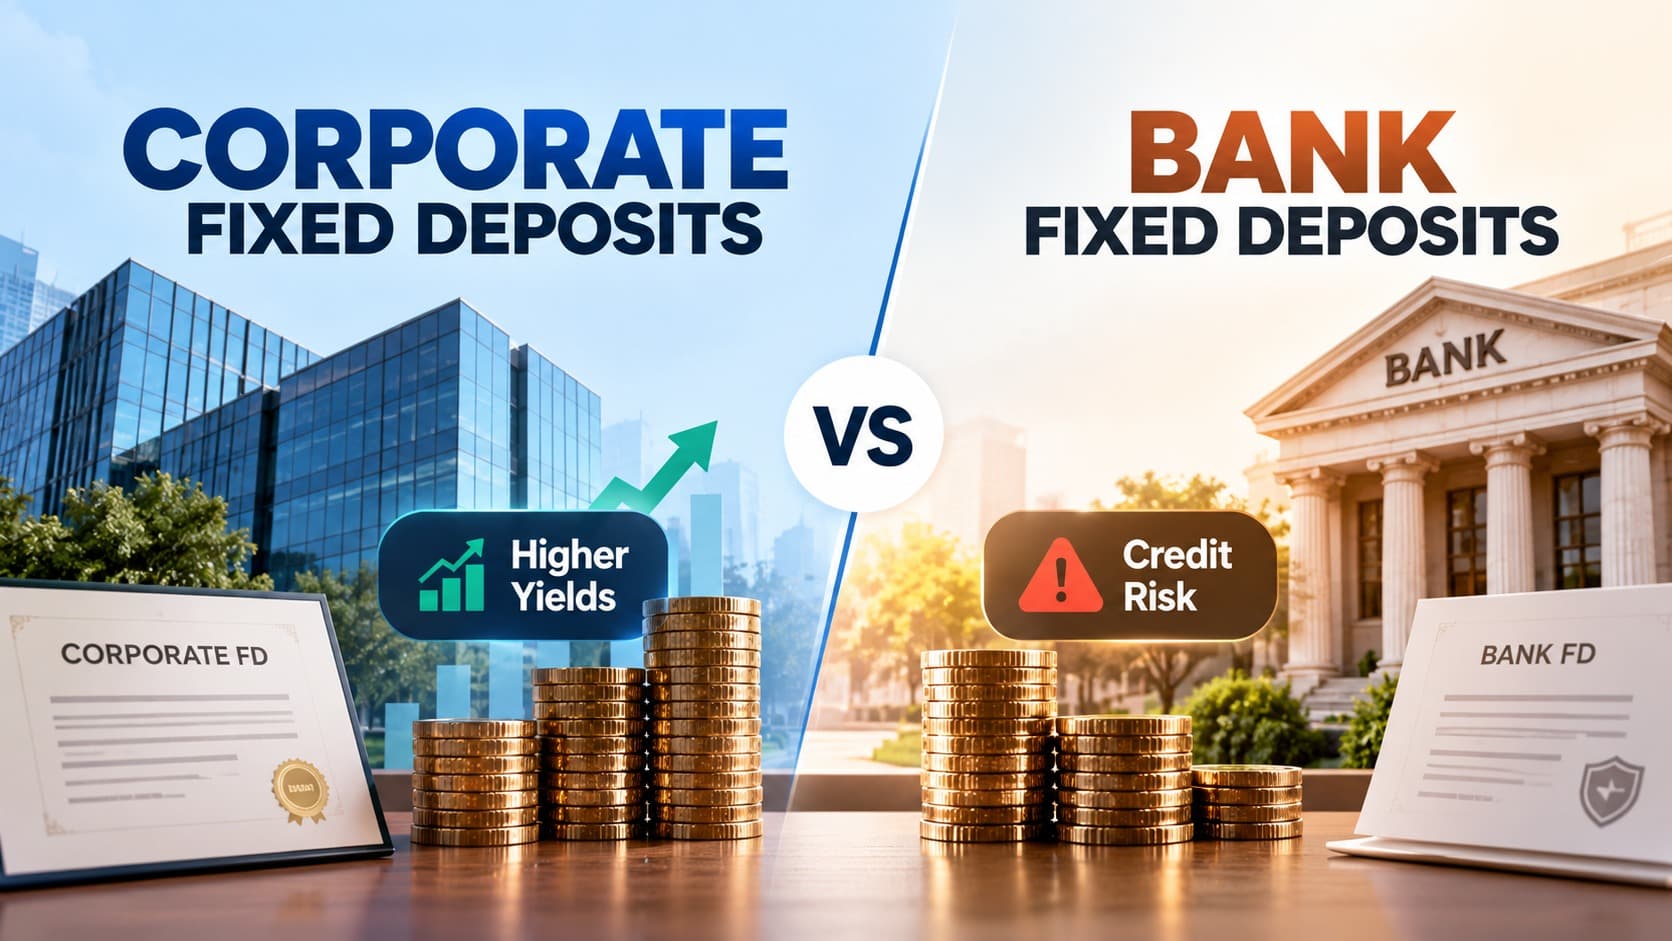
Compare corporate FD vs bank FD on interest rates, returns, DICGC insurance, credit ratings and default risk to understand which fixed deposit may suit you.
Fixed deposits are often considered one of the simpler ways to earn relatively predictable interest on surplus money. But not all fixed deposits carry the same level of risk. While bank fixed deposits are familiar to most investors, corporate fixed deposits can sometimes offer higher interest rates, making them attractive to investors looking for better returns from fixed-income products.
This creates an important corporate FD vs bank FD comparison. At first glance, the decision may seem straightforward: if a company is offering a higher interest rate than a bank, why not choose the higher-yielding option? The answer lies in the relationship between return and credit risk.
A bank FD represents a deposit placed with a bank, while a corporate FD is essentially money deposited with an eligible company under the applicable regulatory framework. In a corporate FD, the investor is taking credit exposure to the company. If the company's financial position deteriorates, its ability to repay the principal and interest can come under pressure.
Bank deposits, on the other hand, benefit from the deposit-insurance framework administered by the Deposit Insurance and Credit Guarantee Corporation (DICGC), subject to the applicable conditions and limits. DICGC currently provides insurance of up to ₹5 lakh per depositor per bank, covering principal and accrued interest.
This difference is critical. A higher interest rate is not "free" additional return. It can partly compensate investors for taking greater credit risk.
Therefore, when comparing company FD vs bank FD, investors should look beyond the advertised interest rate. Credit rating, financial strength, deposit insurance, tenure, premature withdrawal rules, liquidity and the purpose of the investment all deserve attention.
What Is The Difference Between Corporate FD And Bank FD?
The fundamental difference is who owes the money to the investor.
With a bank FD, the investor places money with a bank for a specified period at an agreed interest rate.
With a corporate FD, the investor places money with a company under the terms of its deposit programme. The company uses those funds as part of its financing.
The risk therefore depends significantly on the financial health and repayment capacity of the issuer.
Factor | Bank FD | Corporate FD |
Issuer | Bank | Company |
Return | Generally predetermined | Generally predetermined |
Credit Risk | Bank-Specific | Company Specific |
DICGC Insurance | Applicable to eligible bank deposits | Not Applicable |
Potential interest rate | Usually lower than some corporate FDs | Can be higher |
Key Consideration | Bank strength + insurance | Company strength + credit rating |
Liquidity | Depends on the bank's premature withdrawal terms | Depends on issuer's terms and applicable rules |
DICGC states that eligible deposits such as savings, current, fixed and recurring deposits with insured banks are covered, subject to the insurance ceiling and conditions. Deposits from NBFCs are specifically excluded from DICGC insurance.
Corporate Fixed Deposit Risk Vs Bank FD: Why Does The Difference Matter?
The most important factor in the corporate fixed deposit risk vs bank FD comparison is credit risk.
Credit risk is the possibility that the borrower may not be able to repay principal or interest when due. SEBI's investor education material notes that higher credit risk generally requires a higher yield to compensate investors for taking that additional risk.
This explains why some corporate FDs may advertise higher rates than bank FDs.
Consider an illustrative example:
Suppose:
Bank FD: 7% per annum
Corporate FD: 9% per annum
A ₹1 lakh investment at 7% would earn approximately ₹7,000 in annual interest before tax, while the 9% corporate FD would earn approximately ₹9,000, assuming simple annual interest for illustration.
The additional ₹2,000 is attractive. But the investor is accepting greater issuer-specific credit exposure in exchange for that higher rate.
The comparison should therefore be:
Higher yield + higher credit risk vs lower yield + greater deposit protection
rather than simply:
9% is better than 7%.
DICGC Insurance Corporate FD: Is Your Money Protected?
The question of DICGC insurance for corporate FD is particularly important.
DICGC deposit insurance applies to eligible deposits with insured banks. The current maximum insurance cover is ₹5 lakh per depositor per bank, including principal and accrued interest, subject to the applicable conditions. Deposits held in the same right and capacity across branches of the same bank are aggregated for determining the insurance limit.
Corporate deposits do not receive this DICGC protection.
This means investors should not assume that because a corporate FD resembles a bank FD in structure, it receives the same deposit insurance.
This distinction becomes especially important when investing a substantial amount. An investor considering a corporate FD should assess whether the additional interest justifies taking the issuer's credit risk.
Highest Interest Corporate FDs: Should You Chase The Highest Rate?
Searching for the highest interest corporate FDs can be tempting, particularly when interest rates are attractive.
However, the highest rate is not necessarily the best option.
A significantly higher interest rate can indicate that the issuer needs to offer additional compensation to attract deposits. Investors should therefore examine:
Credit rating
Financial statements
Profitability and cash flows
Existing debt
Repayment history
Deposit programme terms
Tenure
Premature withdrawal provisions
Whether the issuer is a bank, NBFC or other eligible company
The objective should be to find an appropriate balance between yield and credit quality, rather than simply maximising the headline interest rate.
Credit Rating AAA Corporate FDs: Are They Risk-Free?
The phrase AAA corporate FDs can create a false sense of security.
A high credit rating indicates a stronger assessment of the issuer's ability to meet its financial obligations. SEBI educational material explains that credit ratings range from higher-safety ratings such as AAA to lower ratings, with credit risk generally increasing as the rating declines.
However, a credit rating is not a guarantee of repayment.
Ratings can also change if the issuer's financial position deteriorates. Therefore, investors should not treat an AAA rating as equivalent to a government guarantee or DICGC insurance.
A rating should be one part of the due-diligence process, not the only factor. Investors should also assess their investment risk profile before deciding how much exposure to take to corporate deposits.
Corporate FD Interest Rates Vs Bank FD: Why Are Corporate Rates Higher?
The corporate FD interest rates vs bank FD difference can largely be explained by risk and funding requirements.
Companies may offer higher rates to attract deposits because they are competing for funds with banks and other investment opportunities.
From the investor's perspective, the additional interest can be viewed as compensation for taking issuer-specific credit risk.
However, the rate also depends on factors such as:
Tenure
Market interest rates
Issuer's funding requirements
Credit profile
Deposit mobilisation strategy
Type of company
Therefore, investors should compare the post-tax return and risk, rather than looking at the interest rate in isolation.
Corporate FD Vs Bank FD Returns: How Should You Compare Them?
The corporate FD vs bank FD returns comparison should consider more than the advertised rate.
For example, an investor may see:
Bank FD: 7%
Corporate FD: 9%
But the corporate FD may involve greater credit risk and may not have DICGC insurance.
Taxation also matters. Interest income from both bank and corporate FDs is generally taxable according to the applicable provisions and the investor's tax circumstances.
Therefore, the relevant comparison is:
Post-tax return + credit quality + liquidity + protection
An investor should also check whether the quoted interest rate is cumulative, non-cumulative or dependent on the tenure selected.
Bank FD Vs Company FD Safety: Which Is Safer?
For most investors prioritising capital protection and simplicity, a bank FD with an insured bank offers an important advantage through DICGC protection, subject to the ₹5 lakh limit and applicable conditions.
A corporate FD can potentially offer a higher interest rate, but the investor bears the credit risk of the company.
That does not mean every corporate FD is unsafe or every bank FD is risk-free. Bank-specific risks also exist, and the DICGC protection has a defined limit.
The important distinction is that the protection mechanisms are different.
Investors should therefore avoid making a decision purely based on "bank versus company". The specific institution, amount invested, tenure and risk profile all matter.
Corporate FD Or Bank FD: Which One Should You Choose?
The corporate FD vs bank FD decision ultimately depends on the investor's objective. The corporate FD vs bank FD decision ultimately depends on the investor's objectives, time horizon and financial goals.
A bank FD may be more suitable for someone who:
Prioritises simplicity
Values DICGC deposit insurance within the applicable limit
Has a low tolerance for credit risk
Wants predictable interest income
A corporate FD may be considered by an investor who:
Understands issuer-specific credit risk
Is comfortable with the absence of DICGC protection
Has evaluated the company's financial strength
Is seeking potentially higher interest income
Is willing to accept additional risk for that potential return
For larger investments, diversification can also matter. Concentrating a substantial portion of savings in a single corporate issuer increases exposure to that company's financial health.
What Should You Check Before Investing In A Corporate FD?
Before investing, consider the following checklist:
1. Credit rating: Check the current rating and the rating agency that assigned it.
2. Financial strength: Review the company's financial performance, debt levels and ability to service obligations.
3. Interest rate: Compare the rate with bank FDs and other comparable fixed-income products.
4. Tenure: Ensure the maturity matches your financial goal.
5. Liquidity: Understand premature withdrawal conditions and penalties.
6. Protection: Confirm whether the deposit is covered by DICGC. Corporate deposits generally do not receive DICGC insurance.
7. Concentration: Avoid taking excessive exposure to a single issuer simply for a higher rate.
Reviewing your investment portfolio can help you assess concentration and understand how different investments fit together.
Conclusion
The corporate FD vs bank FD decision is fundamentally a trade-off between potentially higher yields and higher credit risk.
Corporate FDs can offer attractive interest rates, but the additional return comes with exposure to the financial health of the issuing company. Bank FDs, particularly with insured banks, provide the additional benefit of DICGC deposit insurance up to ₹5 lakh per depositor per bank, subject to applicable conditions.
For investors comparing the two, the highest interest rate should not automatically win. Credit quality, insurance coverage, liquidity, taxation, tenure and the amount being invested are equally important.
The smarter approach is to ask not just "Which FD pays more?", but "Is the additional return sufficient compensation for the additional risk I am taking?"
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial, investment or tax advice. Fixed deposits carry issuer-specific risks, and corporate deposits are not covered by DICGC insurance. Interest rates, tax rules and deposit regulations can change. Investors should verify the latest terms, credit ratings and regulatory information before investing.
Frequently Asked Questions
What is the main difference between a corporate FD and a bank FD?
A bank FD is a deposit with a bank, while a corporate FD is a deposit with an eligible company. Corporate FDs may offer higher interest rates but carry issuer-specific credit risk and do not receive DICGC deposit insurance.
Are corporate FDs covered by DICGC insurance?
No. DICGC insurance applies to eligible deposits with insured banks. DICGC insurance does not cover corporate deposits, including deposits mobilised by NBFCs. The current insurance limit for eligible bank deposits is ₹5 lakh per depositor per bank, including principal and interest, subject to applicable conditions.
Are AAA-rated corporate FDs completely safe?
No. An AAA rating indicates a high level of assessed credit quality, but it is not a guarantee against default. Credit ratings can change, and investors should continue to monitor the issuer's financial position.
Why do corporate FDs offer higher interest rates than bank FDs?
Corporate FDs may offer higher rates because companies need to attract funds and investors generally demand additional compensation for taking higher issuer-specific credit risk.