
Why Goal-Based SIPs Are Better Than Random Investing
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
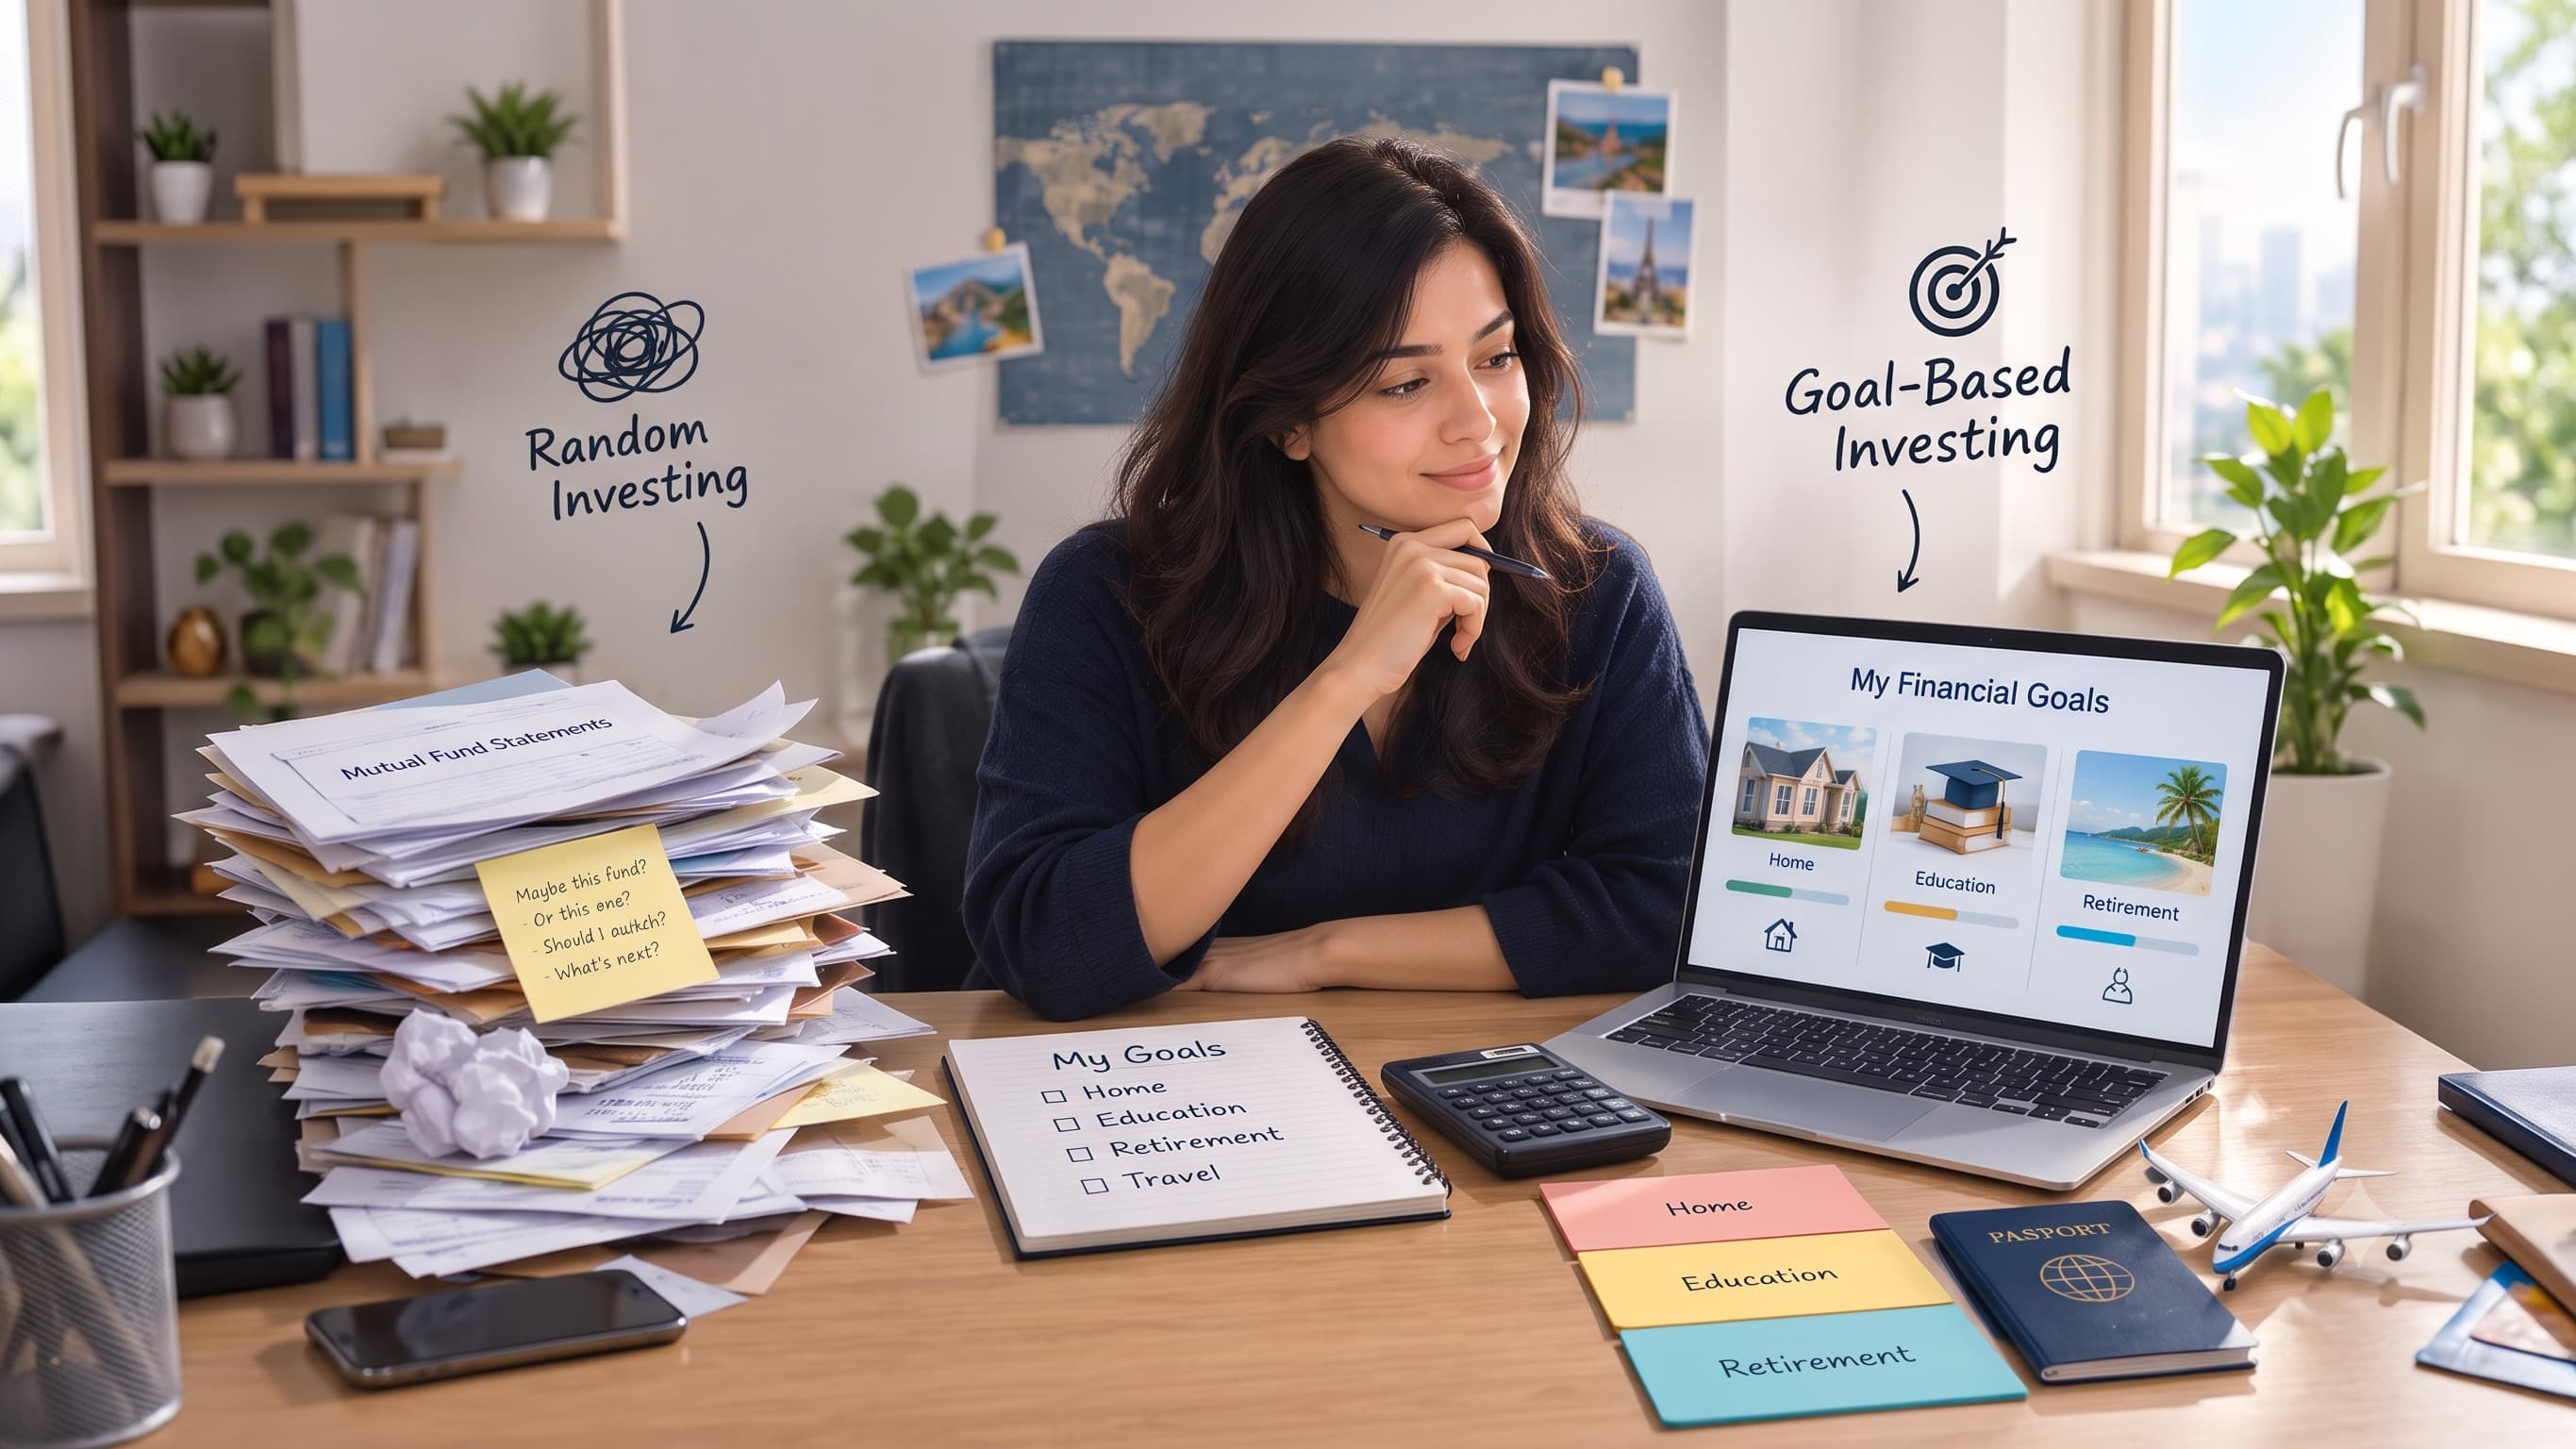
Goal-based investing transforms monthly savings from random contributions into a targeted roadmap for specific milestones like buying a home or funding retirement. By assigning each Systematic Investment Plan a clear purpose, timeline, and risk level, you can protect short-term targets from market downturns while giving long-term wealth the time it needs to compound.
Why Goal-Based SIPs Are Better Than Random Investing
Investing every month is a good habit. But simply putting money into mutual funds without knowing what the money is meant for can make investing harder to manage.
This is where goal-based investing can help.
Instead of asking, “Which mutual fund should I invest in?”, goal-based investing starts with a different question:
“What am I investing this money for, and when will I need it?”
A goal-based SIP connects your investment to a specific financial objective, such as buying a house, funding your child's education, taking an international vacation or building a retirement corpus.
It does not guarantee better returns than random investing. Its advantage is that it gives your investment a purpose, timeline and decision-making framework.
What Is Goal-Based Investing?
Goal-based investing means planning investments around specific financial goals.
For example, instead of having a general SIP of ₹20,000 every month, an investor could divide the investment according to different objectives:
Goal | Time Horizon | Monthly SIP |
International vacation | 3 years | ₹8,000 |
Child's education | 12 years | ₹7,000 |
Retirement | 25 years | ₹5,000 |
Illustrative example only.
The important point is that each investment has a purpose and a time horizon.
SEBI advises investors to consider their financial goals, investment horizon and risk appetite before choosing investments. Asset allocation should also reflect these factors.
Why Is Random Investing a Problem?
Random investing does not necessarily mean investing badly.
It could simply mean investing whenever you have surplus money, choosing funds based mainly on recent performance or adding another SIP without knowing which goal it supports.
The problem appears when you eventually need the money.
Imagine you have accumulated ₹8 lakh across several mutual funds. You now need ₹6 lakh for a house down payment within one year.
The portfolio may have grown well over time, but if a large portion is exposed to market volatility, its value may not be suitable for a goal that is only months away.
The investment was not necessarily wrong.
The mismatch between the investment and the goal was the problem.
Goal-Based SIP vs Random Investing
Goal-Based SIP | Random Investing |
Starts with a financial goal | Often starts with an investment product |
Has a target amount | May not have a defined target |
Has a time horizon | Time horizon may be unclear |
Risk can be matched to the goal | Risk may be chosen independently |
Progress can be measured | Progress may be difficult to evaluate |
Helps separate different objectives | Multiple goals may get mixed together |
This is why the random investing vs goal based comparison is less about which method earns more and more about which method creates better financial discipline.
How Do You Map SIPs to Financial Goals?
A simple process can make mapping SIP to goals easier.
1. List your important goals
Start with goals that have a financial value and a timeframe.
Examples include:
Emergency reserve
Home down payment
Child's education
International vacation
Retirement
Financial independence
Do not start by selecting mutual funds.
Start with the goal.
2. Estimate the future amount required
The amount you need today may not be the amount you need several years from now.
For example, if higher education currently costs ₹15 lakh, the eventual requirement could be higher because of inflation.
Your goal amount should therefore be based on the expected future cost rather than simply today's price.
3. Add a timeline
Every goal should have an approximate date.
A ₹10 lakh requirement five years from now is different from a ₹10 lakh requirement 15 years from now.
The longer the horizon, the more time you may have to manage market fluctuations. Short-term goals generally require greater attention to capital stability and liquidity.
4. Decide the investment approach
Once you know the goal and timeline, you can consider an appropriate asset allocation.
For long-term goals, investors may have the capacity to take more market risk, depending on their risk tolerance.
For short-term goals, highly volatile investments may be unsuitable because a market decline close to the goal date can affect the amount available when the money is needed.
SEBI's investor education material similarly emphasises matching investments with financial goals, risk tolerance and investment horizon.
5. Track each SIP against a goal
This is where tagging mutual funds to goals can become useful.
For example:
SIP A → Retirement
SIP B → Child's Education
SIP C → Home Down Payment
This makes portfolio review more meaningful.
Instead of asking, “Is my mutual fund performing well?”, you can ask:
“Am I still on track to achieve this goal?”
What Are the Benefits of Goal-Based Investing?
Better clarity
You know why you are investing and what the money is intended to achieve.
Easier progress tracking
You can compare your current corpus with the amount required for the goal.
Better risk decisions
The investment horizon becomes an important input when deciding how much market risk may be appropriate.
Less mixing of priorities
Money meant for retirement does not have to be treated the same way as money needed for a vacation next year.
More disciplined behaviour
A clearly defined goal can make it psychologically easier to continue investing because the SIP is connected to something meaningful.
This is one of the potential psychological benefits of goal based SIP investing. However, behaviour differs between investors, so it should not be treated as a guaranteed behavioural outcome.
Can Goal-Based Investing Reduce Risk?
It can help manage risk, but it cannot eliminate investment risk.
For example, an investor with a retirement goal 25 years away may have a different risk capacity from someone who needs a house down payment next year.
Goal-based planning makes this difference visible.
It can also encourage investors to review and gradually adjust their portfolio as the goal approaches.
However, even a goal-based mutual fund portfolio can lose value. Mutual funds are market-linked products and do not provide guaranteed returns.
Can Existing Mutual Funds Be Tagged to Goals?
Yes, as a planning exercise.
Suppose you already own four mutual funds. Instead of immediately selling them, you can first map them against your existing goals.
Ask:
What goal is this investment supporting?
When will I need the money?
Does the current risk level suit that timeline?
Is the investment duplicated elsewhere in my portfolio?
Am I on track to reach the required amount?
This can turn an unstructured portfolio into a more understandable one.
Tagging does not change the nature, risk or taxation of a mutual fund. It is simply a way of organising your investment plan.
Common Mistakes in Goal-Based SIP Planning
Avoid these mistakes:
Choosing a mutual fund before defining the goal.
Assuming a fixed return while calculating the goal.
Ignoring inflation for long-term goals.
Taking excessive equity risk for a near-term requirement.
Never reviewing the SIP amount.
Mixing emergency money with long-term goals.
Treating past fund performance as a future return expectation.
Creating too many goals and making the portfolio unnecessarily complicated.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
The Goal-Based SIP Framework
A simple framework is:
Goal → Amount → Timeline → SIP → Risk → Review → Adjustment
For example:
Child's education → ₹40 lakh → 12 years → Monthly SIP → Suitable asset allocation → Annual review → Increase SIP if required
This is more informative than simply saying, “I invest ₹15,000 every month.”
The SIP amount is only one part of the investment plan.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
Bottom Line
Goal-based SIPs are not automatically better because they produce higher returns.
They can be better because they connect money with purpose.
Instead of randomly accumulating mutual fund investments, you can assign each investment a job: retirement, education, home, travel or another meaningful objective.
The result is a portfolio that is easier to understand, monitor and adjust.
Contact us for a more personalised guidance.
Investing should not only answer “How much am I investing?” It should also answer “What am I investing for?”
This article is for general educational purposes only. Mutual fund investments are subject to market risks. Returns are not guaranteed. Investors should consider their own financial situation, goals, investment horizon and risk tolerance before making investment decisions.
Frequently Asked Questions
What is goal-based investing?
Goal-based investing means planning your investments around specific financial objectives, such as retirement, education, a home or travel.
What is a goal-based SIP?
A goal-based SIP is a regular mutual fund investment that is planned around a specific financial goal, its target amount and timeline.
Is goal-based SIP better than normal SIP?
A goal-based SIP can provide more structure because the investment is connected to a specific objective. It does not guarantee higher returns than a normal SIP.
Can one SIP be used for multiple goals?
It is possible, but separating investments by goal can make tracking easier, particularly when the goals have different timelines and risk requirements.
Can I tag my existing mutual funds to goals?
Yes. You can review your existing investments and map them to different financial goals based on their purpose, timeline and risk profile.
Does goal-based investing reduce market risk?
No. It does not eliminate market risk. It can help investors choose and manage investments with greater awareness of their goal horizon and risk tolerance.
How do I start goal-based financial planning?
Start by listing your goals, estimating their future cost, assigning timelines and then determining the investment contribution and asset allocation required for each goal.
Does goal-based investing guarantee that I will achieve my goals?
No. Market-linked investments can fluctuate and returns are not guaranteed. Goals may need to be reviewed and contributions adjusted over time.




