
ULIP vs Term Insurance and Mutual Funds: The Real Cost Comparison
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
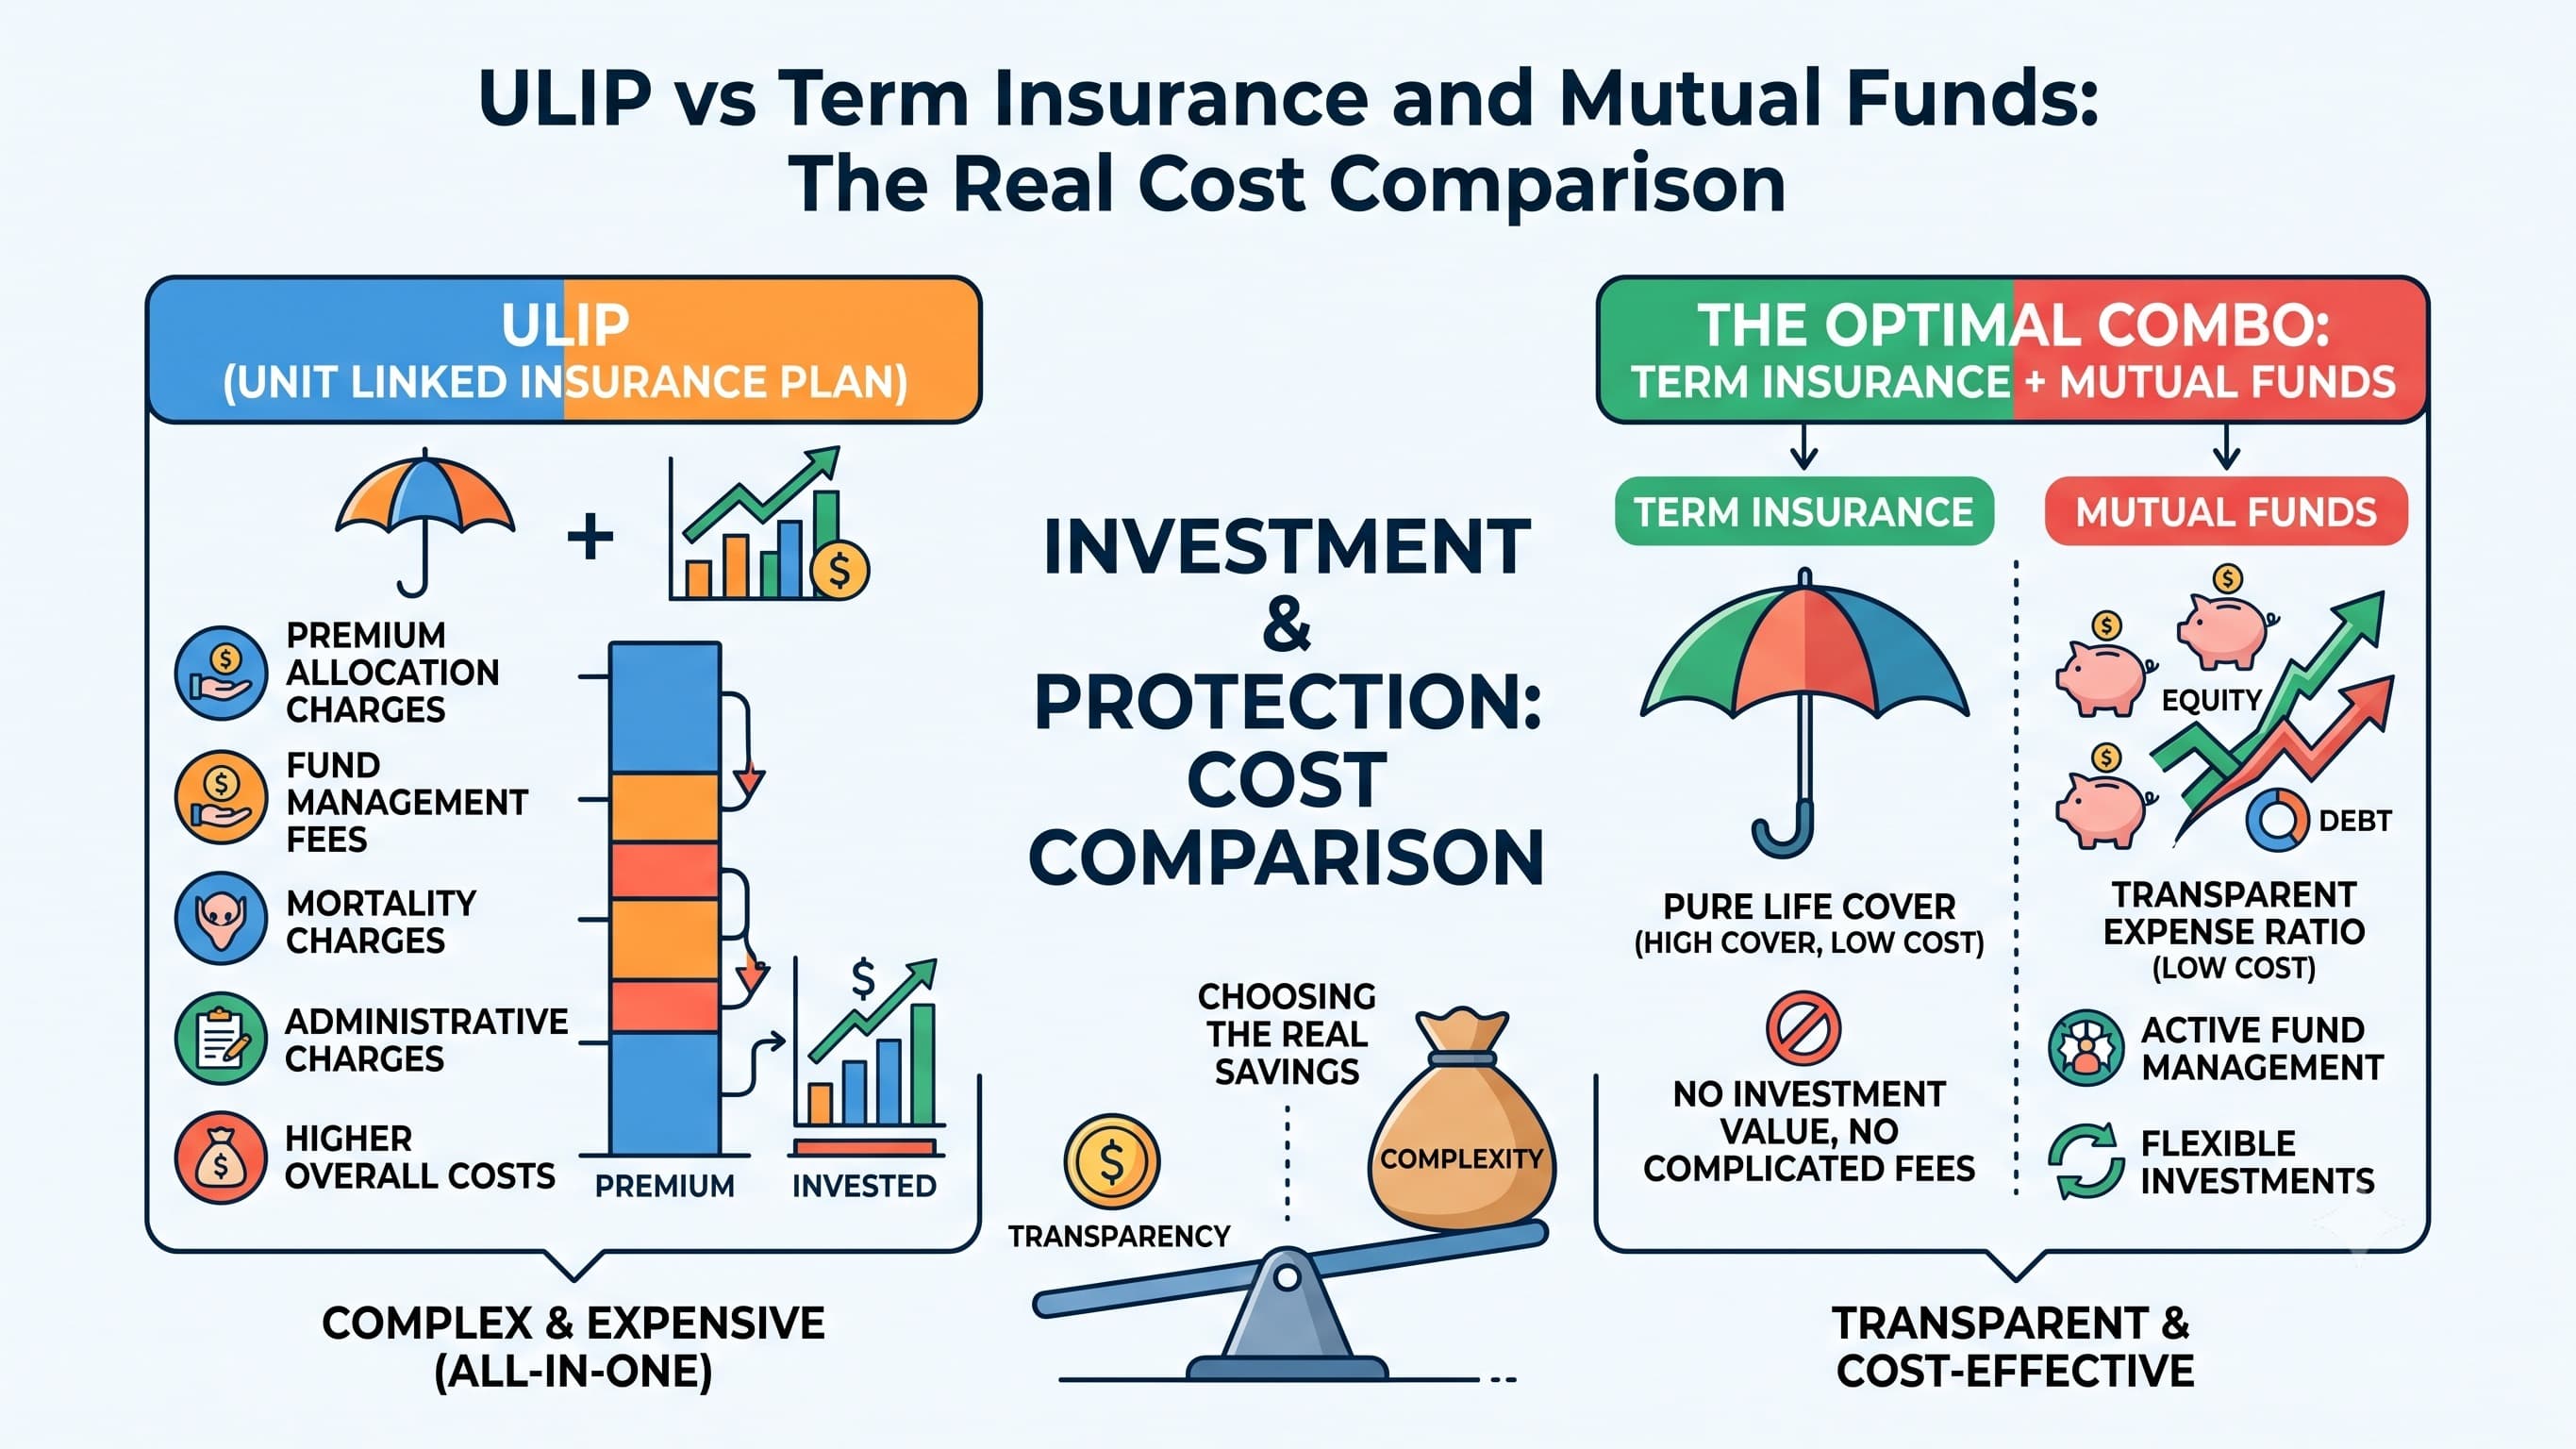
Compare ULIP vs term insurance and mutual funds on charges, returns, tax treatment, flexibility and life cover to understand the real cost of each option.
When you want both life insurance and investment growth, two approaches often come up: buying a ULIP or following the "buy term and invest the rest" approach—taking a separate term insurance policy and investing the remaining money in mutual funds.
At first glance, a ULIP can appear convenient because insurance and investment are combined in one product. A separate term plan plus mutual funds, on the other hand, keeps the two objectives distinct. The difference becomes more important when you look beyond the premium and compare charges, investment flexibility, liquidity, taxation and potential returns.
So, in the ULIP vs mutual funds comparison, the real question is not simply which product can generate higher returns. It is whether combining insurance and investment in one product makes sense for your financial needs.
ULIP vs term insurance: What are you actually buying?
A ULIP, or Unit Linked Insurance Plan, combines life insurance with market-linked investment. Part of the premium is used to provide insurance cover, while the remaining amount is allocated to investment funds after applicable charges.
With the alternative approach, you buy a term insurance policy separately for life cover and invest independently in mutual funds.
This creates a fundamental difference:
Feature | ULIP | Term Insurance + Mutual Funds |
Life Insurance | Included | Separate term policy |
Investment | Included | Separate mutual fund investment |
Return | Market-linked | Market-linked |
Investment choice | Depends on ULIP funds | Wider range of mutual funds |
Returns Liquidity | Subject to ULIP rules Multiple policy and fund-related charges may apply | Mutual funds generally offer greater flexibility |
Charges | Charges are disclosed in policy documents | Term premium + mutual fund expenses |
Transparency | Depends on policy terms | Costs are separately visible |
Flexibility | Depends on policy terms | Insurance and investment can be changed independently |
The key advantage of separating the two is that you can decide how much insurance you need independently of how much you want to invest.
Buy term and invest the rest: How does the strategy work?
The buy term and invest the rest approach is straightforward.
Suppose an individual has ₹50,000 available annually for financial protection and investment.
Instead of putting the entire amount into a ULIP, the investor could purchase a term insurance policy for the required life cover and invest the remaining amount in mutual funds.
This approach separates two different financial goals:
Term insurance → protection for dependants
Mutual funds → wealth creation
The amount allocated to each can be adjusted independently as circumstances change.
For example, if your income increases and you need more life cover, you can evaluate your insurance separately without changing your investment portfolio.
ULIP charges vs mutual fund expense ratio: What is the real cost?
The ULIP charges vs mutual fund expense ratio comparison is important because the premium you pay is not necessarily the amount that gets invested.
Depending on the policy, ULIPs can have charges such as:
Premium allocation charges
Policy administration charges
Fund management charges
Mortality charges
Discontinuance-related charges
Other applicable charges
The exact structure varies by policy, so investors should examine the specific product's benefit illustration and policy documents rather than assuming every ULIP has identical costs. IRDAI-regulated ULIP documents disclose charges such as mortality, fund management and policy administration charges.
Mutual funds have a different cost structure. The expense ratio represents expenses charged to the scheme and is reflected in the NAV. SEBI regulates the expense-ratio framework applicable to mutual fund schemes.
This does not mean that every ULIP is necessarily more expensive than every mutual fund. The correct comparison is between the actual charges of the specific ULIP and the specific mutual fund, along with the cost of the term insurance used in the alternative strategy.
ULIP vs SIP returns: Is one guaranteed to perform better?
The ULIP vs SIP returns comparison needs some caution.
Neither ULIPs nor equity mutual funds guarantee market-linked returns. The outcome depends on the underlying investments, investment horizon, market conditions, charges and taxes. Neither ULIPs nor equity mutual funds guarantee market-linked returns. The outcome depends on the underlying investments, investment horizon, market conditions, charges, taxes and your risk profile.
A ULIP may offer different fund options, such as equity, debt or balanced funds, depending on the product. Mutual funds offer a much wider range of categories and investment strategies.
Therefore, comparing a ULIP's historical fund return with a mutual fund's return without adjusting for charges and the nature of the underlying portfolio can produce a misleading conclusion.
For example, if two investments both generate the same gross market return, the amount ultimately available to the investor can differ because of the costs deducted from each product.
Past performance should not be treated as a guarantee of future returns.
ULIP vs mutual fund returns: Why charges matter over time
Even seemingly small annual costs can affect long-term wealth because investment returns compound over time.
Consider an illustrative example.
Suppose ₹5 lakh is invested for 20 years and the underlying investment generates a hypothetical gross return of 10% per year.
If the effective annual cost is lower in one structure than another, the difference in the final corpus can become meaningful over two decades.
This does not mean a particular ULIP or mutual fund will produce a specific return. It simply demonstrates why investors should compare net outcomes rather than looking only at the headline investment performance.
When comparing ULIP vs mutual fund returns, examine:
Gross investment performance
All applicable charges
Insurance costs
Investment horizon
Tax treatment
Fund allocation
Exit conditions
What about tax benefits?
Tax treatment is another factor in the ULIP vs term plan comparison.
Life insurance premiums may qualify for deductions under applicable provisions, subject to the relevant conditions and limits. ULIPs may also receive specific tax treatment depending on when the policy was issued, the premium amount and other statutory conditions.
For ULIPs issued on or after 1 February 2021, the tax treatment of maturity proceeds can be affected where the aggregate annual premium exceeds the prescribed ₹2.5 lakh threshold for eligible unit-linked insurance policies, subject to the applicable conditions. The tax treatment can also depend on whether the policy satisfies the conditions for exemption.
Mutual fund taxation works differently and depends on the type of mutual fund and the applicable holding period and tax rules.
Therefore, term insurance and mutual fund investing should not be compared with a ULIP purely based on whether an investment product is "tax-free".
Tax rules can change, and investors should verify the provisions applicable to their policy and financial year before making decisions.
ULIP vs term insurance + mutual funds: What about flexibility?
Flexibility is one of the biggest practical differences.
With a separate term plan and mutual fund portfolio, you can make independent decisions.
You could:
Increase your mutual fund SIP
Stop or modify an SIP
Change your mutual fund allocation
Buy additional insurance when required
Maintain multiple mutual fund categories for different goals
A ULIP also provides investment fund options and may allow switching between funds, depending on policy terms. However, the investment remains within the insurance contract.
This distinction matters because insurance and investments serve different purposes.
Is ULIP better than mutual fund investing?
The question is ULIP better than mutual fund investing does not have a universal answer.
A ULIP may appeal to someone who values having insurance and investment within one policy and is comfortable with the product's terms, charges and long-term structure.
The term insurance plus mutual fund approach may appeal to investors who prefer greater separation between protection and wealth creation.
The choice should therefore be based on the actual policy and investment requirements—not simply on the product label. The choice should therefore be based on the actual policy, investment requirements and financial goals
Term insurance vs ULIP: What should you consider?
Before choosing between term insurance vs ULIP, ask:
How much life insurance cover does my family actually need?
What investment return and risk am I comfortable with?
How long can I remain invested?
What charges will I pay over the entire policy/investment period?
How easily can I access or change my investment?
What tax treatment applies to my specific product?
Do I understand the policy's surrender, discontinuance and withdrawal conditions?
A term plan should primarily be evaluated on the adequacy of its life cover, policy terms and premium. A mutual fund should be evaluated based on its investment objective, risk, portfolio, costs and suitability for the investor's goal.
A ULIP needs both dimensions to be evaluated together.
The Bottom Line
The ULIP vs mutual funds decision is ultimately about whether you want your insurance and investment decisions combined or separated.
A ULIP provides both within one insurance contract, but investors need to understand its various charges, investment options, lock-in and policy conditions.
The ULIP vs term insurance alternative separates protection from wealth creation. You buy term insurance for the life cover you need and invest separately in mutual funds based on your goals and risk profile.
The "buy term and invest the rest" approach is therefore not automatically superior in every situation. The important step is to compare the actual costs, insurance cover, investment flexibility, taxation and expected holding period of the products you are considering.
Rather than asking which product is universally better, ask whether the structure fits your financial objectives.
Disclaimer: This article is for general educational purposes only and does not constitute personalised insurance, investment or tax advice. Market-linked investments carry risk, and returns are not guaranteed. Insurance products have specific terms, conditions, charges and exclusions. Investors should read the policy wording, benefit illustration and scheme-related documents carefully and verify the applicable tax rules before making a decision.
Frequently Asked Questions
Is ULIP better than mutual funds?
There is no universal answer. ULIPs combine insurance and market-linked investment, while mutual funds are investment products without life insurance. The appropriate choice depends on your insurance needs, investment objectives, costs, liquidity requirements and tax situation.
What is the difference between ULIP and term insurance?
A ULIP combines life insurance with investment, whereas term insurance primarily provides life protection for a specified period. Term insurance does not build an investment corpus from the premium in the way a ULIP does.
Is buying term insurance and investing in mutual funds better than a ULIP?
The "buy term and invest the rest" strategy separates insurance from investment, giving investors greater independence over each. However, suitability depends on individual circumstances and the specific products being compared.
Are ULIP charges higher than mutual fund expenses?
The cost structures are different. ULIPs can have several charges, including mortality, fund management and policy administration charges. Mutual funds have an expense ratio and other applicable costs. Investors should compare the actual charges of specific products rather than making a category-wide assumption.
Which gives better returns: ULIP or SIP?
Neither guarantees better returns. A ULIP and an SIP can invest in different underlying assets, and the outcome depends on market performance, charges, taxes and investment duration. Historical returns should not be treated as guaranteed future performance.




