
The 50/30/20 Budgeting Rule for High-Cost Cities: Bangalore and Mumbai
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
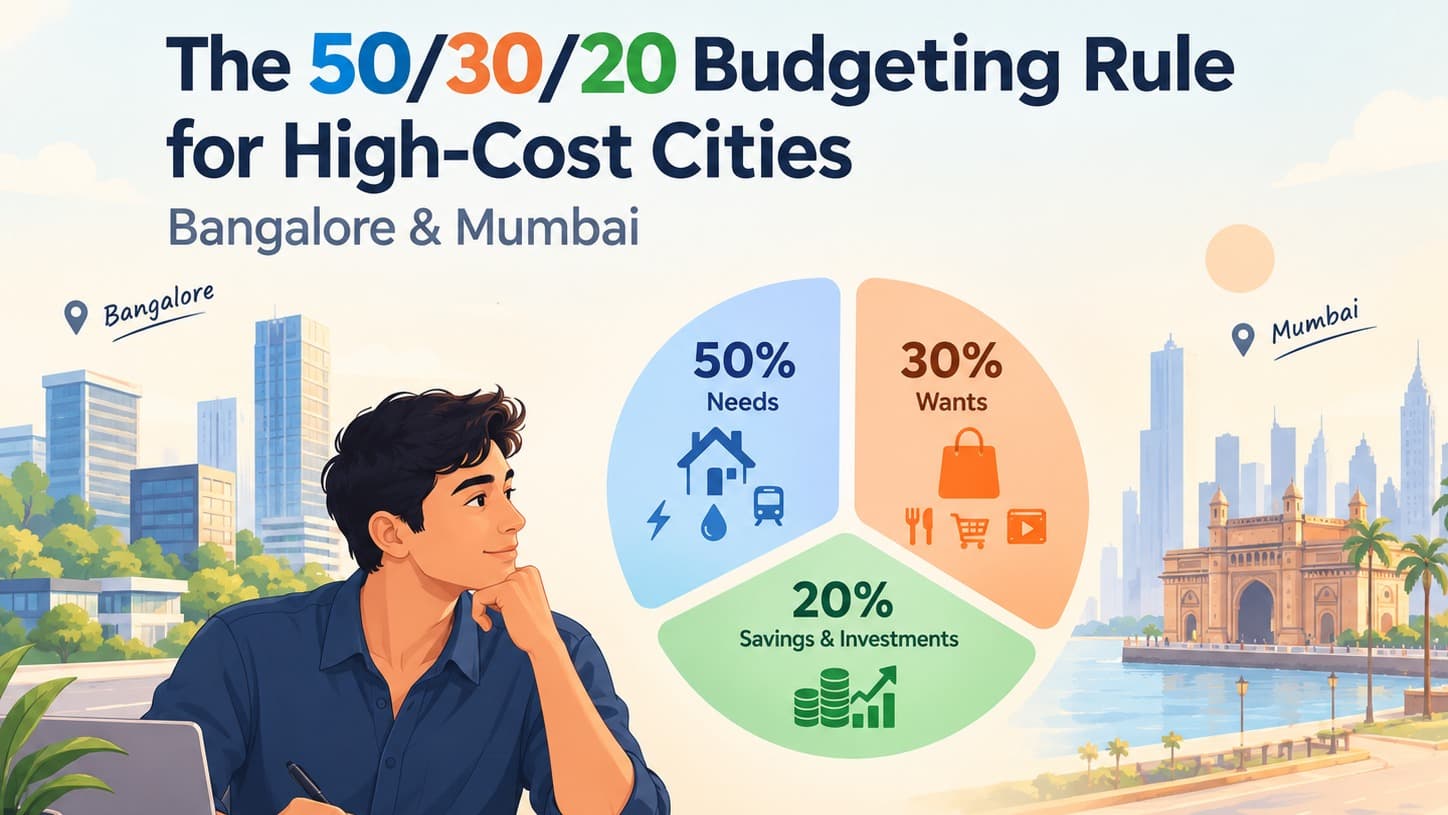
Learn how to apply the 50/30/20 rule in Bangalore and Mumbai. Plan rent, monthly expenses, savings and SIP investments with a practical salary budget.
The 50/30/20 Budgeting Rule for High-Cost Cities: Bangalore and Mumbai
Living in Bangalore or Mumbai can make it difficult to save money, even when you earn a decent salary. Rent, groceries, commuting and everyday expenses can take up a large part of your monthly income. The 50/30/20 rule in India offers a simple way to manage these expenses while making room for savings and investments.
The rule divides your monthly take-home salary into three categories: 50% for needs, 30% for wants and 20% for savings and investments. However, if you live in a high-cost city, you may need to adjust these percentages to match your actual expenses.
What Is the 50/30/20 Budgeting Rule?
The 50/30/20 rule is a budgeting method that helps you divide your after-tax income into essential expenses, lifestyle spending and financial goals.
Here is how it works:
50% for needs: Rent, groceries, electricity, essential transport, insurance premiums and minimum loan payments.
30% for wants: Eating out, shopping, entertainment, subscriptions and holidays.
20% for savings and investments: Emergency funds, SIPs, retirement savings and other financial goals.
For example, if your monthly take-home salary is ₹80,000, the standard allocation would be ₹40,000 for needs, ₹24,000 for wants and ₹16,000 for savings and investments.
The rule is a starting point, not a strict financial requirement. Your budget should reflect your income, responsibilities and cost of living.
Why Does Budgeting in Bangalore and Mumbai Need a Different Approach?
The biggest challenge in managing high living costs is that essential expenses can exceed 50% of your salary before you spend anything on entertainment or shopping.
In Bangalore, your rent and daily commute may depend heavily on how close you live to your workplace. In Mumbai, housing costs and the distance between your home and workplace can also significantly affect your monthly budget.
For example, if your take-home salary is ₹60,000 and your rent is ₹25,000, rent alone consumes around 42% of your income. You still need to pay for groceries, utilities, transport and other essentials.
This is why a rigid 50/30/20 budget may not work for everyone in these cities. Instead of abandoning budgeting, calculate your actual expenses and adjust your spending categories.
How Should You Divide an ₹80,000 Monthly Salary?
Consider the following illustrative example for a salaried professional living in Bangalore or Mumbai.
Budget category | Monthly allocation |
Rent and household expenses | ₹28,000 |
Groceries, utilities and transport | ₹12,000 |
Lifestyle and discretionary spending | ₹16,000 |
Emergency fund and other savings | ₹8,000 |
SIP investments | ₹16,000 |
Total | ₹80,000 |
In this example, 50% of the salary goes towards needs, 20% towards wants and 30% towards savings and investments.
This is an adapted budget, not a prescribed allocation for every metro resident. Someone paying higher rent or supporting family members may need to allocate more towards essential expenses.
The important point is to assign a purpose to your income before the month begins. Review actual spending at the end of each month and adjust the budget accordingly.
How Can You Save 20% of Your Salary in Mumbai or Bangalore?
Saving 20% of your salary becomes easier when you plan your expenses around your financial priorities rather than saving whatever remains at the end of the month.
Start with these steps:
1. Set a realistic housing budget. Compare rent, maintenance and commuting costs together. A cheaper house far from work may not produce meaningful savings if travel expenses and travel time increase significantly.
2. Separate needs from wants. Groceries are generally a need, but frequent food delivery may partly fall under discretionary spending. Review recurring subscriptions, shopping and weekend expenses to identify areas you can reduce.
3. Automate your savings. Set aside a predetermined amount after your salary arrives. This reduces the temptation to spend the entire balance during the month.
4. Build an emergency fund. Keep money available for unexpected expenses, job loss or medical needs. The amount and timeline should depend on your responsibilities and income stability.
5. Increase savings when your salary grows. When you receive a raise, direct part of the increase towards your financial goals instead of automatically increasing your lifestyle expenses.
If essential expenses already consume 60% of your income, you could temporarily use a 60/20/20 split, provided it fits your circumstances. If that is still unrealistic, choose a sustainable savings amount and work towards increasing it over time.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
How Much of Your Monthly Salary Should Go Towards an SIP?
An SIP, or Systematic Investment Plan, allows you to invest a fixed amount regularly in a mutual fund scheme. It can help build investing discipline without requiring you to invest a large lump sum at once. SEBI explains how mutual funds and SIPs work in its investor education resources.
Under the 50/30/20 rule, SIP investments can form part of the 20% savings and investments category. However, you do not need to put your entire 20% into mutual funds.
For example, on a take-home salary of ₹60,000, a 20% allocation equals ₹12,000. Depending on your circumstances, you might divide this between an emergency fund and a monthly SIP.
If you have expensive outstanding debt or no emergency savings, you may need to address those priorities before increasing your investments.
Choose mutual fund schemes based on your financial goals, investment horizon and risk tolerance. Mutual funds are market-linked investments, and returns are not guaranteed. An SIP does not eliminate market risk.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
Common Budgeting Mistakes to Avoid
When managing a metro-city budget, avoid these common mistakes:
Following percentages blindly: A budget that ignores actual rent and essential expenses is unlikely to remain practical.
Ignoring small recurring payments: Subscriptions, delivery charges and frequent small purchases can add up over time.
Investing without emergency savings: Unexpected expenses can force you to withdraw investments at an unsuitable time.
Increasing lifestyle expenses after every raise: Higher income does not automatically translate into higher savings.
Expecting fixed investment returns: Review your financial goals and risk tolerance instead of relying on assumed market returns.
Contact us for a more personalised guidance.
Final Takeaway
The 50/30/20 rule provides a useful starting point for budgeting, but living in Bangalore or Mumbai may require a more flexible approach. Track your essential expenses, control discretionary spending and build a savings habit that fits your income.
The goal is not to follow a percentage perfectly every month. It is to make your money work towards both your present needs and future financial goals.
Review your budget regularly, increase your savings as your income grows and choose investments based on your individual circumstances.
Frequently Asked Questions
Is the 50/30/20 rule suitable for Indian salaries?
Yes, it can be a useful starting point. However, people with high rent, EMIs or family responsibilities may need to adjust the percentages to suit their circumstances.
How much should I save every month in Mumbai?
Start by calculating your essential expenses and financial obligations. Saving 20% of take-home income is a useful target, but a smaller sustainable amount may be more realistic initially.
How can I manage high living costs in Bangalore?
Compare housing and commuting costs, plan essential spending, reduce unnecessary recurring expenses and automate savings after receiving your salary.
Should I invest 20% of my salary in an SIP?
Not necessarily. The 20% category includes savings and investments, which may cover emergency funds and other financial goals as well as SIPs. Your investment amount should reflect your financial situation and risk tolerance.
What if my rent alone exceeds 30% of my salary?
Review your total housing and commuting costs, consider shared accommodation or a different location if practical, and adjust discretionary spending. Avoid taking on unaffordable commitments simply to meet a budgeting percentage.




