
Step-Up SIPs: The Secret to Reaching Your Financial Goals Faster
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
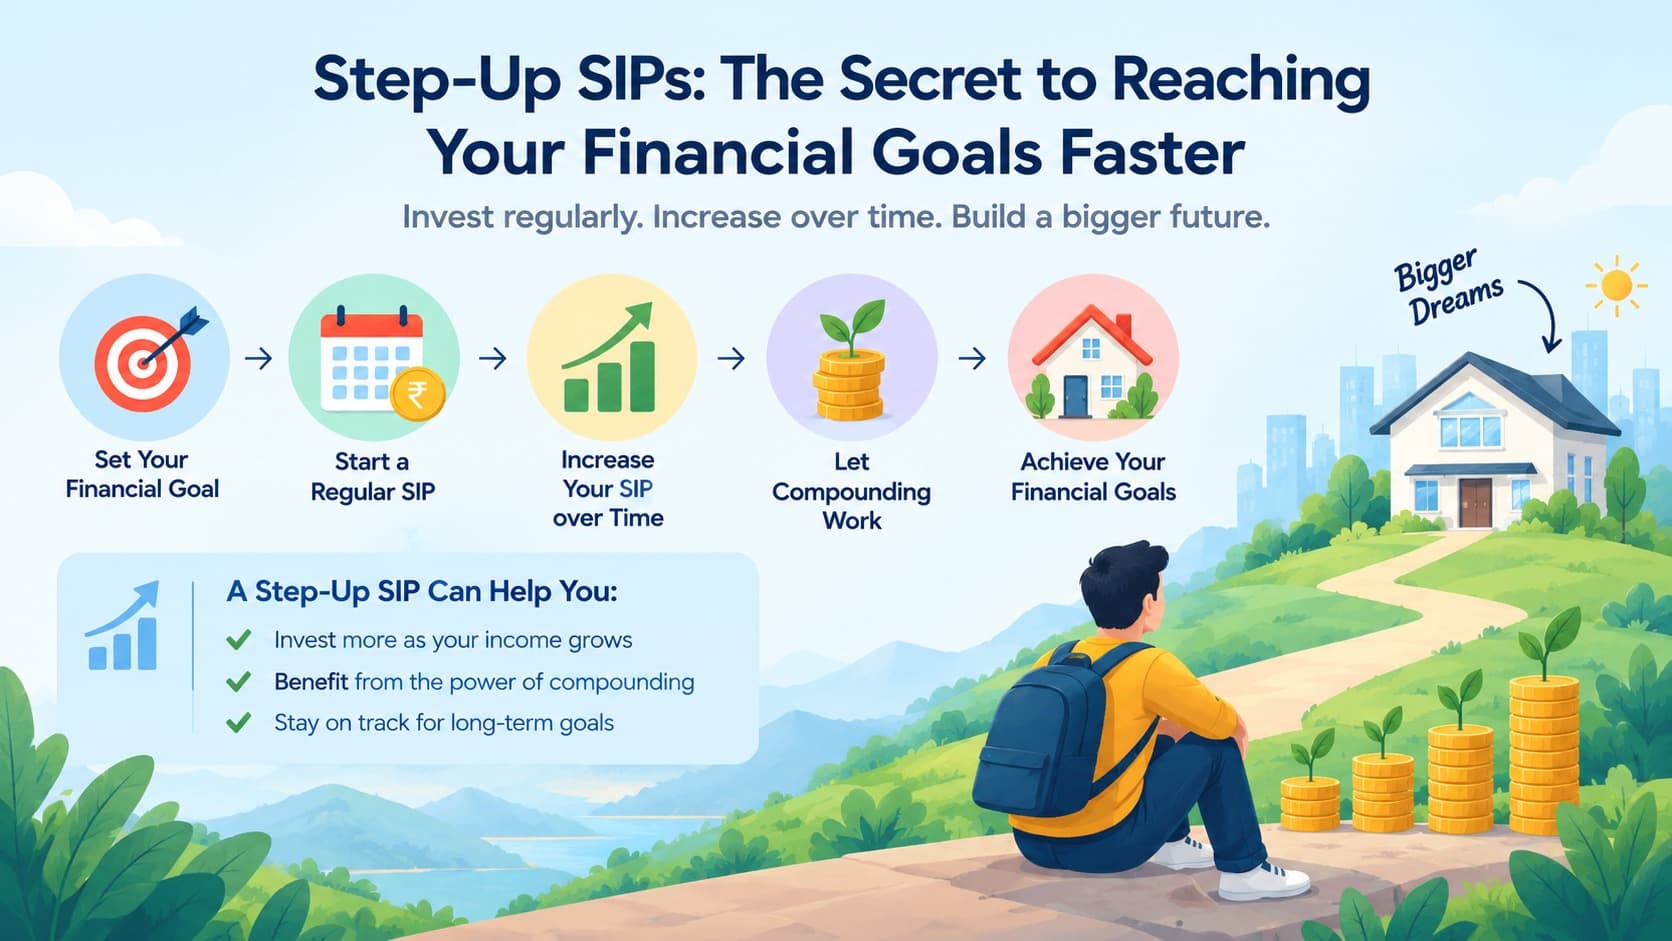
A Step-Up SIP lets you raise your monthly investment gradually, such as once a year, as your salary goes up. This simple habit helps you build a much bigger savings fund over time without straining your day-to-day budget.
Step-Up SIPs: The Secret to Reaching Your Financial Goals Faster
Starting a SIP is a simple way to invest regularly. But what happens when your income increases while your SIP stays the same?
This is where a Step-Up SIP, also called a Top-Up SIP, can help.
A Step-Up SIP allows you to increase your SIP investment at predefined intervals. Instead of investing ₹10,000 every month for 15 years, for example, you could start at ₹10,000 and increase the amount every year as your income grows.
The idea is simple: invest regularly, increase your contribution gradually and give your money more time to potentially compound.
What Is a Step-Up SIP?
A Step-Up SIP is an SIP where the investment amount increases periodically. AMFI scheme documents describe Step-Up SIP as a facility that allows investors to increase their SIP instalment by a fixed amount at predefined intervals.
For example, with a starting SIP of ₹10,000 and a 10% annual increase:
Year | Monthly SIP |
1 | ₹10,000 |
2 | ₹11,000 |
3 | ₹12,100 |
4 | ₹13,310 |
5 | ₹14,641 |
The exact Step-Up options can vary between mutual fund schemes and platforms.
The objective is to make your investment contribution grow alongside your earning capacity.
Step-Up SIP vs Normal SIP
The main difference is straightforward.
A normal SIP generally keeps the contribution constant, while a Step-Up SIP increases the contribution periodically.
Suppose two investors start with ₹10,000 per month.
Investor A continues with ₹10,000.
Investor B increases the SIP by 10% every year.
If both invest in the same fund, Investor B is contributing more money over time. This can potentially result in a larger corpus, although it also requires a larger investment.
So, the Step-Up SIP vs normal SIP decision is mainly about your cash flow and investment goal, not about one method guaranteeing better returns.
Why Increase Your SIP Amount Annually?
Your income may increase over time because of salary increments, promotions or business growth.
If your SIP remains unchanged for many years, your investment contribution may not reflect your increased ability to save.
Increasing your SIP annually can help you invest more gradually instead of making a large jump in your monthly commitment.
For example, a ₹10,000 SIP with a 10% annual increase becomes approximately ₹14,641 by the fifth year.
However, the increase should be realistic. A SIP that becomes difficult to maintain can hurt financial discipline.
Compounding With Step-Up SIP
Compounding works over time because investment growth can itself contribute to future growth.
A Step-Up SIP adds another element: your invested amount also increases over time.
AMFI explains that long-term investing can benefit from compounding, while also noting that rupee-cost averaging through SIP does not guarantee profits or protect against losses.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
Illustrative example
Suppose you invest ₹10,000 per month and increase the SIP by 10% every year.
If we assume a hypothetical 12% annual return:
A constant ₹10,000 SIP for 15 years could accumulate around ₹50 lakh.
A 10% annual Step-Up SIP could accumulate around ₹80 lakh.
These figures are illustrative only. The difference also exists because the Step-Up investor contributes substantially more money.
Actual mutual fund returns will vary and are not guaranteed.
How to Use a Step-Up SIP Calculator
A Step-Up SIP calculator can help estimate how your corpus could change when your investment increases periodically.
You generally need:
Starting monthly SIP
Annual Step-Up percentage or amount
Investment period
Assumed rate of return
For example:
Starting SIP: ₹10,000
Annual increase: 10%
Period: 15 years
Assumed return: 12%
The calculator can estimate your total investment and potential future corpus.
But remember: the return assumption is only an assumption. A calculator should be used for financial planning, not as a prediction of actual returns.
Can a Step-Up SIP Help You Reach ₹1 Crore?
Yes, it can be part of a strategy to target a ₹1 crore corpus.
But there is no single SIP amount that guarantees ₹1 crore.
The required investment depends on:
Starting SIP
Investment horizon
Annual Step-Up
Investment returns
Market conditions
For example, a young investor with a long investment horizon may start with a smaller SIP and gradually increase it as income grows.
This is why a Step-Up SIP to reach ₹1 crore should be planned around your income and timeline rather than simply choosing a target number from a calculator.
What Is a Goal-Based Step-Up SIP?
A goal-based Step-Up SIP starts with the financial goal.
For example:
Goal: ₹50 lakh
Time horizon: 12 years
Starting SIP: Based on your current capacity
Annual increase: Based on expected income growth
The goal could be retirement, higher education, a home down payment or another long-term financial requirement.
SEBI's investor education material highlights the importance of considering financial goals, investment horizon and risk while making investment decisions.
As the goal gets closer, investors should also review whether the portfolio's risk remains appropriate for the time remaining.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
Common Step-Up SIP Mistakes
Avoid these common mistakes:
Choosing an unrealistic annual increase
Assuming a fixed return every year
Ignoring inflation
Increasing investments while neglecting emergency savings
Taking excessive risk for a short-term goal
Never reviewing the portfolio as the goal approaches
Treating ₹1 crore as a universal target
A higher SIP does not automatically make an investment suitable for your goal.
Contact us for a more personalised guidance.
Key Takeaway
A Step-Up SIP is essentially a way to make your investment contribution grow as your income grows.
The framework is simple:
Set your goal → Start a manageable SIP → Increase it periodically → Stay invested → Review your risk → Track the goal.
The biggest benefit of a Top-Up SIP is that you can start with an amount that fits your current income and gradually invest more as your financial capacity improves.
However, Step-Up SIPs do not guarantee returns. The underlying mutual fund remains market-linked, and your investment can gain or lose value.
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. Past performance does not guarantee future returns.
Frequently Asked Questions
Is Step-Up SIP better than a normal SIP?
It can be useful when you expect your investment capacity to increase over time. Neither method guarantees better returns.
How much should I increase my SIP annually?
There is no universal percentage. Choose an increase that is realistic for your income and expenses.
Can Step-Up SIP make ₹1 crore?
It can help you target ₹1 crore, but the outcome depends on the investment amount, period and market-linked returns.
What is a Top-Up SIP?
It is commonly used for a SIP where the investment amount is increased periodically.
Is Step-Up SIP suitable for everyone?
The Step-Up feature can be useful for investors with growing income, but the underlying investment should still match the investor's goal, time horizon and risk profile.




