
How Much SIP Would You Need to Build ₹50 Lakh in 5 Years?
By Divay Diya
About the Author
Divay Diya is a business and digital marketing enthusiast with expertise in market research, SEO, and strategic planning. She explores business growth, marketing, investing, and financial markets, translating research into actionable insights.
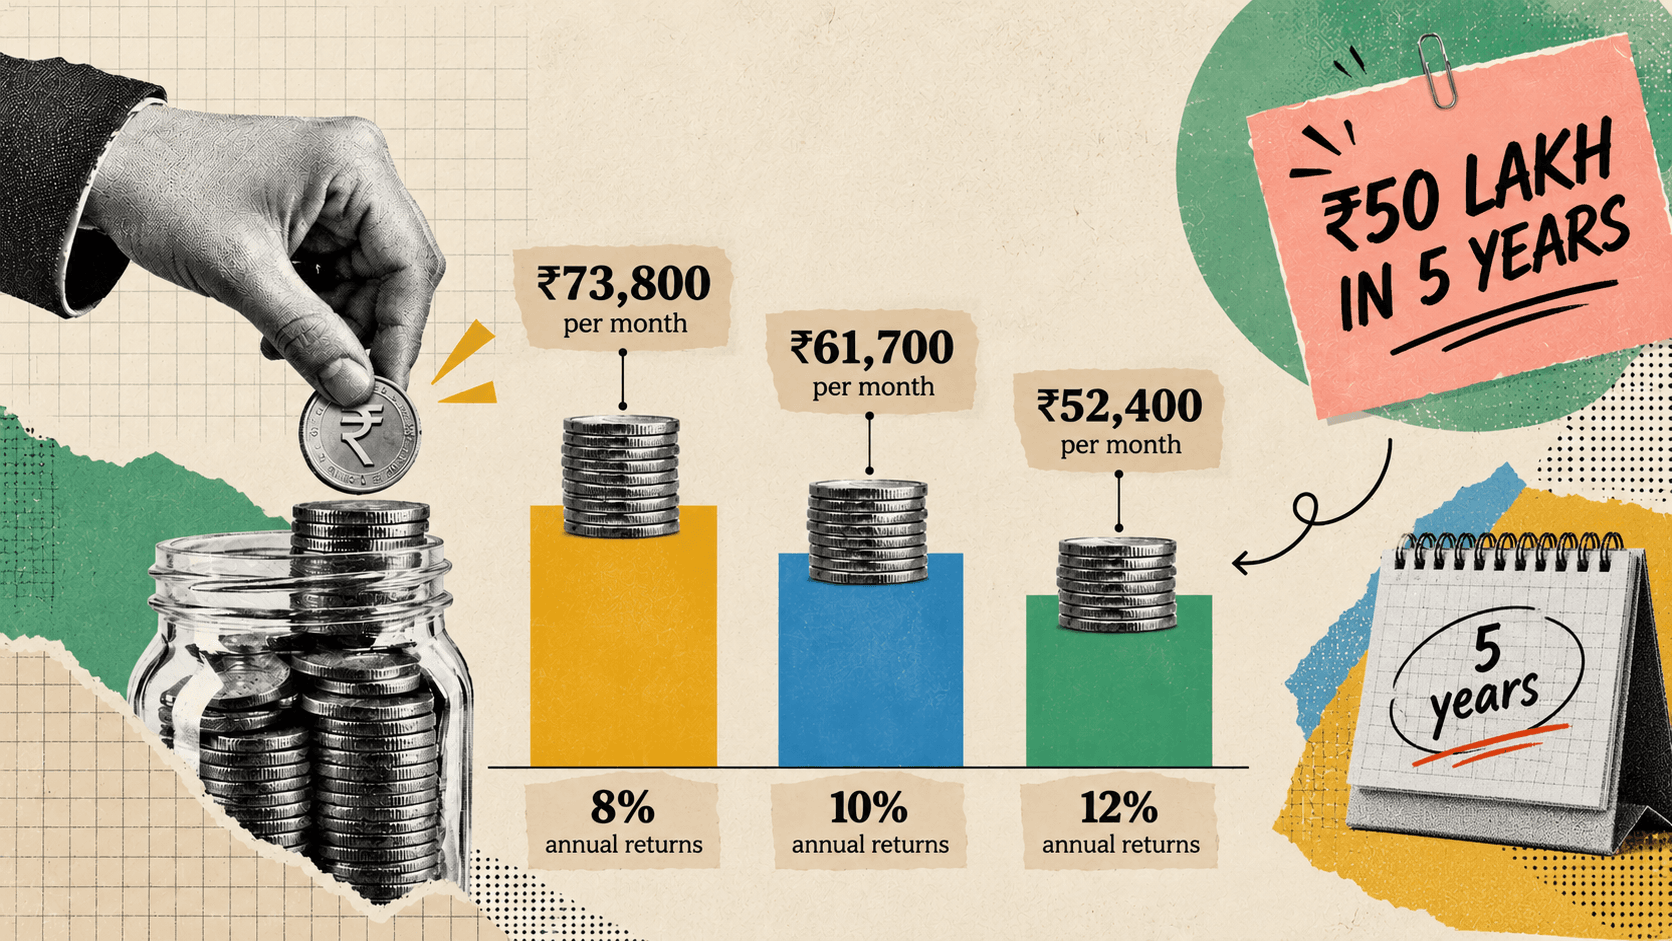
Planning to build ₹50 lakh in five years? Explore the estimated monthly SIP required under different return assumptions, how a Step-Up SIP works, and the risks to consider before investing towards a five-year financial goal.
Building a corpus of ₹50 lakh in five years through a Systematic Investment Plan (SIP) requires a substantial monthly investment. The exact amount depends on the return you assume, how consistently you invest, and whether you increase your contributions over time.
To target ₹50 lakh in five years, you would need to invest approximately ₹61,200 per month at an assumed annual return of 12%. At an assumed return of 8%, the required monthly SIP would be approximately ₹68,050. These figures are illustrative calculations, not guaranteed outcomes.
Here is how much you may need to invest each month under different return assumptions.
Assumed Annual Return | Approximate Monthly SIP | Total Amount Invested Over 5 Years | Illustrative Investment Gains |
|---|---|---|---|
8% | ₹68,050 | ₹40.83 lakh | ₹9.17 lakh |
10% | ₹64,570 | ₹38.74 lakh | ₹11.26 lakh |
12% | ₹61,220 | ₹36.73 lakh | ₹13.27 lakh |
Note: These figures are illustrative. They assume monthly investments at the end of each month over 60 months, with a constant assumed annual return divided by 12 for monthly calculations. Actual mutual fund returns fluctuate, and your final corpus may be higher or lower than ₹50 lakh.
If you are planning a major financial goal, such as funding a child’s education, making a property down payment, or building a financial reserve, understanding the monthly investment required can help you determine whether your target is realistic.
1. How Much SIP Is Required to Accumulate ₹50 Lakh in 5 Years?
The monthly SIP required to target ₹50 lakh depends primarily on the assumed rate of return.
A higher assumed return reduces the amount you need to contribute every month. However, higher-return investments generally involve greater uncertainty and may expose you to higher market risk.
For example, if you invest approximately ₹68,050 every month for five years and earn an assumed annual return of 8%, your investments could grow to around ₹50 lakh under the calculation assumptions used above.
At an assumed annual return of 10%, the monthly requirement falls to approximately ₹64,570. At 12%, it falls further to approximately ₹61,220.
The difference may appear modest when comparing monthly contributions, but the cumulative effect of investment returns becomes more visible over time.
However, you should not select a mutual fund simply because its past returns make your target SIP look smaller. The return assumptions in a calculator are hypothetical, and actual market performance can differ considerably.
What should you consider before choosing a monthly SIP?
Before committing to a five-year SIP, consider the following:
Your monthly income: Ensure the SIP fits comfortably within your budget.
Your financial obligations: Account for rent, education expenses, loan repayments, insurance premiums and other essential costs.
Your emergency fund: Avoid investing money you may need immediately for unexpected expenses.
Your investment risk tolerance: Consider how much temporary loss or volatility you could realistically tolerate.
Your deadline: If the ₹50 lakh target is non-negotiable, you may need a plan that accounts for the possibility of lower-than-expected returns.
You can use the Kuberzo SIP Calculator to explore how different monthly contributions and return assumptions affect your estimated investment corpus.
2. How Does an SIP Help You Build Wealth Over Five Years?
A Systematic Investment Plan allows you to invest a fixed amount in a mutual fund at regular intervals, usually monthly.
Instead of investing a large sum at once, you spread your contributions over time. This can make investing easier to organise around your monthly income and expenses.
An SIP also helps establish an investment routine. Once you set up the plan, you can contribute regularly without needing to decide how much to invest every month from scratch.
The role of compounding
Compounding occurs when investment gains remain invested and potentially generate further gains over time.
For example, suppose your investments generate positive returns during the first year. If those gains remain invested, subsequent returns may be earned on both your contributions and the accumulated gains.
However, mutual fund returns are not fixed. Unlike a bank deposit with a contractual interest rate, a mutual fund’s value fluctuates with the performance of its underlying investments.
Therefore, compounding can support wealth creation, but it does not guarantee that you will reach a specific target within a fixed period.
The benefit of regular investing
Regular investing can help you avoid the pressure of identifying a supposedly perfect time to enter the market.
When you invest a fixed amount at regular intervals, you purchase more units when the applicable unit price is lower and fewer units when it is higher, assuming the same investment amount.
This is commonly associated with rupee cost averaging. However, it does not eliminate market risk or guarantee a profit.
For a five-year goal, consistency is important, but it must be combined with an investment strategy that reflects your financial circumstances and deadline.
3. What If You Cannot Invest ₹60,000 or More Every Month?
A monthly SIP of approximately ₹61,000–₹68,000 may be difficult to maintain, particularly if you are early in your career or managing several financial responsibilities.
If you cannot afford the required amount today, you have several options. Each involves a trade-off between your monthly contribution, investment period, expected returns and target amount.
Option 1: Increase your investment period
Extending your investment horizon can reduce the monthly amount required to accumulate the same target, all else being equal.
This is because your contributions have more time to accumulate returns, and you can spread the required investment over a larger number of instalments.
For example, you could compare a five-year plan with a seven-year or ten-year plan to see whether a longer timeline fits your budget.
However, a longer period does not guarantee a particular outcome. The result will still depend on actual investment performance.
Option 2: Start with an affordable SIP
You do not necessarily need to begin with your eventual target contribution.
You could start with an amount that fits your current budget and increase it as your income grows. This approach can make regular investing more manageable.
However, if you start substantially below the required amount, you may need to increase your contributions considerably, extend the timeline or revise your target.
It is important to calculate whether your revised plan remains realistic rather than assuming that any SIP will automatically produce ₹50 lakh.
Option 3: Consider a Step-Up SIP
A Step-Up SIP allows you to increase your SIP contribution periodically, usually by a fixed percentage or amount.
This can be useful if you expect your income to rise over time and want your investments to grow alongside it.
For example, you might begin with a smaller monthly contribution and increase it annually as your salary increases.
However, a Step-Up SIP is not a shortcut to a financial target. The amount you eventually need to invest will depend on your starting SIP, annual increases, investment period and actual returns.
You can explore different contribution patterns using the Kuberzo Step-Up SIP Calculator.
4. How Does a Step-Up SIP Work for a ₹50 Lakh Goal?
A Step-Up SIP increases your monthly investment at regular intervals rather than keeping it constant throughout the investment period.
Suppose you begin investing ₹40,000 per month and increase your monthly contribution by 10% every year.
Your monthly SIP would progress as follows:
Investment Year | Monthly SIP |
|---|---|
Year 1 | ₹40,000 |
Year 2 | ₹44,000 |
Year 3 | ₹48,400 |
Year 4 | ₹53,240 |
Year 5 | ₹58,564 |
By the fifth year, your monthly contribution would have increased to ₹58,564.
This approach may be easier to manage if your income grows gradually. Instead of committing to a large monthly SIP immediately, you increase your contribution as your financial capacity improves.
However, the table only illustrates how the monthly contribution changes. It does not establish that this particular Step-Up SIP will accumulate ₹50 lakh in five years. The final corpus must be calculated separately using the starting contribution, step-up rate, investment dates and assumed returns.
Is a Step-Up SIP better than a regular SIP?
Neither approach is automatically better for every investor.
A regular SIP keeps your monthly contribution constant. A Step-Up SIP increases it periodically.
A regular SIP may suit someone whose income and savings capacity are relatively stable. A Step-Up SIP may suit someone who expects their income to increase and can commit to higher contributions in future years.
The right approach depends on your income pattern, financial obligations and ability to sustain the investment.
If you choose a Step-Up SIP, ensure that the planned increases are realistic. An investment plan that becomes unaffordable after two years may not serve your goal effectively.
5. Which Mutual Funds Should You Consider for a Five-Year SIP?
Choosing a mutual fund for a five-year goal requires more than comparing historical returns.
You should consider your investment horizon, tolerance for losses, financial obligations and the importance of the target date.
Different mutual fund categories carry different levels and types of risk.
Equity mutual funds
Equity mutual funds primarily invest in shares of companies.
Their values can fluctuate significantly with market conditions, company performance and economic developments. Although equities may offer opportunities for long-term growth, they can also experience substantial declines.
A five-year investment period does not guarantee that an equity investment will recover from a market downturn before you need the money.
You can learn more about equity mutual funds before considering whether this category suits your circumstances.
Debt mutual funds
Debt mutual funds invest primarily in fixed-income instruments, such as government securities, corporate bonds and money-market instruments, depending on the scheme.
They may have different risk characteristics from equity funds, but they are not risk-free. Their values can be affected by interest-rate changes, credit quality, liquidity conditions and other factors.
Debt funds should not be treated as guaranteed-return investments.
Explore debt mutual funds to understand their general characteristics and potential risks.
Hybrid mutual funds
Hybrid mutual funds invest in a combination of asset classes, commonly including equity and debt.
The allocation between these assets varies across schemes. Consequently, hybrid funds can have different levels of market exposure and risk.
They are not all equally suitable for a five-year goal, and their risk depends on their investment strategy and portfolio composition.
You can explore hybrid mutual funds to understand how these schemes differ.
How should you compare funds?
Before selecting a scheme, review:
Its investment objective and strategy.
The risk level indicated by its Riskometer.
Its asset allocation and portfolio holdings.
Its historical performance across different market conditions.
Its expense ratio and applicable transaction costs.
Its exit load, if applicable.
Whether its investment strategy aligns with your goal and time horizon.
Past performance is not a reliable guarantee of future returns. A fund that performed well over a previous five-year period may not deliver similar results over your next five years.
Instead of choosing a fund solely because it has produced the highest recent return, consider whether its risks are appropriate for the amount you need and the date you need it.
6. Is Five Years Enough to Build ₹50 Lakh Through SIP?
Five years can be a meaningful investment period, but whether it is sufficient to reach ₹50 lakh depends on your contributions and actual investment performance.
A five-year deadline also leaves less time to recover from a market downturn than a much longer investment horizon.
Consider two separate questions:
Can you afford the monthly investment required to target ₹50 lakh?
Can you tolerate the possibility that your investment may be worth less than ₹50 lakh when the five years end?
The first question concerns your savings capacity. The second concerns investment risk.
Both matter.
What if the market falls near the end of the fifth year?
Suppose your investment performs well during the first few years but experiences a market decline shortly before your goal date.
Your portfolio value could fall just when you need to withdraw the money.
This is particularly important if the target is linked to a fixed financial commitment, such as a tuition payment or property purchase.
A SIP does not protect you against such declines. Regular contributions may help spread your purchases across different market conditions, but the underlying investment remains exposed to risk.
If your deadline is inflexible, consider whether relying heavily on volatile investments is appropriate for your circumstances.
You should also review your investment plan as the goal approaches rather than waiting until the final month to assess whether you have accumulated enough.
Should you choose equity, debt or hybrid funds?
There is no universally correct answer for every five-year investor.
The choice depends on your risk tolerance, financial position, investment objective and flexibility around the deadline.
Someone who can postpone a goal may be able to tolerate more uncertainty than someone who must withdraw the entire amount on a fixed date.
Before investing, review the scheme’s Riskometer and understand the possibility of losses. Do not assume that a particular category will deliver a fixed annual return.
7. How Can You Stay on Track to Reach ₹50 Lakh?
A clear investment plan can help you monitor your progress and identify shortfalls early.
Here are five practical steps to consider.
1. Calculate your required monthly contribution
Start by estimating the monthly investment required under several return assumptions.
Do not rely on only one optimistic scenario. Comparing different scenarios helps you understand how sensitive your target is to investment performance.
The monthly SIP figures in this article provide an illustrative starting point.
2. Set a realistic budget
Review your income, fixed expenses, variable expenses, emergency savings and other financial goals.
Your SIP should be sustainable alongside your essential expenses and financial commitments.
Avoid committing to a contribution simply because a calculator indicates that it is required. If you cannot maintain that contribution, revisit the plan.
3. Review your progress periodically
Check whether your contributions are being made as planned and whether your investment remains aligned with your goal.
A review should consider your progress, portfolio allocation, risk exposure and remaining time—not just the latest return.
Frequent changes in response to short-term market movements may not improve your outcome.
4. Reassess your plan when circumstances change
Your financial situation may change because of a salary increase, an unexpected expense, a change in family responsibilities or a revised goal.
If your income rises, you may be able to increase your SIP. If your expenses increase, you may need to adjust your contribution or timeline.
Reassessing your plan is preferable to continuing with an amount that is no longer practical.
5. Prepare for a possible shortfall
A financial plan should account for the possibility that your portfolio does not reach its target on time.
If your projected corpus falls short, you may need to increase contributions, extend the investment period or revise the goal.
Do not assume that higher-risk investments will automatically make up the difference.
If you need help connecting your investment contributions to a specific financial objective, consider the Kuberzo Goal-Based Financial Planner.
8. Should You Aim for Exactly ₹50 Lakh or a Higher Amount?
Before finalising your target, consider whether ₹50 lakh will cover the expense you expect to face in five years.
The cost of many goods and services can rise over time due to inflation. As a result, an amount that appears sufficient today may have lower purchasing power in the future.
For example, if your target is to fund a future education expense or purchase a property, estimate the likely cost when you will actually need the money rather than relying only on today’s price.
This does not mean that you must automatically set a higher target. It means that the target should reflect the future expense as realistically as possible.
You can use the Kuberzo Inflation Calculator to explore how inflation may affect purchasing power over time.
You should also distinguish between your target corpus and the amount you will ultimately have available to spend. Applicable taxes, exit loads and other costs may affect the amount you receive when you redeem your investments.
The treatment will depend on the investment and the rules applicable at the time of redemption. Consider the relevant scheme documents and current tax provisions before making withdrawal decisions.
Final Takeaway
Building ₹50 lakh through SIPs in five years requires careful planning, substantial monthly contributions and a realistic understanding of investment risk.
Under the illustrative assumptions in this article, the required monthly SIP ranges from approximately ₹61,220 to ₹68,050 when annual returns of 8%–12% are assumed.
These figures are useful for planning, but they should not be interpreted as a promise that a particular SIP will produce ₹50 lakh.
Start by assessing how much you can invest consistently, choose investments that match your risk tolerance and deadline, and review your progress periodically. If the required monthly contribution is beyond your current budget, consider adjusting your timeline or using a realistic Step-Up SIP strategy rather than depending on unusually high returns.
Disclaimer: This article is for educational and informational purposes only. Mutual fund investments are subject to market risks, including the possible loss of principal. Illustrative calculations are based on assumptions and do not represent actual or guaranteed returns. Please read all scheme-related documents carefully and consider your financial circumstances and risk tolerance before investing.
Frequently Asked Questions
How much SIP is required for ₹50 lakh in five years?
Under the illustrative assumptions used in this article, the required monthly SIP is approximately ₹68,050 at an assumed annual return of 8%, ₹64,570 at 10%, and ₹61,220 at 12%. These calculations assume monthly contributions at the end of each month over 60 months. Actual mutual fund returns are not fixed, so the final corpus may differ.
Can I build ₹50 lakh in five years with a ₹25,000 monthly SIP?
A ₹25,000 monthly SIP is substantially below the estimated monthly contributions shown in this article. Whether you can accumulate ₹50 lakh depends on actual investment returns, any increase in contributions, additional investments and the time available. You should calculate the expected corpus using realistic assumptions rather than relying on an unusually high return to bridge the gap.
Is a 12% return guaranteed on an SIP?
No. A 12% return is an assumption used for an illustrative calculation, not a guaranteed return from a mutual fund.
Is a Step-Up SIP suitable for a five-year goal?
A Step-Up SIP may suit investors who expect their income to increase and can raise their contributions periodically. However, increasing your SIP does not guarantee that you will reach ₹50 lakh. The outcome depends on your starting contribution, step-up rate, investment period and actual returns.
Which mutual fund is best for a five-year SIP?
There is no single mutual fund that is best for every investor. Your choice should reflect your financial goal, risk tolerance, investment horizon and the possibility of market losses. Review the scheme’s investment objective, portfolio, Riskometer, costs and other relevant details before investing. Past performance does not guarantee future results.
Is an SIP safer than investing a lump sum?
n SIP spreads investments across regular instalments, while a lump-sum investment places the amount into the market at one time. An SIP may reduce the need to time a single entry point, but it does not eliminate market risk or guarantee profits. The suitability of either approach depends on your circumstances and investment objective.
What should I do if I cannot invest the required amount every month?
You could consider extending your investment horizon, starting with an affordable contribution and increasing it as your income grows, or revising your target. The right choice depends on your financial capacity and deadline. Avoid taking excessive investment risk simply to compensate for a contribution shortfall.
What happens if my SIP does not reach ₹50 lakh after five years?
If your investments fall short of the target, you may need to extend the investment period, contribute additional money or revise the goal. The best response depends on why the shortfall occurred and whether you can postpone the expense. Review your options before making rushed investment decisions.




