
Flexi Cap vs Multi Cap: Which Could a 30-Year-Old Choose for a ₹1 Crore Goal?
By Divay Diya
About the Author
Divay Diya is a business and digital marketing enthusiast with expertise in market research, SEO, and strategic planning. She explores business growth, marketing, investing, and financial markets, translating research into actionable insights.
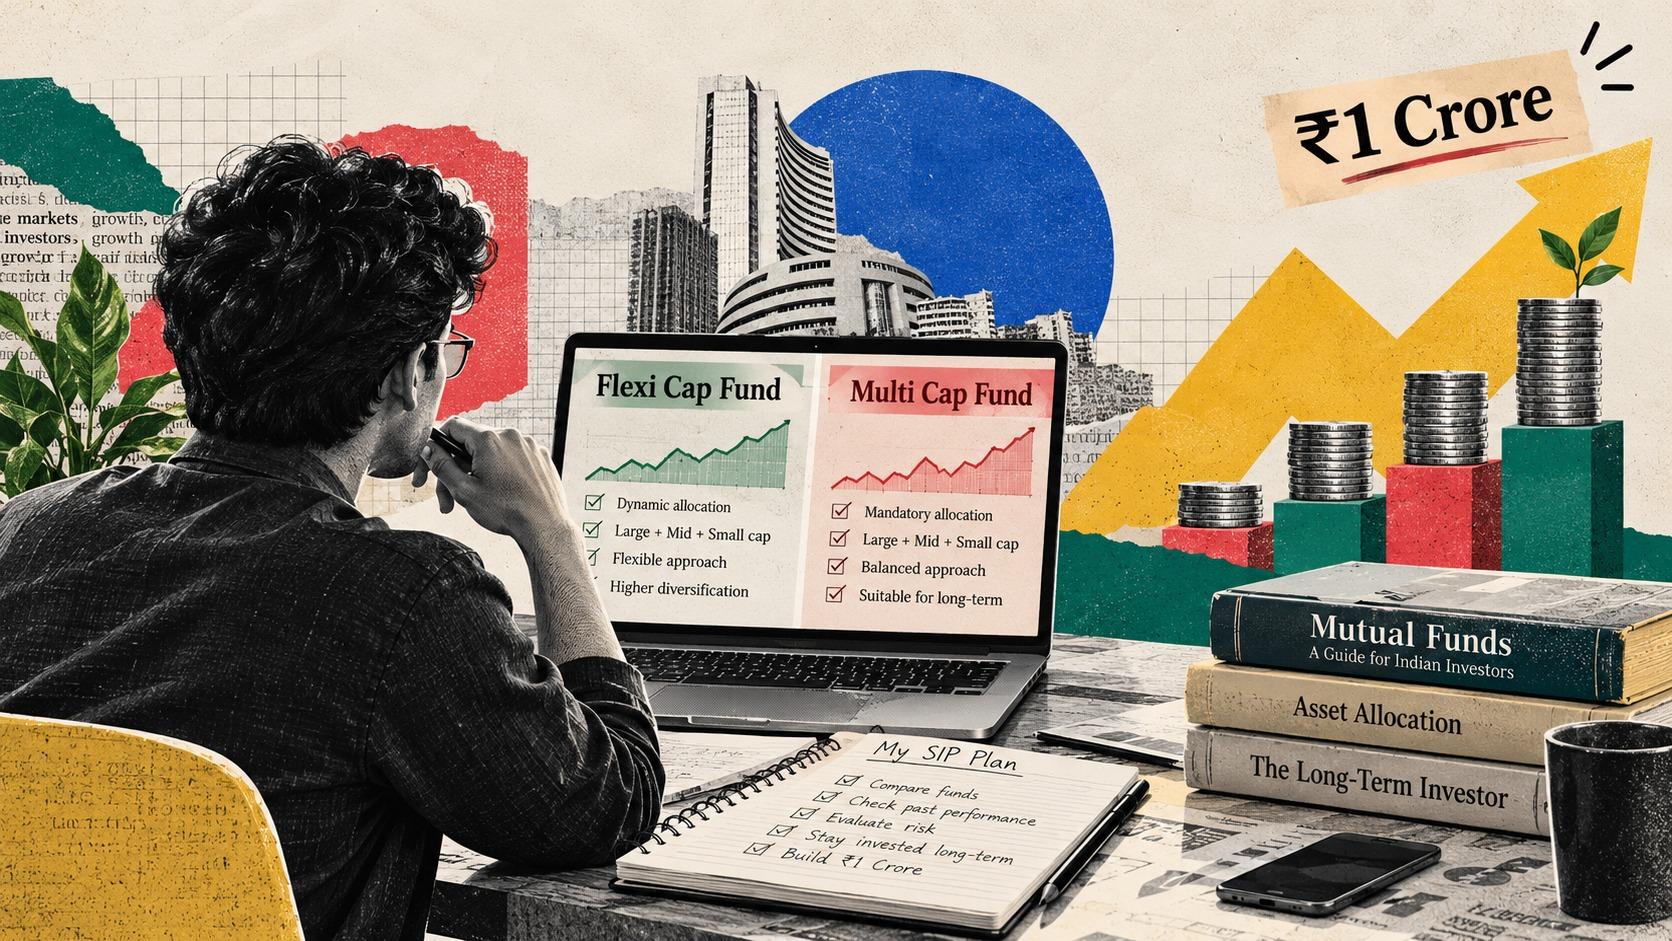
Two investors can have the same ₹1 crore goal but need very different investment strategies. A flexi cap fund gives the fund manager greater freedom to move across market-cap segments, while a multi cap fund follows defined allocation requirements. So, which approach makes more sense for a 30-year-old investing for the long term? Explore the differences, understand the risks, and see how your SIP strategy could shape your journey towards ₹1 crore.
At 30, building a ₹1 crore investment portfolio can feel achievable, but deciding where to invest can be confusing. Two equity mutual fund categories that often appear similar are flexi cap and multi cap funds. Both invest across large-cap, mid-cap and small-cap companies, yet they follow different allocation rules.
The key difference is flexibility. A flexi cap fund gives the fund manager greater freedom to adjust allocations across market-cap segments, while a multi cap fund must maintain prescribed minimum exposure to each. For someone planning a ₹1 crore investment goal, understanding this distinction can help make fund selection more deliberate.
1. What Is a Flexi Cap Fund?
A flexi cap fund is an open-ended equity scheme that invests across large-cap, mid-cap and small-cap stocks. Under SEBI’s categorisation framework, it must invest at least 65% of its total assets in equity and equity-related instruments. Unlike a multi cap fund, it has no category-mandated minimum allocation to each of the three market-cap segments.
This gives the fund manager room to adjust allocations according to the scheme’s strategy, valuations and assessment of market opportunities. For example, a manager may favour large-cap companies during uncertain markets and increase exposure to mid-cap or small-cap stocks when the investment strategy supports doing so.
That flexibility can be useful, but it does not guarantee better returns. Results depend on the manager’s decisions, stock selection and market conditions. A flexi cap fund may also have substantial exposure to one segment for a period, so investors should examine its actual portfolio rather than assume that exposure is always evenly distributed.
2. What Is a Multi Cap Fund?
A multi cap fund must invest at least 75% of its total assets in equity and equity-related instruments, with at least 25% of total assets allocated to each of the large-cap, mid-cap and small-cap segments under SEBI’s categorisation framework.
This structure ensures exposure to all three segments. The fund manager cannot freely move the portfolio into only large-cap companies because the scheme must maintain the prescribed minimum allocations. This creates a more defined allocation structure, but it also means that exposure to mid-cap and small-cap stocks remains even when those segments face difficult market conditions.
Multi cap funds are not automatically more diversified or more rewarding in every market. Their results depend on the specific stocks held, portfolio construction, costs and market performance. The category rules define minimum allocations; they do not predict returns.
3. Flexi Cap vs Multi Cap: Key Differences
Basis of comparison | Flexi cap fund | Multi cap fund |
|---|---|---|
Minimum equity exposure | 65% of total assets | 75% of total assets |
Large-cap allocation | No category-mandated minimum | At least 25% of total assets |
Mid-cap allocation | No category-mandated minimum | At least 25% of total assets |
Small-cap allocation | No category-mandated minimum | At least 25% of total assets |
Allocation approach | Greater flexibility across market-cap segments | Prescribed minimum exposure across all three segments |
Main consideration | Manager’s allocation and stock-selection decisions | Mandatory exposure to mid-cap and small-cap stocks |
These are category-level characteristics, not descriptions of every scheme’s current portfolio. Check the latest scheme documents and portfolio disclosures before investing.
4. Which Could Suit a 30-Year-Old?
Age alone does not determine which category is right. Your investment horizon, risk tolerance, existing investments and preference for flexibility matter more.
A flexi cap fund may suit an investor who prefers the fund manager to have greater freedom to adjust market-cap exposure. However, allocations can change, and the fund may underperform its benchmark or peers.
A multi cap fund may suit someone who prefers defined minimum exposure to large-, mid- and small-cap companies. The trade-off is that the scheme must retain minimum exposure to mid-cap and small-cap stocks even when they are struggling. These segments can be volatile, and losses can be substantial during market corrections.
Neither category is automatically safer. A flexi cap manager’s flexibility does not guarantee downside protection, and a multi cap fund’s exposure to three segments does not eliminate equity risk.
The more useful question is whether the structure matches how you want your long-term portfolio to behave.
5. How Much SIP Could Build ₹1 Crore?
Suppose you are 30 and want to accumulate ₹1 crore by age 50. That gives you 20 years to invest. The following table estimates the monthly SIP required under three assumed annual returns.
Assumed annual return | Approximate monthly SIP | Investment period |
|---|---|---|
8% | ₹16,900 | 20 years |
10% | ₹13,200 | 20 years |
12% | ₹10,100 | 20 years |
Illustrative estimates assume end-of-month contributions and a constant monthly rate derived from the assumed annual return. Figures are rounded. Actual mutual fund returns fluctuate, and the final value may differ substantially.
The table is a planning tool, not a forecast for either category. Do not choose a flexi cap or multi cap fund because you expect it to deliver a particular return. Instead, choose a realistic contribution, keep emergency savings separate and review your goal as your income and circumstances change.
Use Kuberzo’s SIP Calculator to test different contribution amounts and timelines.
6. Comparing Flexi Cap Fund Returns and Multi Cap Fund Returns
Investors naturally want to know which category has delivered stronger returns. There is no permanent winner. Performance depends on the measurement period, portfolio allocation, stock selection, expenses and the market environment.
When large-cap stocks outperform smaller companies, a flexi cap fund with greater large-cap exposure may benefit relative to a multi cap fund that must retain minimum mid-cap and small-cap allocations. When mid-cap and small-cap stocks outperform, a multi cap fund’s required exposure to those segments may help it relative to a flexi cap fund with less exposure.
When comparing flexi cap fund returns with multi cap fund returns, consider these factors:
Compare similar periods: Review several time horizons instead of relying only on one-year returns.
Use appropriate benchmarks: Assess each scheme against its relevant benchmark.
Review downside behaviour: Examine performance during market corrections, not only during rallies.
Understand portfolio allocation: Market-cap exposure can help explain performance differences.
Compare expenses: Costs affect the returns investors ultimately receive.
Look for consistency: One strong period does not establish that a fund will continue to outperform.
Past performance provides context but cannot guarantee future results. A category comparison is useful, but the individual fund’s portfolio, strategy and execution matter too.
7. Should You Invest in Both Categories?
You can hold both flexi cap and multi cap funds, but doing so does not automatically improve diversification. Both categories may own many of the same companies, particularly among large-cap stocks. Multiple fund names can create the appearance of variety without making a portfolio meaningfully different.
Before investing in both, compare their current holdings, market-cap exposure and stated strategies. Ask what each fund adds to your portfolio. If their holdings and exposures overlap substantially, one well-chosen fund may already serve the intended purpose. In other situations, using both may fit a broader investment strategy.
Your decision should reflect your entire portfolio, not simply the number of schemes you own. Keep near-term expenses and emergency savings separate from money committed to volatile equity investments.
Kuberzo’s Portfolio Review can be a useful starting point for assessing how your investments fit together.
8. Common Mistakes to Avoid
Choosing only by recent returns: A recent top performer may not remain one. Review performance over different periods and compare schemes against relevant benchmarks.
Assuming flexibility means safety: A flexi cap fund can still hold concentrated positions or experience steep declines. Flexibility is an allocation feature, not a guarantee of protection.
Underestimating mid-cap and small-cap volatility: Multi cap funds must maintain exposure to these segments. Understand how this may affect returns during market stress.
Ignoring your time horizon: Equity funds are generally better suited to long-term goals than money you may need soon. If the goal is approaching, reassess how much risk is appropriate.
Switching too frequently: Moving funds whenever rankings change can disrupt your strategy and may create transaction costs or tax consequences. Review investments periodically rather than reacting to every headline.
Overlooking your wider financial situation: Your debt, emergency savings, income stability and other goals should influence how much equity risk you take.
9. A Practical Way to Decide
Start by writing down your target amount and the date by which you want to reach it. Work out a monthly contribution using different return assumptions, remembering that none is guaranteed. Then decide whether you prefer the flexibility of a flexi cap fund or the defined minimum allocation structure of a multi cap fund.
Compare individual schemes based on their investment objectives, portfolios, benchmark performance, expenses and risks. Check overlap with your existing investments and understand how the fund may behave during a downturn. Choose an SIP you can sustain and increase it when your income allows.
Review your plan at sensible intervals. A market fall alone does not mean your strategy has failed, but changes in your finances, goals or ability to tolerate risk may justify reassessment. Avoid choosing a scheme solely because it currently ranks first.
Key Takeaway
For a 30-year-old targeting ₹1 crore, both flexi cap and multi cap funds can be considered for long-term equity investing, but they offer different portfolio structures. Flexi cap funds give managers greater freedom to change allocations across market-cap segments, while multi cap funds must maintain at least 25% exposure to each of the large-cap, mid-cap and small-cap segments.
Neither category guarantees better returns. Your decision should depend on your risk tolerance, investment horizon, existing portfolio and comfort with each structure. Set a realistic SIP, compare individual schemes carefully and focus on consistency rather than chasing recent winners.
Disclaimer: This article is for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any mutual fund. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully and consider your financial circumstances before investing.
Frequently Asked Questions
Is a flexi cap fund better than a multi cap fund?
Neither is universally better. The right choice depends on your preferences, risk tolerance, investment horizon and the specific scheme’s strategy.
Do flexi cap funds deliver higher returns?
Not consistently. Returns vary by scheme, period, market-cap allocation, stock selection and market conditions. Past performance does not guarantee future returns.
Can I use an SIP in either category?
Yes. SIPs allow regular investments in eligible flexi cap and multi cap schemes. Select a contribution that fits your budget and long-term plan.
Can I invest in both categories?
Yes, but review portfolio overlap first. Holding both does not automatically improve diversification.




