
Direct vs Regular Mutual Fund: Meaning, Differences & Commission
By Amrita Sinha
About the Author
Amrita Sinha is a content strategist with experience in SEO, digital marketing, and financial content. She writes easy-to-understand, research-backed articles on investing, personal finance, taxation, and wealth management for Kuberzo.
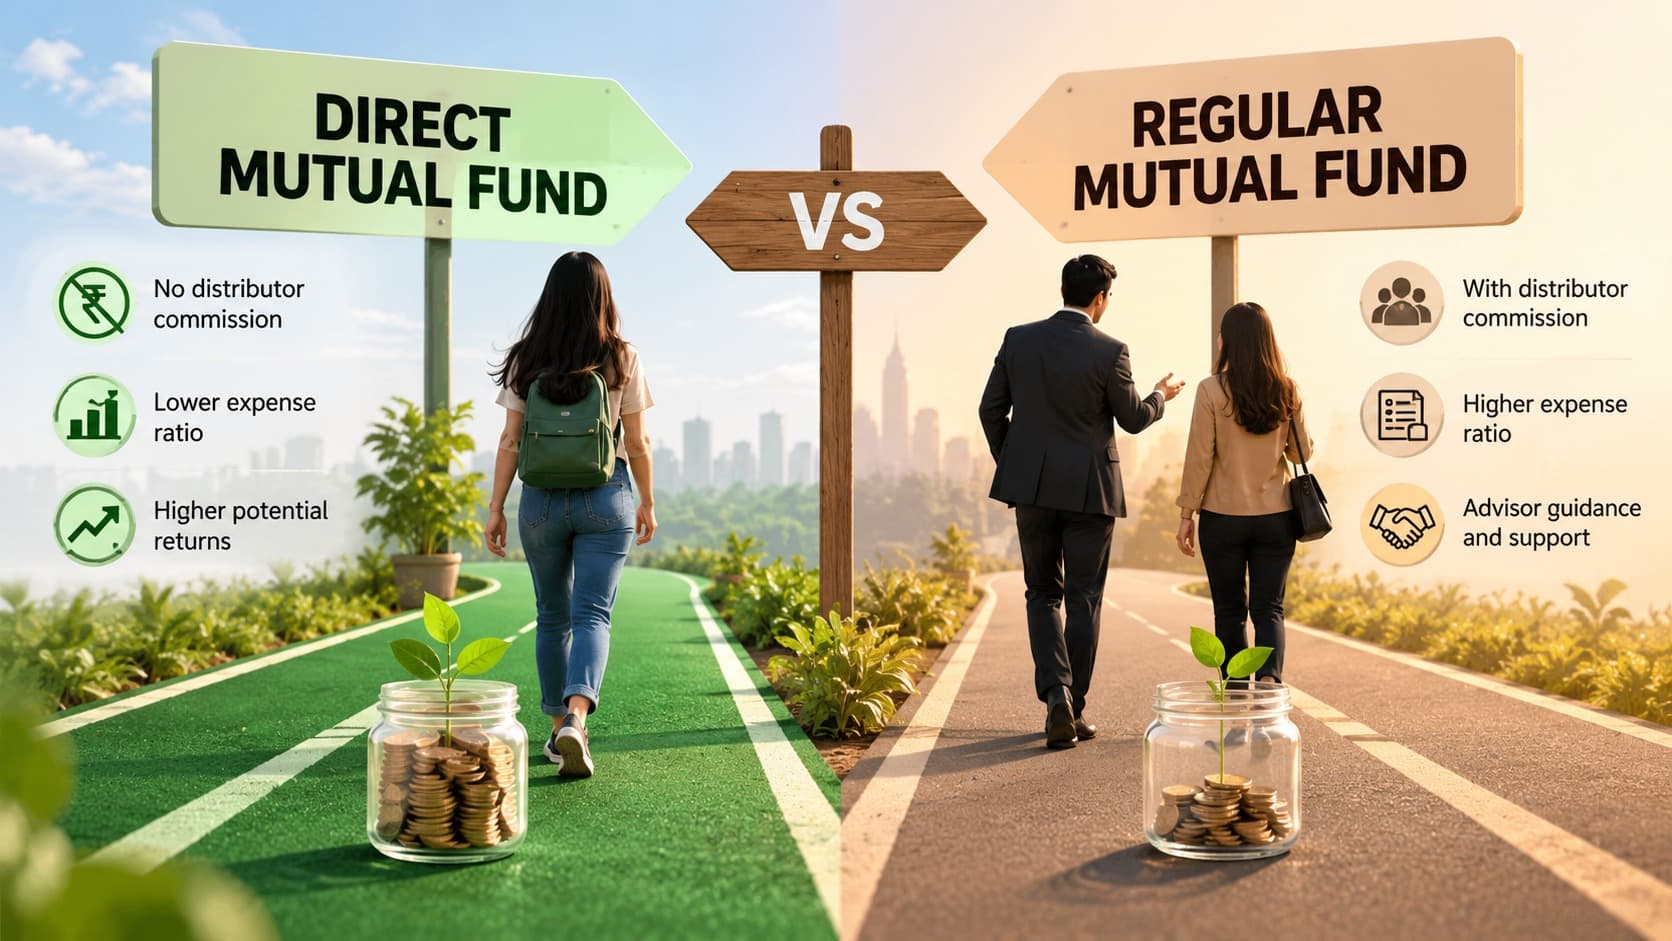
Understand direct vs regular mutual funds, expense ratios, distributor commissions, return differences, and how to switch from regular to direct plans.
When investing in mutual funds, you may come across two options for the same scheme: Direct Plan and Regular Plan. Both invest in the same underlying portfolio, follow the same investment objective and are managed by the same fund manager. Yet, their expense ratios and returns can differ.
Why does this happen?
The main reason is the cost of distribution. Regular plans include distribution-related expenses, such as commissions paid to mutual fund distributors, while Direct plans do not include distributor commissions. This difference can affect the returns investors receive over time.
Understanding the direct vs regular mutual fund difference can help you make a more informed investment decision. However, choosing between the two is not just about selecting the option with the lower expense ratio. You should also consider how comfortable you are researching, selecting and monitoring investments independently.
In this guide, we explain both plans, compare their costs and benefits, and discuss what investors should know before switching plans.
What Is a Direct Plan in a Mutual Fund?
A Direct Plan in a mutual fund allows investors to invest in a scheme without routing their investment through a mutual fund distributor.
You can generally invest through the asset management company's (AMC's) website or other permitted direct investment channels. Direct plans are designed for investors who prefer to research and manage their mutual fund investments themselves.
The most important feature of a Direct Plan is its lower expense ratio compared with the corresponding Regular Plan of the same scheme. This is because distributor commissions and related distribution costs are not included in the Direct Plan's expenses.
For example, if you invest in a Direct Plan of an equity mutual fund, your money is invested in the same underlying portfolio as the corresponding Regular Plan. The fund manager does not run a separate portfolio just for Direct Plan investors.
However, a Direct Plan does not automatically mean that the investment is suitable for you. You still need to assess the fund's objective, risk level, portfolio, performance and suitability for your financial goals.
Regular Mutual Fund Meaning
The regular mutual fund meaning is straightforward: it is a mutual fund plan purchased through an intermediary, such as a mutual fund distributor.
A distributor may help investors understand available schemes, complete the investment process and provide ongoing assistance, depending on the services offered.
The Regular Plan has a higher expense ratio than its corresponding Direct Plan because distribution-related costs, including applicable distributor commissions, are included in the scheme's expenses.
This does not mean that Regular Plans have a different investment strategy. The portfolio, investment objective and fund manager remain the same as those of the corresponding Direct Plan.
Regular Plans may be useful for investors who value assistance with the investment process. However, investors should understand the costs involved and the nature of the services provided before choosing one.
Direct vs Regular Mutual Fund: Key Differences
Here is a comparison of the two plans.
Feature | Direct Plan | Regular Plan |
Investment route | Directly through the AMC or an eligible direct channel | Through a mutual fund distributor |
Underlying portfolio | Same as the corresponding Regular Plan | Same as the corresponding Direct Plan |
Fund manager | Same | Same |
Expense ratio | Generally lower | Generally higher |
Distributor commission | No distributor commission is charged under the Direct Plan | Applicable distribution commission is included in scheme expenses |
Historical returns | Generally higher for the same scheme and option over comparable periods, due to lower expenses | Generally lower for the same scheme and option over comparable periods, due to higher expenses |
Investor support | Investor generally manages research and decisions independently | Distributor support may be available, depending on the service |
Best suited for | Investors comfortable making their own investment decisions | Investors who value distributor assistance |
Neither plan guarantees better investment performance. Market movements, portfolio decisions and investment risks affect both plans because they share the same underlying portfolio. The key difference is the cost structure and the support available through the distribution channel.
Distributor Commission in Mutual Funds: How Does It Work?
Distributor commission in mutual funds is compensation paid for distributing mutual fund schemes. In a Regular Plan, applicable distribution costs are included in the scheme's expense structure and are reflected in its expense ratio.
Investors generally do not pay this commission as a separate bill each time they make an SIP instalment. Instead, the cost forms part of the expenses charged to the scheme, which affects its NAV over time.
Direct Plans do not include distributor commissions. Consequently, their expense ratios are generally lower than those of the corresponding Regular Plans.
It is important to understand that distributor commission is not the only cost associated with running a mutual fund. The expense ratio can also include other permitted scheme expenses, such as investment management and administrative costs, subject to applicable regulations.
Before investing, check the latest expense ratio for the specific scheme and plan. Costs can change, so do not rely on an old comparison or assume that every fund has the same difference between its Direct and Regular Plans.
Return Difference Between Direct and Regular Mutual Funds
The return difference between Direct and Regular plans mainly arises from their different expense ratios.
Since the Direct Plan generally has lower recurring expenses, more of the scheme's investment gains remain available to contribute to its NAV, all else being equal. Over long periods, this difference can compound.
Example: How Costs Can Affect Long-Term Returns
Suppose you invest ₹1,00,000 in two plans of the same mutual fund. For illustration, assume the underlying portfolio generates a 10% annual return before plan-level expenses.
Direct Plan expense ratio: 0.50% per year
Regular Plan expense ratio: 1.00% per year
For a simplified illustration, assume the resulting annual returns are approximately 9.50% for the Direct Plan and 9.00% for the Regular Plan.
Investment Period | Direct Plan at 9.50% | Regular Plan at 9.00% |
Initial investment | ₹1,00,000 | ₹1,00,000 |
After 5 years | Approximately ₹1,57,400 | Approximately ₹1,53,900 |
After 10 years | Approximately ₹2,48,600 | Approximately ₹2,36,700 |
These figures are illustrative estimates, not actual or projected mutual fund returns. They assume constant annual returns after the stated expense differences and do not account for taxes, transaction-related costs or market fluctuations.
The example shows how even a relatively small difference in annual expenses can affect the final investment value over time. Actual outcomes depend on the scheme's changing expense ratio, market performance and other factors.
Difference Between Direct and Regular SIP
The difference between Direct and Regular SIP is the same basic cost difference that applies to lump-sum investments.
A Systematic Investment Plan (SIP) is a method of investing a fixed amount at regular intervals. It is not a separate type of mutual fund plan. You can set up an SIP in either the Direct or Regular Plan of an eligible scheme.
For example, if you invest ₹5,000 per month in a Direct Plan, your instalments purchase units of that plan. If you invest ₹5,000 per month in the corresponding Regular Plan, the instalments purchase units of the Regular Plan.
Both SIPs invest in the same underlying portfolio, but the expense ratios differ. Over time, this cost difference may affect the value of your accumulated investment.
When comparing SIPs, make sure you compare the same scheme, investment option, dates and contribution amounts. Do not assume that a Direct SIP is inherently less risky or that it guarantees higher returns.
Regular Plan Advisory Benefits: Is the Extra Cost Worth It?
The regular plan advisory benefits can be relevant for investors who prefer assistance with selecting and maintaining investments.
Before selecting a plan, assess your investment risk profile to understand the level of market risk that may suit your financial situation.
Depending on the distributor and the services agreed upon, support may include:
Help understanding available mutual fund schemes.
Assistance with the investment and transaction process.
Support with paperwork and account-related queries.
General guidance on maintaining investment discipline.
Help reviewing investments or navigating market volatility, where offered.
However, the quality and scope of support can vary. Not every distributor offers comprehensive financial planning or personalised investment advice. Investors should clarify the services provided, the distributor's registration status and how the distributor is compensated.
A Regular Plan may be appropriate if you value this assistance and believe it supports better investment decisions. A Direct Plan may be more suitable if you can confidently research schemes, assess risks and manage your portfolio independently.
The decision should account for both cost and the value of the support you actually receive.
How to Identify Direct vs Regular Fund
If you are unsure which plan you currently hold, there are a few ways to check.
1. Review your mutual fund statement
Look for the scheme name and plan details. The plan may be labelled “Direct” or “Regular” in your account statement or transaction confirmation.
2. Check the AMC's website or app
Log in to the official platform and review your investment details. The plan type and applicable scheme information may be displayed there.
3. Review the expense ratio
Direct Plans generally have a lower expense ratio than their corresponding Regular Plans. However, do not use the expense ratio alone to identify a plan. Verify the plan name in the official records.
4. Check your transaction route
If you invested through a mutual fund distributor, you may hold a Regular Plan. If you invested directly through the AMC's permitted direct channel, you may hold a Direct Plan. Always confirm using the actual scheme records.
Switching From Regular to Direct: What Should You Know?
Investors sometimes consider switching from Regular to Direct to reduce recurring costs. Before making the change, understand that a switch is generally processed as a redemption from one plan and a purchase into another, rather than simply changing a label.
Depending on the scheme, the applicable holding period and your circumstances, the switch may have tax implications and could attract an exit load. The details depend on the transaction and the scheme's rules.
Before switching:
Check the current expense ratios of both plans.
Review the scheme's exit load conditions.
Understand the potential capital gains tax implications.
Confirm the process and timing with the AMC or your investment platform.
Consider whether you are comfortable managing the investment without distributor support.
A mutual fund portfolio review can help you evaluate your existing investments, recurring costs and whether your portfolio remains aligned with your goals.
You do not necessarily need to switch immediately just because the Direct Plan has a lower expense ratio. First evaluate any one-time costs and the services you may lose, then compare them with the potential long-term cost savings.
Conclusion
The choice between Direct and Regular mutual fund plans comes down to cost, support and how confidently you can manage your investments.
Direct Plans generally have lower expense ratios because they do not include distributor commissions. Regular Plans have higher expenses but may provide access to distributor assistance, depending on the services offered.
Both plans share the same underlying portfolio and fund manager, so the main distinction is not the investment strategy but the cost structure and distribution route.
Before choosing a plan, compare expense ratios, understand the available support and consider your investment knowledge and financial goals. If you are considering switching, check exit loads and tax implications first.
The right plan is the one that helps you invest appropriately, understand the costs and stay aligned with your long-term financial objectives.
Frequently Asked Questions
What is the difference between Direct and Regular mutual funds?
Both plans invest in the same underlying portfolio and have the same fund manager. Direct Plans generally have lower expense ratios because they do not include distributor commissions, while Regular Plans are purchased through distributors and include applicable distribution costs.
Are Direct mutual funds always better than Regular mutual funds?
Not necessarily. Direct Plans generally have lower costs, but investors need to research and manage their investments independently. A Regular Plan may be suitable for someone who values distributor assistance and understands the cost involved.
How much commission do mutual fund distributors earn?
Commission varies depending on the scheme, plan, distribution arrangement and applicable rules. It is generally included in the expense structure of Regular Plans rather than being billed separately to each investor. Check the latest scheme disclosures for relevant information.
Can I switch from a Regular Plan to a Direct Plan?
Yes, subject to the AMC's process and applicable scheme rules. The transaction is generally treated as a redemption and a fresh purchase, so exit load and capital gains tax may apply. Verify the implications before switching.




