
Buying Your Dream Home: How to Build a Down Payment with SIPs
By Saahil Madhogaria
About the Author
Saahil Madhogaria is an MBA student at SOIL Institute of Management with a background in Game Art & Animation and experience as a 3D Artist. He writes about marketing, business, personal finance, careers, and MBA life.
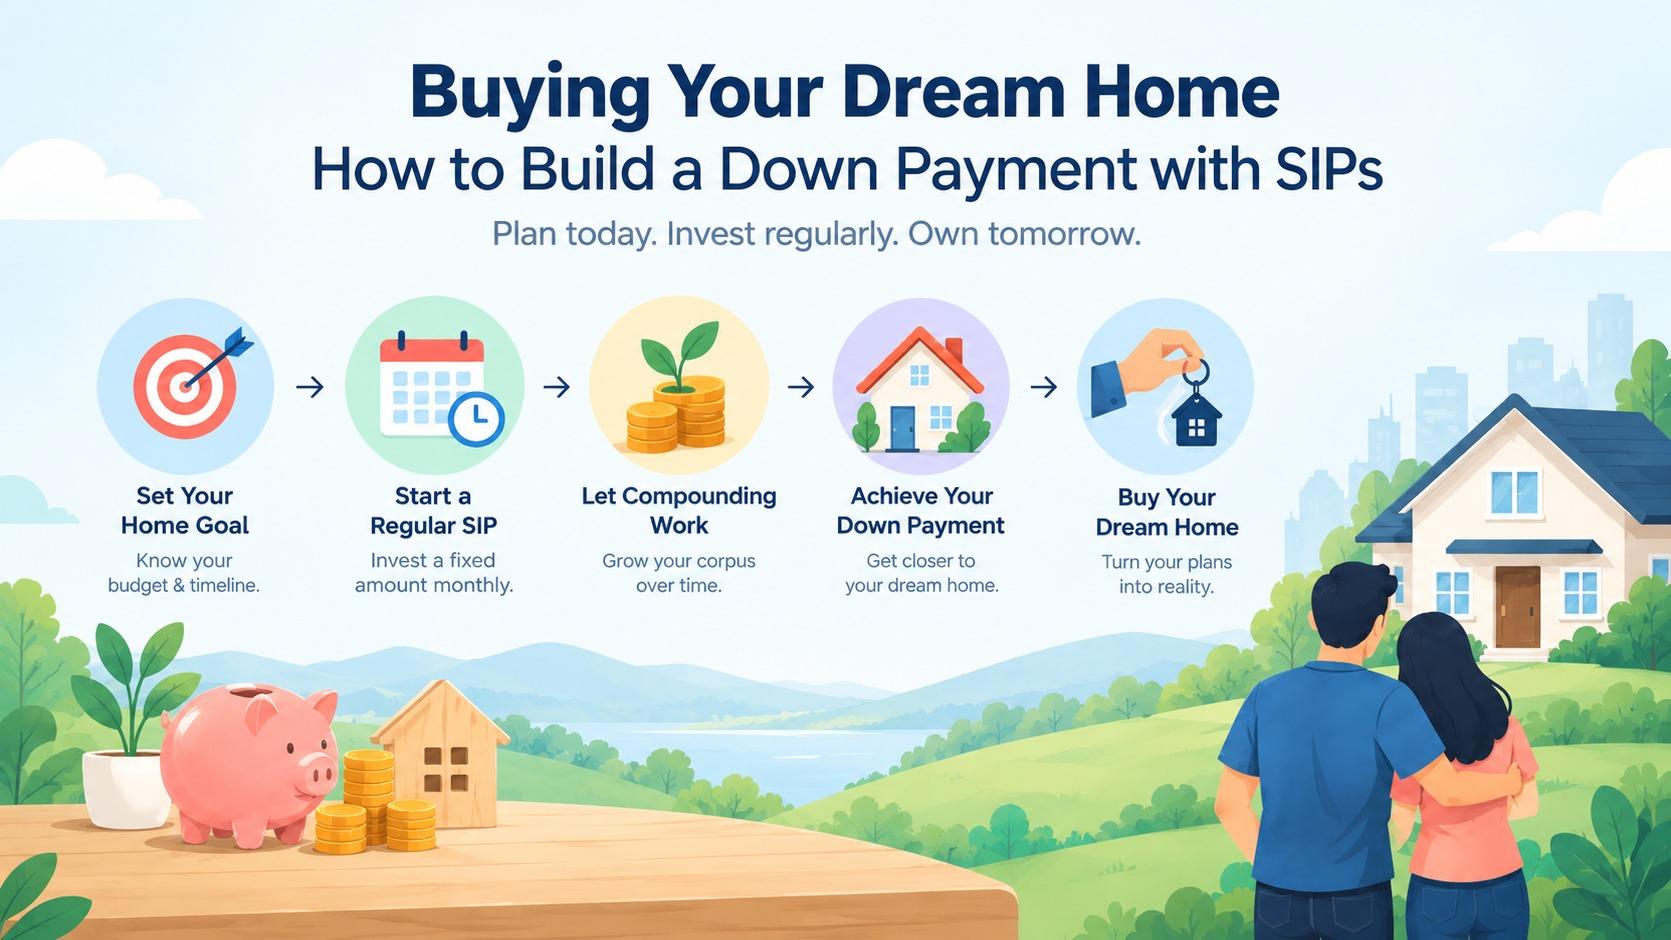
Save for your dream home’s down payment by investing a fixed amount each month. Learn how to estimate what you'll need, set a clear timeline, and switch to safer options as you get closer to buying.
Buying Your Dream Home: How to Build a Down Payment with SIPs
Buying a home is one of the biggest financial goals for many Indian households. But the first challenge is often not the home loan EMI. It is building enough money for the down payment and other upfront costs.
A systematic investment plan (SIP) can be one way to build this corpus over time. Instead of waiting until you have a large amount of money, you invest a fixed amount periodically into a mutual fund scheme.
However, buying a house through SIP does not mean that the SIP pays for the property. The SIP helps you build an investment corpus that can later be used towards the purchase.
Here is how to approach a home down payment SIP strategy.
Step 1: Set your home-buying goal
Start with the home you want to buy, rather than the SIP amount.
Suppose you are considering a property that costs ₹80 lakh today. You may need to arrange a portion of the purchase price from your own resources, while the remaining amount may be financed through a home loan, subject to the lender's assessment and applicable rules.
The actual upfront requirement can also include expenses such as registration, stamp duty, brokerage, interiors and other transaction costs.
Your first calculation should therefore be:
Expected home price + purchase-related costs − available savings = amount you need to build
SEBI recommends making financial goals specific, measurable and time-bound and then aligning investments with the goal and investment horizon.
Step 2: Decide when you want to buy
Your timeline is just as important as your target amount.
If you want to buy a home after 10 years, you have more time to build the required corpus than someone planning to purchase in three years.
This matters because mutual funds can fluctuate in value. SEBI advises investors to match investments with their time horizon and risk tolerance, noting that short-term goals generally call for avoiding highly volatile investments.
Therefore, a SIP for a home purchase five or ten years away should not automatically follow the same strategy as money required next year.
Step 3: Calculate your down-payment target
Suppose your target is to accumulate ₹20 lakh for the down payment and related upfront requirements.
You now have two variables:
Target corpus = ₹20 lakh
Investment period = 7 years
A SIP calculator for a home loan or home purchase can then help estimate the monthly amount required using an assumed rate of return.
The result is an illustration, not a promise.
For example, if a calculator assumes a particular annual return, changing that assumption will change the SIP requirement. Actual mutual fund returns can be higher or lower because they are market-linked.
Step 4: Choose investments according to your timeline
There is no universally best mutual fund for house purchase.
The investment category should depend on how far away your home purchase is and how much volatility you can accept.
For a longer-term goal, some investors may consider equity-oriented mutual funds because they have higher growth potential but also higher volatility.
For a shorter-term goal, investors may prefer less volatile options depending on their risk profile and specific requirements.
SEBI advises investors to consider financial goals, investment horizon, risk appetite, diversification and asset allocation before investing. It also states that investors should avoid risky investments such as equity for short-term requirements.
The closer you get to your home purchase, the more important capital preservation and liquidity become.
Step 5: Increase your SIP as your income grows
A fixed SIP may not keep pace with a rising home price or increasing income.
Consider increasing your SIP periodically when your salary or business income increases.
For example:
Starting SIP: ₹20,000 per month
Income increases: Increase the SIP
Repeat periodically: Build the corpus faster
This approach can make goal-based saving for a home more flexible.
However, do not increase the SIP at the cost of an emergency fund, insurance premiums, essential expenses or other important financial goals.
Step 6: Understand SIP vs EMI for a home
SIP and EMI serve completely different purposes.
SIP: Helps you invest regularly and potentially build a future corpus.
EMI: Repays the principal and interest on a home loan after borrowing.
Therefore, SIP vs EMI for home is not really an either-or decision.
Before buying, you may use a SIP to build the down payment. After taking a home loan, you may have an EMI to repay the borrowing.
For example:
Before purchase → SIP → Build down payment
After purchase → Home loan → EMI
The two can exist at different stages of the same home-buying journey.
Kuberzo's guide to different types of mutual funds can help investors understand how equity, debt, hybrid and passive categories differ.
Step 7: Start reducing risk as the purchase approaches
This is one of the most important parts of a home-buying SIP strategy.
Imagine that you have accumulated ₹18 lakh after years of investing and plan to purchase your home in six months. A sharp market decline at that point could reduce the value of your corpus.
This is why an investor should not simply continue taking the same level of market risk until the day the money is required.
As the goal approaches, review the portfolio and consider whether the asset allocation still matches the shorter time horizon and the importance of the goal.
SEBI notes that investments should be matched to the investment horizon and risk tolerance and that portfolios should be periodically reviewed and rebalanced when required.
SIP vs real estate: understand the difference
Real estate and mutual fund SIPs serve different purposes.
Buying a property gives you an actual physical asset and may also provide housing utility. A mutual fund SIP gives you exposure to financial-market investments without directly owning a property.
Therefore, real estate vs mutual fund SIP should not be treated as a simple “which is better?” comparison.
For someone saving for a future house, the relevant question is:
“What investment approach is appropriate for the money I need and the date on which I need it?”
The answer depends on the investor's financial goal, time horizon, liquidity needs and risk tolerance.
Kuberzo's SIP Calculator can help investors model different monthly contribution scenarios.
What about taxes?
Tax should be considered when calculating the amount available for the down payment.
The tax treatment of mutual fund gains depends on factors such as the type of mutual fund, holding period and applicable tax rules.
For equity-oriented funds, current tax provisions include a 12.5% long-term capital-gains rate for specified transactions under Section 112A, subject to the applicable conditions and exemptions.
Therefore, do not assume that your portfolio's displayed value will necessarily equal the amount available for your home purchase after taxes.
Common mistakes to avoid
Starting without a target: Decide the approximate property value, timeline and corpus requirement first.
Ignoring property-price inflation: Today's home price may not be the price when you are ready to buy.
Using aggressive return assumptions: A higher assumed return can make the required SIP look smaller than it may actually need to be.
Taking excessive risk close to purchase: A short-term market fall can affect a corpus that is about to be used.
Forgetting additional costs: The down payment may not be the only upfront expense.
Stopping the SIP without a replacement plan: If your goal changes, review the investment plan rather than simply abandoning it.
Contact us for a more personalised guidance.
The bottom line
Building a home down payment through SIPs is essentially a goal-based investing exercise.
Start by deciding what you want to buy and when you want to buy it. Estimate the future amount required, calculate the SIP needed and choose investments according to your time horizon and risk tolerance.
As the purchase date approaches, review the portfolio and gradually reassess the amount of market risk you are taking.
A SIP can help create investing discipline, but it cannot guarantee that you will accumulate a particular amount. Mutual fund investments are subject to market risks, and actual returns can differ from the assumptions used in a calculator.
Illustrative examples are for educational purposes only. Mutual fund investments are subject to market risks. This article does not constitute personalized investment, tax or home-loan advice. Consider your financial circumstances and consult a SEBI-registered investment adviser where appropriate.
Frequently Asked Questions
How is a home down payment target calculated?
Start with the estimated future property price and add upfront expenses—including stamp duty, registration charges, brokerage, and interior furnishing—then subtract your existing savings. Because lenders typically finance only 75% to 80% of a property's value, your target corpus must cover both the remaining down payment and all out-of-pocket transaction costs.
What is the difference between an SIP and a home loan EMI?
An SIP and an EMI serve opposite financial purposes at different stages of homeownership. An SIP is a wealth-building method used before purchasing a home to accumulate the required down payment. An EMI is a mandatory debt repayment used after buying the home to pay off the lender's principal and interest.
How should I choose mutual funds based on my purchase timeline?
Fund selection should align with your investment horizon and risk tolerance. For long-term goals (typically 7 to 10 years away), equity-oriented mutual funds can provide higher growth potential to outpace property inflation. For shorter timelines (under 3 to 5 years), lower-volatility options like debt or conservative hybrid funds help preserve capital.
Why is it critical to de-risk the portfolio as the purchase date approaches?
Equities fluctuate with market cycles. If a sharp market downturn occurs just months before your home purchase, an equity-heavy portfolio could decline sharply, leaving you short on funds. Gradually transferring your accumulated corpus into liquid or conservative instruments protects the money when it is time to complete the transaction.
Do taxes affect the final down payment corpus?
Yes. The market value displayed in your investment portfolio is before taxes. Mutual fund redemptions are subject to capital gains taxes based on asset type and holding period (such as long-term capital gains taxes under Section 112A for equity funds). Accounting for tax liabilities in advance ensures you have the exact net cash required at closing.




